10-Q: Quarterly report [Sections 13 or 15(d)]
Published on November 10, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
_________________________
FORM 10-Q
_________________________
(Mark One)
x | QUARTERLY REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 | ||||
For the quarterly period ended September 30, 2026
OR
o | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 | ||||
For the transition period from ___________ to ___________
Commission file number 001-42813
_________________________
MOUNT LOGAN CAPITAL INC.
(Exact name of registrant as specified in its charter)
_________________________
Delaware | 33-2698952 | |||||||
(State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) | |||||||
650 Madison Ave, 3rd Floor New York, New York | 10022 | |||||||
(Address of Principal Executive Offices) | (Zip Code) | |||||||
(212) 891-2880
Registrant’s telephone number, including area code
Securities registered pursuant to Section 12(b) of the Act:
Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||
| Common Stock, $0.001 par value | MLCI | The Nasdaq Stock Market LLC | ||||||
8.00% Senior Notes Due 2031 | MLCIL | The Nasdaq Stock Market LLC | ||||||
Securities registered pursuant to Section 12(g) of the Act: None
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☒ No ☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes ☒ No ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
Large accelerated filer | ☐ | Accelerated filer | ☐ | |||||||||||
Non-accelerated filer | ☐ | Smaller reporting company | ☒ | |||||||||||
Emerging growth company | ☒ | |||||||||||||
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act). Yes ☐ No ☒
As of November 10, 2026, the registrant had 11,490,883 shares of Common Stock outstanding.
Table of Contents
3
Cautionary Note Regarding Forward-Looking Statements
This Quarterly Report on Form 10-Q contains “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended (the “Securities Act”), and Section 21E of the Securities Exchange Act of 1934, as amended (the “Exchange Act”). Forward-looking statements relate to expectations, beliefs, projections, future plans and strategies, anticipated events or trends and similar expressions concerning matters that are not historical facts. Forward-looking statements reflect the Company’s current views with respect to, among other things, capital resources, portfolio performance and results of operations. Likewise, the Company’s condensed consolidated financial statements and statements regarding anticipated growth in its operations, anticipated market conditions, demographics and results of operations are forward-looking statements. In some cases, you can identify these forward-looking statements by the use of terminology such as “outlook,” “believes,” “expects,” “potential,” “continues,” “may,” “will,” “should,” “could,” “seeks,” “approximately,” “predicts,” “intends,” “plans,” “estimates,” “anticipates” or the negative version of these words or other comparable words or phrases.
The forward-looking statements contained in this Quarterly Report on Form 10-Q are based on the Company’s current expectations and beliefs concerning future developments and their potential effects on the Company. There can be no assurance that future developments affecting the Company will be those that it has anticipated. Actual results may differ materially from those in the forward-looking statements. Some factors that could cause the Company’s actual results to differ include:
•the risk that any synergies from the Business Combination (as defined herein) may not be fully realized or may take longer to realize than expected;
•the risk of litigation related to the Business Combination;
•variability in revenues, earnings, and cash flows and the resulting impact on quarterly earnings trends and stock price volatility;
•the intensity of competition in asset management and insurance markets and constraints on the ability to execute growth strategies and maintain or increase market share or margins;
•reliance on technology and information systems, including third party and systems provided by BC Partners Advisors L.P. (“BCPA”), and risks related to cybersecurity, data integrity, and operational resilience;
•dependence on management’s assumptions, estimates, models, and judgment, and the risk that actual outcomes diverge materially from those assumptions;
•illiquidity of certain assets under management and insurance investments, and the impact of limited liquidity on valuation, portfolio management, and capital allocation;
•dependence on access to financing markets and the availability, cost, and terms of capital and liquidity;
•risks associated with the use of hedging and other risk management instruments, including costs, basis risk, counterparty exposure, and potential ineffectiveness;
•adverse political, market, and economic conditions and their effects on investment performance, funding costs, client activity, and policyholder behavior;
•dependence on BCPA and key BCPA personnel;
•actual and potential conflicts of interest arising from the relationship with BCPA;
•concentration risk associated with managing a limited number of funds and investments;
•complexities and subjectivity in valuing illiquid assets, including model risk and sensitivity to assumptions;
•the heavily regulated nature of the insurance business; and
•the increased expenses and compliance requirements associated with being a U.S. public company.
These forward-looking statements involve a number of risks, uncertainties (some of which are beyond the Company’s control) or other assumptions that may cause actual results or performance to be materially different from those expressed or implied by these forward-looking statements. These risks and uncertainties include, but are not limited to, those factors described under the section entitled “Item 1A. Risk Factors” of our Annual Report on Form 10-K for the fiscal year ended December 31, 2025, which was filed with the Securities and Exchange Commission (“SEC”) on March 19, 2026. Should one or more of these risks or uncertainties materialize, or should any of the assumptions prove incorrect, actual results may vary in material respects from those projected in these forward-looking statements. The Company undertakes no obligation to update or revise any forward-looking statements, whether as a result of new information, future events or otherwise, except as may be required under applicable securities laws.
Unless the context otherwise requires, (i) all references in this Quarterly Report on Form 10-Q following the closing of the Business Combination on September 12, 2025 to “we,” “us,” “our,” the “Company,” and “Mount Logan” refer to
4
Mount Logan Capital Inc. (formerly, Yukon New Parent, Inc.), as the registrant, and its consolidated subsidiaries and (ii) all references prior to the closing refer to Legacy Mount Logan (as defined herein). The Mount Logan logo and our other registered or common law trademarks, service marks, or trade names appearing in this Quarterly Report on Form 10-Q are the property of Mount Logan Capital Inc. Other trade names, trademarks, and service marks used in this Quarterly Report on Form 10-Q are the property of their respective owners.
5
Part I - Financial Information
Item 1. Financial Statements
6
MOUNT LOGAN CAPITAL INC.
CONDENSED CONSOLIDATED STATEMENTS OF FINANCIAL POSITION (UNAUDITED)
| (in thousands, except per share data) | September 30, 2026 | December 31, 2025 | ||||||||||||
| ASSETS | ||||||||||||||
| Asset Management | ||||||||||||||
| Cash and cash equivalents | $ | 3,065 | $ | 14,999 | ||||||||||
Investments (including related party amounts of $10,219 and $25,423 at September 30, 2026 and December 31, 2025, respectively) | 10,775 | 29,298 | ||||||||||||
| Intangible assets | 24,360 | 10,961 | ||||||||||||
Other assets (including related party amounts of $1,852 and $5,245 at September 30, 2026 and December 31, 2025, respectively) | 9,968 | 11,165 | ||||||||||||
| 48,168 | 66,423 | |||||||||||||
| Insurance Solutions | ||||||||||||||
| Cash and cash equivalents | 40,546 | 88,723 | ||||||||||||
| Restricted cash | 19,241 | 9,973 | ||||||||||||
Investments (including related party amounts of $16,009 and $20,867 at September 30, 2026 and December 31, 2025, respectively) | 862,638 | 956,808 | ||||||||||||
| Derivatives | — | 481 | ||||||||||||
| Assets of consolidated variable interest entities | ||||||||||||||
| Cash and cash equivalents | 16,731 | 30,030 | ||||||||||||
| Investments | 128,681 | 120,680 | ||||||||||||
| Other assets | 1,100 | 955 | ||||||||||||
| Reinsurance recoverable | 236,875 | 272,918 | ||||||||||||
| Intangible assets | 2,444 | 2,444 | ||||||||||||
| Deferred acquisition costs | 4,119 | 6,791 | ||||||||||||
| Goodwill | 30,193 | 30,193 | ||||||||||||
| Other assets | 19,020 | 14,299 | ||||||||||||
| 1,361,588 | 1,534,295 | |||||||||||||
| Total assets | $ | 1,409,756 | $ | 1,600,718 | ||||||||||
| LIABILITIES | ||||||||||||||
| Asset Management | ||||||||||||||
| Due to related parties | $ | 14,285 | $ | 11,844 | ||||||||||
| Debt obligations | 98,392 | 76,250 | ||||||||||||
| Accrued expenses and other liabilities | 4,853 | 9,515 | ||||||||||||
| 117,530 | 97,609 | |||||||||||||
| Insurance Solutions | ||||||||||||||
| Future policy benefits | 698,909 | 781,881 | ||||||||||||
| Interest sensitive contract liabilities | 281,283 | 363,981 | ||||||||||||
| Funds held under reinsurance contracts | 222,028 | 237,143 | ||||||||||||
| Debt obligations | 12,000 | 17,250 | ||||||||||||
| Derivatives | 11,596 | 1,388 | ||||||||||||
| Accrued expenses and other liabilities | 3,738 | 10,510 | ||||||||||||
| 1,229,554 | 1,412,153 | |||||||||||||
| Total liabilities | $ | 1,347,084 | $ | 1,509,762 | ||||||||||
| Commitments and Contingencies (See Note 24) | ||||||||||||||
| EQUITY | ||||||||||||||
Common shares, $0.001 par value, 150,000,000 shares authorized, 11,490,883 and 12,786,770 shares issued and outstanding as of September 30, 2026 and December 31, 2025, respectively | $ | 11 | $ | 13 | ||||||||||
| Warrants | 1,426 | 1,426 | ||||||||||||
| Additional paid-in-capital | 163,039 | 177,099 | ||||||||||||
| Retained earnings (accumulated deficit) | (135,625) | (120,746) | ||||||||||||
| Accumulated other comprehensive income (loss) | 33,821 | 33,164 | ||||||||||||
| Total equity | 62,672 | 90,956 | ||||||||||||
| Total liabilities and equity | $ | 1,409,756 | $ | 1,600,718 | ||||||||||
See accompanying notes to the condensed consolidated financial statements (unaudited).
7
MOUNT LOGAN CAPITAL INC.
8
CONDENSED CONSOLIDATED STATEMENTS OF OPERATIONS (UNAUDITED)
| Three months ended September 30, | Nine months ended September 30, | |||||||||||||||||||||||||
| (in thousands, except per share data) | 2026 | 2025 | 2026 | 2025 | ||||||||||||||||||||||
| REVENUES | ||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||
| Management fees | $ | 1,874 | $ | 1,851 | $ | 5,204 | $ | 7,900 | ||||||||||||||||||
| Incentive fees | — | 431 | 813 | 1,208 | ||||||||||||||||||||||
| Advisory and transaction fees, net | — | — | 66 | — | ||||||||||||||||||||||
| Equity investment earning | 144 | 481 | 659 | 805 | ||||||||||||||||||||||
| 2,018 | 2,763 | 6,742 | 9,913 | |||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||
| Net premiums | (4,389) | (4,492) | (13,107) | (12,743) | ||||||||||||||||||||||
| Product charges | 143 | 184 | 429 | 1,766 | ||||||||||||||||||||||
| Net investment income | 17,181 | 16,992 | 49,126 | 48,621 | ||||||||||||||||||||||
| Net realized and change in unrealized gains (losses) from investment activities | (8,694) | 3,775 | (13,224) | 9,085 | ||||||||||||||||||||||
| Net revenues of consolidated variable interest entities | 1,701 | 2,797 | 3,565 | 9,979 | ||||||||||||||||||||||
| Net investment income (loss) on funds withheld | 2,763 | (10,656) | (3,558) | (23,232) | ||||||||||||||||||||||
| Other income | 2,128 | 76 | 2,272 | 230 | ||||||||||||||||||||||
| 10,833 | 8,676 | 25,503 | 33,706 | |||||||||||||||||||||||
| Total revenues | 12,851 | 11,439 | 32,245 | 43,619 | ||||||||||||||||||||||
| EXPENSES | ||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||
| Administration and servicing fees | 3,764 | 1,564 | 10,708 | 4,613 | ||||||||||||||||||||||
| Transaction costs | 17 | 3,185 | 51 | 10,483 | ||||||||||||||||||||||
| Compensation and benefits | 512 | 4,161 | 938 | 8,377 | ||||||||||||||||||||||
| Amortization and impairment of intangible assets | 512 | 8,272 | 1,630 | 11,071 | ||||||||||||||||||||||
| Interest and other credit facility expenses | 2,185 | 1,970 | 6,362 | 5,876 | ||||||||||||||||||||||
| General, administrative and other | 2,400 | 2,980 | 7,273 | 5,961 | ||||||||||||||||||||||
| 9,390 | 22,132 | 26,962 | 46,381 | |||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||
Net policy benefit and claims (remeasurement gain on policy liabilities of $3,907 and $14,430 and $3,846 and $6,871 for the three and nine months ended September 30, 2026 and 2025, respectively) | (2,393) | (2,118) | (9,309) | (1,389) | ||||||||||||||||||||||
| Interest sensitive contract benefits | 4,171 | 4,154 | 12,639 | 11,969 | ||||||||||||||||||||||
| Amortization of deferred acquisition costs | 1,431 | 929 | 2,842 | 2,389 | ||||||||||||||||||||||
| Compensation and benefits | — | 73 | — | 540 | ||||||||||||||||||||||
| Interest expense | 300 | 408 | 1,018 | 1,143 | ||||||||||||||||||||||
General, administrative and other (including related party amounts of $1,641 and $4,993 and $1,773 and $5,258 for the three and nine months ended September 30, 2026 and 2025, respectively) | 3,131 | 3,338 | 11,025 | 10,294 | ||||||||||||||||||||||
| 6,640 | 6,784 | 18,215 | 24,946 | |||||||||||||||||||||||
| Total expenses | 16,030 | 28,916 | 45,177 | 71,327 | ||||||||||||||||||||||
| Investment and other income (loss) - Asset Management | ||||||||||||||||||||||||||
| Net realized and change in unrealized gains (losses) from investment activities | (1,044) | 1,342 | (2,362) | 3,050 | ||||||||||||||||||||||
| Dividend income | 9 | 22 | 74 | 89 | ||||||||||||||||||||||
| Interest income | 282 | 275 | 967 | 814 | ||||||||||||||||||||||
| Other income (loss), net | 207 | 251 | 853 | 556 | ||||||||||||||||||||||
| Loss on extinguishment of debt | — | — | (472) | — | ||||||||||||||||||||||
| Gain on acquisition | — | 4,457 | 0 | 4457 | ||||||||||||||||||||||
| Total investment and other income (loss) | (546) | 6,347 | (940) | 8,966 | ||||||||||||||||||||||
| Income (loss) before taxes | (3,725) | (11,130) | (13,872) | (18,742) | ||||||||||||||||||||||
| Income tax (expense) benefit — Asset Management | — | (2,306) | — | (2,333) | ||||||||||||||||||||||
| Net income (loss) | $ | (3,725) | $ | (13,436) | $ | (13,872) | $ | (21,075) | ||||||||||||||||||
| Earnings per share | ||||||||||||||||||||||||||
| Net income (loss) attributable to common shareholders - Basic and Diluted | $ | (0.33) | $ | (1.64) | $ | (1.21) | $ | (2.93) | ||||||||||||||||||
| Net income (loss) attributable to common shareholders - Diluted | (0.33) | (1.64) | (1.21) | (2.93) | ||||||||||||||||||||||
| Weighted average shares outstanding – Basic and Diluted | 11,313,555 | 8,174,426 | 11,430,978 | 7,185,669 | ||||||||||||||||||||||
| Weighted average shares outstanding – Diluted | 11,313,555 | 8,174,426 | 11,430,978 | 7,185,669 | ||||||||||||||||||||||
9
MOUNT LOGAN CAPITAL INC.
CONDENSED CONSOLIDATED STATEMENTS OF COMPREHENSIVE INCOME (LOSS) (UNAUDITED)
| Three months ended September 30, | Nine months ended September 30, | |||||||||||||||||||||||||
| (in thousands, except per share data) | 2026 | 2025 | 2026 | 2025 | ||||||||||||||||||||||
| Net income (loss) | $ | (3,725) | $ | (13,436) | $ | (13,872) | $ | (21,075) | ||||||||||||||||||
| Other comprehensive income (loss), before tax: | ||||||||||||||||||||||||||
| Unrealized investment gains (losses) on available-for-sale securities | (7,742) | 4,498 | (9,555) | 6,184 | ||||||||||||||||||||||
| Unrealized gains (losses) on hedging instruments | (8,119) | 501 | (10,689) | 5,237 | ||||||||||||||||||||||
| Remeasurement gains (losses) on future policy benefits and reinsurance recoverable related to discount rate | 20,509 | (7,175) | 20,901 | (15,167) | ||||||||||||||||||||||
| Other comprehensive income (loss), before tax | 4,648 | (2,176) | 657 | (3,746) | ||||||||||||||||||||||
| Income tax expense (benefit) related to other comprehensive income (loss) | — | — | — | — | ||||||||||||||||||||||
| Other comprehensive income (loss) | 4,648 | (2,176) | 657 | (3,746) | ||||||||||||||||||||||
| Comprehensive income (loss) | $ | 923 | $ | (15,612) | $ | (13,215) | $ | (24,821) | ||||||||||||||||||
See accompanying notes to the condensed consolidated financial statements (unaudited).
10
MOUNT LOGAN CAPITAL INC.
CONDENSED CONSOLIDATED STATEMENTS OF CHANGES IN EQUITY (UNAUDITED)
(in thousands, except for number of shares)
| Three and nine months ended September 30, 2026 | Number of Voting Common Shares | Par Value of Common Shares | Warrants | Additional Paid in Capital | Retained Earnings (Accumulated Deficit) | Accumulated Other Comprehensive Income (loss) | Total Equity | |||||||||||||||||||||||||||||||||||||
| Balance at July 1, 2026 | 11,188,768 | $ | 11 | $ | 1,426 | $ | 161,713 | $ | (131,562) | $ | 29,173 | $ | 60,761 | |||||||||||||||||||||||||||||||
| Share issuance for investment purchase | 302,115 | — | — | 904 | — | — | 904 | |||||||||||||||||||||||||||||||||||||
| Equity based compensation | — | — | — | 422 | — | — | 422 | |||||||||||||||||||||||||||||||||||||
| Common shares repurchased | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
Shareholder dividends ($0.03 per share) | — | — | — | — | (338) | — | (338) | |||||||||||||||||||||||||||||||||||||
| Net income (loss) | — | — | — | — | (3,725) | — | (3,725) | |||||||||||||||||||||||||||||||||||||
| Other comprehensive income (loss) | — | — | — | — | — | 4,648 | 4,648 | |||||||||||||||||||||||||||||||||||||
| Balance at September 30, 2026 | 11,490,883 | $ | 11 | $ | 1,426 | $ | 163,039 | $ | (135,625) | $ | 33,821 | $ | 62,672 | |||||||||||||||||||||||||||||||
| Balance at January 1, 2026 | 12,786,770 | $ | 13 | $ | 1,426 | $ | 177,099 | $ | (120,746) | $ | 33,164 | $ | 90,956 | |||||||||||||||||||||||||||||||
| Share issuance for investment purchase | 302,115 | — | — | 904 | — | — | 904 | |||||||||||||||||||||||||||||||||||||
| Equity based compensation | (7,401) | — | — | 501 | — | — | 501 | |||||||||||||||||||||||||||||||||||||
| Common shares repurchased | (1,590,601) | (2) | — | (15,465) | — | — | (15,467) | |||||||||||||||||||||||||||||||||||||
Shareholder dividends ($0.09 per share) | — | — | — | — | (1,007) | — | (1,007) | |||||||||||||||||||||||||||||||||||||
| Net income (loss) | — | — | — | — | (13,872) | — | (13,872) | |||||||||||||||||||||||||||||||||||||
| Other comprehensive income (loss) | — | — | — | — | — | 657 | 657 | |||||||||||||||||||||||||||||||||||||
| Balance at September 30, 2026 | 11,490,883 | $ | 11 | $ | 1,426 | $ | 163,039 | $ | (135,625) | $ | 33,821 | $ | 62,672 | |||||||||||||||||||||||||||||||
| Three and nine months ended September 30, 2025 | Number of Voting Common Shares | Par Value of Common Shares | Warrants | Additional Paid in Capital | Retained Earnings (Accumulated Deficit) | Accumulated Other Comprehensive Income (Loss) | Total Equity | |||||||||||||||||||||||||||||||||||||
| Balance at July 1, 2025 | 6,789,843 | $ | 7 | $ | 1,426 | $ | 129,531 | $ | (66,727) | $ | 35,471 | $ | 99,708 | |||||||||||||||||||||||||||||||
| Share Issuance for reverse acquisition | 5,666,700 | 6 | — | 46,806 | — | — | 46,812 | |||||||||||||||||||||||||||||||||||||
| Share issuance for investment purchase | 122,308 | — | — | 870 | — | — | 870 | |||||||||||||||||||||||||||||||||||||
| Equity based compensation | — | — | — | 2,124 | — | — | 2,124 | |||||||||||||||||||||||||||||||||||||
| Restricted Share Units release | 368,578 | — | — | (798) | — | — | (798) | |||||||||||||||||||||||||||||||||||||
| Common shares repurchased | (160,637) | — | — | (1,434) | — | — | (1,434) | |||||||||||||||||||||||||||||||||||||
Shareholder dividends ($0.06 per share) | — | — | — | — | (427) | — | (427) | |||||||||||||||||||||||||||||||||||||
| Net income (loss) | — | — | — | — | (13,436) | — | (13,436) | |||||||||||||||||||||||||||||||||||||
| Other comprehensive income (loss) | — | — | — | — | — | (2,176) | (2,176) | |||||||||||||||||||||||||||||||||||||
| Balance at September 30, 2025 | 12,786,792 | $ | 13 | $ | 1,426 | $ | 177,099 | $ | (80,590) | $ | 33,295 | $ | 131,243 | |||||||||||||||||||||||||||||||
| Balance at January 1, 2025 | 6,133,631 | $ | 6 | $ | 1,426 | $ | 123,889 | $ | (58,279) | $ | 37,041 | $ | 104,083 | |||||||||||||||||||||||||||||||
| Share Issuance for reverse acquisition | 5,666,700 | 6 | — | 46,806 | — | — | 46,812 | |||||||||||||||||||||||||||||||||||||
| Share issuance for investment purchase | 760,188 | 1 | — | 5,869 | — | — | 5,870 | |||||||||||||||||||||||||||||||||||||
| Equity based compensation | 4,101 | — | — | 2,843 | — | — | 2,843 | |||||||||||||||||||||||||||||||||||||
| Restricted Share Units release | 382,809 | — | — | (874) | — | — | (874) | |||||||||||||||||||||||||||||||||||||
| Common shares repurchased | (160,637) | — | — | (1,434) | — | — | (1,434) | |||||||||||||||||||||||||||||||||||||
Shareholder dividends ($0.18 per share) | — | — | — | — | (1,236) | — | (1,236) | |||||||||||||||||||||||||||||||||||||
| Net income (loss) | — | — | — | — | (21,075) | — | (21,075) | |||||||||||||||||||||||||||||||||||||
| Other comprehensive income (loss) | — | — | — | — | — | (3,746) | (3,746) | |||||||||||||||||||||||||||||||||||||
| Balance at September 30, 2025 | 12,786,792 | $ | 13 | $ | 1,426 | $ | 177,099 | $ | (80,590) | $ | 33,295 | $ | 131,243 | |||||||||||||||||||||||||||||||
See accompanying notes to the condensed consolidated financial statements (unaudited).
11
MOUNT LOGAN CAPITAL INC.
CONDENSED CONSOLIDATED STATEMENTS OF CASH FLOWS (UNAUDITED)
| Nine months ended September 30, | ||||||||||||||
| (in thousands) | 2026 | 2025 | ||||||||||||
| Cash Flows from Operating Activities | ||||||||||||||
| Net income (loss) | $ | (13,872) | $ | (21,075) | ||||||||||
| Adjustments to reconcile net income (loss) to net cash used in operating activities: | ||||||||||||||
| Net realized (gains) losses on investments | 11,939 | 2,697 | ||||||||||||
| Net realized (gains) losses on foreign currency | — | (33) | ||||||||||||
| Net change in unrealized (gains) losses on investments | 17,749 | (11,216) | ||||||||||||
| Change in fair value of debt obligation | — | (1,339) | ||||||||||||
| Payment in-kind interest | 909 | 181 | ||||||||||||
| Equity investment earnings | (659) | (805) | ||||||||||||
| Amortization of debt issuance costs | 174 | 377 | ||||||||||||
| Amortization of deferred acquisition costs | 2,842 | 2,389 | ||||||||||||
| Amortization of intangible assets | 1,630 | 3,103 | ||||||||||||
| Impairment of intangible assets | — | 7,968 | ||||||||||||
| Net amortization of premiums and accretion of discounts on investments | (519) | 216 | ||||||||||||
| Equity based compensation | 501 | 1,969 | ||||||||||||
| Increase (decrease) in estimated credit losses | (7,479) | (360) | ||||||||||||
| Write-off of unamortized debt issuance costs | 472 | — | ||||||||||||
| Merger Transaction Activity | (2,835) | — | ||||||||||||
| Gain on reverse acquisition of business | — | (4,457) | ||||||||||||
| Gain on recapture | (1,849) | — | ||||||||||||
| (Increase) decrease in operating assets: | ||||||||||||||
| Reinsurance recoverable | 8,053 | 7,939 | ||||||||||||
| Change in deferred acquisition costs | (170) | (3,393) | ||||||||||||
| Distributions from equity method investments | 2,169 | 1,314 | ||||||||||||
| Other assets | (2,204) | (1,046) | ||||||||||||
| Other assets of consolidated VIEs | (145) | 519 | ||||||||||||
| Purchases of investments by consolidated VIEs | (63,465) | (66,073) | ||||||||||||
| Proceeds from sale of investments by consolidated VIEs | 49,530 | 61,074 | ||||||||||||
| Increase (decrease) in operating liabilities: | ||||||||||||||
| Due to related parties | 2,442 | (2,182) | ||||||||||||
| Future policy benefits | (34,082) | (18,527) | ||||||||||||
| Interest sensitive contract liabilities | 12,639 | 11,969 | ||||||||||||
| Funds held under reinsurance contracts | (15,115) | 3,698 | ||||||||||||
| Accrued expenses and other liabilities | (4,208) | (547) | ||||||||||||
| Net cash used in operating activities | $ | (35,553) | $ | (25,640) | ||||||||||
| Investing Activities | ||||||||||||||
| Purchases of investments | (244,139) | (218,720) | ||||||||||||
| Proceeds received from reverse acquisition of business | — | 36,794 | ||||||||||||
| Proceeds from sales and repayments of investments | 249,393 | 252,944 | ||||||||||||
| Net cash provided by (used in) investing activities | $ | 5,254 | $ | 71,018 | ||||||||||
| Financing Activities | ||||||||||||||
| Shareholder dividends | (1,007) | (1,236) | ||||||||||||
| Repurchase of common shares | (15,467) | (1,434) | ||||||||||||
| Issuance of common shares | 904 | — | ||||||||||||
| Proceeds from borrowings of asset management business | 45,597 | — | ||||||||||||
| Repayments of borrowings of asset management business | (24,500) | (2,000) | ||||||||||||
| Financing costs paid and deferred | (2,324) | — | ||||||||||||
| Proceeds from borrowings of insurance business | — | 3,000 | ||||||||||||
| Repayments of borrowings of insurance business | (5,250) | — | ||||||||||||
| Deposits on investment-type policies and contracts | 911 | 42,996 | ||||||||||||
| Withdrawals on investment-type policies and contracts | (32,707) | (26,592) | ||||||||||||
12
| Nine months ended September 30, | ||||||||||||||
| (in thousands) | 2026 | 2025 | ||||||||||||
| Net cash provided by (used in) financing activities | $ | (33,843) | $ | 14,734 | ||||||||||
| Effects of exchange rate changes on cash and restricted cash | ||||||||||||||
| Net increase (decrease) in cash, cash equivalents and restricted cash, and cash and cash equivalents of consolidated VIEs | (64,142) | 60,112 | ||||||||||||
| Cash, cash equivalents and restricted cash, and cash and cash equivalents of consolidated VIEs, beginning of the period | 143,725 | 101,703 | ||||||||||||
| Cash, cash equivalents and restricted cash, and cash and cash equivalents of consolidated VIEs, end of period | $ | 79,583 | $ | 161,815 | ||||||||||
| Cash, cash equivalents, restricted cash and cash and cash equivalents of consolidated VIEs | ||||||||||||||
| Asset Management | ||||||||||||||
| Cash and cash equivalents | 3,065 | 22,283 | ||||||||||||
| Total Asset Management | 3,065 | 22,283 | ||||||||||||
| Insurance Solutions | ||||||||||||||
| Cash and cash equivalents | 40,546 | 108,242 | ||||||||||||
| Restricted cash | 19,241 | 9,967 | ||||||||||||
| Cash and cash equivalents of consolidated VIEs | 16,731 | 21,323 | ||||||||||||
| Total Insurance Solutions | 76,518 | 139,532 | ||||||||||||
| Total cash, cash equivalents and restricted cash, and cash and cash equivalents of consolidated VIEs | $ | 79,583 | $ | 161,815 | ||||||||||
| Supplemental disclosures of cash flow information | ||||||||||||||
| Interest received | 60,722 | 61,284 | ||||||||||||
| Interest paid | 5,865 | 6,410 | ||||||||||||
| Dividends received | 389 | 1,085 | ||||||||||||
| Income taxes paid | 76 | 256 | ||||||||||||
| Supplemental Disclosures of Non-Cash Investing and Financing Activities | ||||||||||||||
| Reduction in investments relating to recapture of reinsurance agreement | 60,981 | — | ||||||||||||
| Issuance of common shares for vested Restricted Share Units | — | 2,461 | ||||||||||||
| Issuance of common shares for investment purchases | — | 52,682 | ||||||||||||
| Issuance of common shares for share based compensation | — | 45 | ||||||||||||
| Write off of debt investment | 13,586 | — | ||||||||||||
| Acquisition of intangible assets | 15,029 | — | ||||||||||||
See accompanying notes to the condensed consolidated financial statements (unaudited).
13
MOUNT LOGAN CAPITAL INC.
NOTES TO CONDENSED CONSOLIDATED FINANCIAL STATEMENTS (UNAUDITED)
(All amounts in thousands, except share and per share data, and except where noted)
Note 1. Organization
Mount Logan, together with its consolidated subsidiaries (the “Company”) is a diversified alternative asset management and insurance solutions platform operating through two business segments: Asset Management and Insurance Solutions. Our Asset Management segment is conducted by Mount Logan Management LLC (“ML Management”), our SEC-registered investment adviser, which manages a significant portion of our Assets Under Management (“AUM”) across our various managed funds supported by permanent and semi-permanent capital bases. ML Management also directly manages the capital of our wholly-owned insurance company, Ability Insurance Company (“Ability”), for the benefit of policyholders. The Company’s Insurance Solutions segment is conducted by Ability, a Nebraska domiciled insurer, which specializes in reinsuring annuity products for the increasing number of individuals seeking to fund retirement needs and represents all of our insurance solutions operations.
On September 12, 2025 (the “Closing Date”), the Company completed a business combination with 180 Degree Capital Corp. ("TURN") and Mount Logan Capital Inc. ("Legacy Mount Logan"), accounted for as a reverse acquisition with Legacy Mount Logan as the accounting acquirer. Accordingly, the Company's condensed consolidated financial statements present the historical results of Legacy Mount Logan prior to September 12, 2025, and those of the combined company thereafter. Refer to Note 3. Business combinations and Asset Acquisitions for more information about the reverse acquisition and the financial reporting impacts.
Unless the context otherwise requires, all references to the “Company,” “Mount Logan,” or “we” refer to (i) the Company on or after the Closing Date, and (ii) Legacy Mount Logan prior to the Closing Date.
Note 2. Summary of significant accounting policies
Basis of presentation and Consolidation
The accompanying unaudited Condensed Consolidated Financial Statements (“Condensed Consolidated Financial Statements”) have been prepared in accordance with accounting principles generally accepted in the United States of America (“U.S. GAAP”). Certain disclosures included in the annual audited Consolidated Financial Statements have been condensed or omitted as they are not required for interim Condensed Consolidated Financial Statements. The operating results presented for interim periods are not necessarily indicative of the results that may be expected for any other interim period or for the entire year. These Condensed Consolidated Financial Statements should be read in conjunction with the annual audited financial statements and the notes thereto included in the Company’s Annual Report on Form 10-K for the year ended December 31, 2025 filed with the SEC on March 19, 2026.
The Condensed Consolidated Financial Statements reflect all adjustments, both normal and recurring which, in the opinion of management, are necessary for the fair presentation of the Company’s Condensed Consolidated Financial Statements for the periods presented.
The results of the Company and its subsidiaries are presented on a consolidated basis. All intercompany transactions and balances are eliminated on consolidation.
The Company's Asset Management and Insurance Solutions segments possess distinct characteristics, and as a result are presented separately from each other. The Company believes that separate presentation provides a more informative view of the Company’s consolidated financial position and results of operations than an aggregated presentation and that reporting insurance solutions separately is appropriate given, among other factors, the relative significance of Ability's policy liabilities, which do not provide recourse to the remaining assets of Mount Logan.
For a summary of our significant accounting policies, see Note 2. Summary of significant accounting policies included in our Annual report on Form 10-K for the year ended December 31, 2025. During the three and nine months ended September 30, 2026, there were no material updates to our significant accounting policies.
The number of shares issued and outstanding, earnings per share, additional paid-in capital, dividends paid per share and all references to share quantities of the Company have been retrospectively adjusted to reflect the Company’s existing capital structure post merger with TURN. Refer to Note 3. Business combinations and Asset Acquisitions for further detail.
14
Due to rounding, numbers presented throughout these Condensed Consolidated Financial Statements may not add up precisely to the totals provided and percentages may not precisely reflect the absolute figures.
Recently issued accounting pronouncements
In November 2024, the FASB issued ASU 2024-03, Income Statement – Reporting Comprehensive Income – Expense Disaggregation Disclosures. This ASU requires disaggregation of certain expense captions into specified categories in disclosures within the footnotes to the financial statements. The ASU requires presentation in a tabular format of each pertinent expense category on the face of the income statement, such as employee compensation, depreciation, amortization of intangible assets, and other applicable expenses. In January 2025, the FASB issued ASU 2025-01, Income Statement—Reporting Comprehensive Income—Expense Disaggregation Disclosures: Clarifying the Effective Date. ASU 2024-03 will be effective for public business entities for annual reporting periods beginning after December 15, 2026 (for all other entities - December 15, 2027) and interim reporting periods beginning after December 15, 2027 (for all other entities - December 15, 2028) with early adoption permitted, as clarified in ASU 2025-01. The Company is currently evaluating the impact of adopting ASU 2024-03 on its Condensed Consolidated Financial Statements.
In May 2025, the FASB issued ASU 2025–03, Business Combinations (Topic 805) and Consolidation (Topic 810): Determining the Accounting Acquirer in the Acquisition of a Variable Interest Entity (“ASU 2025–03”). This ASU requires an entity involved in an acquisition transaction effected primarily by exchanging equity interests when the legal acquiree is a variable interest entity (“VIE”) that meets the definition of a business to consider factors to determine which entity is the accounting acquirer. When considering those factors, the reporting entity may determine that a transaction in which the legal acquiree is a VIE represents a reverse acquisition. The update will be effective for all entities for annual periods (and interim periods in annual reporting periods) beginning after December 15, 2026. The Company is currently evaluating the impact of adopting this ASU on its Condensed Consolidated Financial Statements.
Note 3. Business combinations and Asset Acquisitions
Acquisition of 180 Degree Capital
On September 12, 2025, the Company completed its Business Combination with TURN, accounted for as a reverse acquisition under ASC 805, with Legacy Mount Logan as the accounting acquirer. The measurement period for the Business Combination ended during the three and nine months ended September 30, 2026, and purchase accounting for the transaction is final. There is no contingent consideration or indemnification asset associated with the transaction. See Note 3 to the consolidated financial statements included in the Company’s Annual Report on Form 10-K for the year ended December 31, 2025, for further detail regarding the business combination and discussion of the $4.5 million bargain purchase gain recognized in “Gain on acquisition” in the consolidated statements of operations.
Yieldstreet Alternative Income Fund Inc. Transition Services and Sub-advisory Agreements
On March 18, 2026, ML Management, a wholly-owned subsidiary of the Company, entered into a Transition Services Agreement (the "TSA") and a Sub-Advisory Agreement with Willow Asset Management LLC ("Willow"), in connection with an Agreement and Plan of Reorganization among Opportunistic Credit Interval Fund ("SOFIX"), Yieldstreet Alternative Income Fund Inc. ("YS AIF"), ML Management, and Willow, pursuant to which SOFIX acquired the assets and assumed the liabilities of YS AIF. The transactions closed on August 24, 2026 (the "YS AIF Transaction Closing Date").
Under the TSA, Willow granted ML Management an exclusive, worldwide license to certain books, records, and data files relating to YS AIF (the "YS AIF assets"), together with transition services over a two-year period following the YS AIF Transaction Closing Date, for aggregate consideration of $5.0 million, consisting of $2.0 million in cash paid at Closing, $1.0 million in MLCI restricted shares issued to Willow at Closing, and up to $2.0 million payable as rebates against fees otherwise due to ML Management under the Sub-Advisory Agreement, described below.
Under the Sub-Advisory Agreement, ML Management acts as non-discretionary sub-adviser to a legacy private credit portfolio managed by Willow, unrelated to the YS AIF assets, in exchange for a sub-advisory fee.
The Company evaluated the TSA and the Sub-Advisory Agreement as a single unit of account for accounting purposes, as the agreements were executed contemporaneously, contain cross-referenced termination and payment
15
provisions, and a portion of the TSA consideration is structurally settled through fees generated under the Sub-Advisory Agreement, consistent with the indicators in ASC 805-10-25-20 through 25-21.
The Company concluded the YS AIF assets acquired under the TSA do not meet the definition of a business under ASC 805-10-55-3A through 55-9, as no workforce, substantive process, or output-generating capability transferred to the Company. Accordingly, the transaction is accounted for as an asset acquisition under ASC 805-50. Total consideration was allocated between (i) an intangible asset, representing the YS AIF assets and the associated license, and (ii) the transition services, on a relative-fair-value basis in accordance with ASC 805-50-30-3. The transition services are expensed as consumed over the two-year service period. The intangible asset was valued using an income approach, as no observable market exists for a comparable asset. The asset is tested for impairment annually, and more frequently if events or changes in circumstances indicate that it is more likely than not impaired, and the indefinite-life determination is reassessed each reporting period.
The 302,115 shares (valued at $1.0 million as of the YS AIF Transaction Closing Date) in MLCI restricted shares issued to Willow is accounted for under ASC 718 as consideration for the YS AIF assets, license, and transition services received, measured at grant-date fair value as of the YS AIF Transaction Closing Date, without a discount for lack of marketability associated with the shares' two-year lock-up period, and allocated between the intangible asset and transition services consistent with the allocation described above.
The Company may pay up to $2.0 million in additional TSA consideration in the form of rebates against Sub-Advisory Fees otherwise payable by Willow, recognized incrementally as each $0.25 million tranche becomes probable and estimable, with the resulting adjustment to the cost basis of the acquired assets recognized as a cumulative catch-up adjustment in the period of recognition. This consideration is not accounted for as a reduction of the amount of Sub-Advisory Fee revenue under ASC 606 as the payment is for a distinct service, the fair value of the distinct services are reasonably estimable, and the total consideration payable to Willow does not exceed the fair value of the distinct services received. As of September 30, 2026, none of the rebate had been recognized as additional consideration.
As of September 30, 2026, the carrying value of the intangible asset recognized in connection with this transaction was $2.8 million, and it is not impaired as of September 30, 2026. See Note 11. Goodwill and intangible assets, Intangible assets for further detail.
Separately, on August 24, 2026, restricted stock units with an aggregate value of approximately $0.6 million were issued as inducement grants to six former Willow employees who became employees of BCPA and provide services to the Company under the existing staffing and servicing agreements between the Company and BCPA. The awards were granted in connection with the Sub-Advisory Agreement with Willow under the Nasdaq Listing Rule 5635(c)(4) inducement exemption and are not consideration under the TSA. The awards vest in equal annual installments over three years beginning on the first anniversary of the grant date, subject to continued service, and the related compensation expense is recognized under ASC 718 on a straight-line basis over the vesting period. See Note 22. Related Parties for additional information regarding the staffing and servicing agreements between the Company and BCPA.
Alternative Credit Income Fund (“ACIF”) completed merger with BC Partners Lending Corporation (“BCPL”)
Overview
The Company holds a 24.99% equity interest in Sierra Crest Investment Management LLC ("SCIM"), accounted for under the equity method. The remaining 75.01% of SCIM is owned by BC Partners. Prior to September 29, 2026, SCIM served as the investment manager of ACIF, and the Company was entitled to 100% of the economics of the ACIF management arrangement through a pass-through of SCIM's results. The Company also held a promissory note receivable from SCIM (the "SCIM Note") with a principal balance of $13.6 million, an allowance for credit losses of $0.3 million, accrued interest receivable of $3.8 million, and carried a payable to SCIM of $7.2 million representing the cumulative excess of ACIF expenses over revenues borne by the Company (the "ACIF Economics Payable").
Effective September 29, 2026, ACIF merged with and into BC Partners Lending Corporation ("BCPL") (the "ACIF Merger"). In connection with the ACIF Merger, (i) SCIM and BC Partners Advisors L.P. ("BCPA"), the investment adviser to BCPL, entered into a Revenue Share Agreement under which BCPA pays 29.88% of the management and incentive fees it receives under its investment advisory agreement with BCPL, net of the allocable compensation costs of the BCPL sales force, (the "Revenue Share Amount"); and (ii) SCIM and Mount Logan Capital US Holdings LLC ("MLC USH"), a wholly owned consolidated subsidiary of the Company, entered into an Assignment and Cancellation Agreement (the "Cancellation Agreement") under which SCIM's rights to the Revenue Share Amount were assigned to MLC USH in
16
exchange for the cancellation of the SCIM Note, and the accrued interest receivable and the ACIF Economics Payable were settled against each other. The Revenue Share Agreement continues until mutually terminated by the parties and terminates automatically upon termination of the investment advisory agreement between BCPA and BCPL.
The Company evaluated the Merger Agreement, the Revenue Share Agreement and the Cancellation Agreement together because they were negotiated as a package, are interdependent, and share a single commercial objective. Each component was accounted for under the applicable guidance, as described below.
Cancellation of the SCIM Note and Recognition of the Revenue Share Amount
The Company accounted for the cancellation of the SCIM Note as an extinguishment of a financial asset in exchange for the acquisition of an intangible asset, measured under the asset acquisition cost guidance in ASC 805-50-30-2. The Revenue Share Amount was recorded at $12.2 million, the fair value of the SCIM Note at September 29, 2026, which the Company determined was more clearly evident than the fair value of the Revenue Share Amount. The fair value of the SCIM Note was determined with the assistance of an independent valuation specialist using the income approach with significant unobservable inputs including the discount rate and expected recovery, and is a Level 3 measurement. The Company derecognized the SCIM Note at its net carrying amount of $13.3 million (principal of $13.6 million less allowance for credit losses of $0.3 million) and recognized a loss of $1.1 million in Net realized and change in unrealized gains (losses) from investment activities in the three and nine months ended September 30, 2026. The exchange was a non-cash transaction.
Settlement of Accrued Interest and the ACIF Economics Payable
Under the Cancellation Agreement, the $3.8 million of accrued interest receivable on the SCIM Note was settled against an equal portion of the $7.2 million ACIF Economics Payable. No gain or loss was recognized on the settlement. The remaining balance of $3.4 million (the "Remaining CIF Payable") continues to be recorded as a liability to a related party. The Remaining CIF Payable is repaid, at least quarterly, from one-third of the Revenue Share Amount received by the Company until paid in full, and may be prepaid at the Company's option. The repayment amounts and timing depend on fees earned by BCPA and are not fixed or determinable; accordingly, no interest has been imputed. The Remaining CIF Payable is presented gross and is not offset against the Revenue Share Amount.
Revenue Share Amount Intangible Asset
The Revenue Share Amount is an intangible asset, because it is not a fixed claim on the cash of BCPA and the Company provides no goods or services to ACIF, BCPL, BCPA or SCIM in exchange for it. It is therefore not accounted for as revenue from a contract with a customer, and it does not meet the definition of a derivative because it has no notional amount or payment provision. The Company determined that the asset has an indefinite useful life because the Revenue Share Agreement can be terminated only by mutual agreement or upon termination of the BCPL advisory agreement, which has no stated end date and continues subject to annual approval by the BCPL board of directors or shareholders. The asset is tested for impairment annually, and more frequently if events or changes in circumstances indicate that it is more likely than not impaired, and the indefinite-life determination is reassessed each reporting period. At September 30, 2026, the carrying amount of the asset was $12.2 million, and no impairment was recorded.
Amounts received under the Revenue Share Agreement are recognized in Other income (loss), net as earned, beginning in the fourth quarter of 2026, consistent with the recognition of the BCIC profit share interest revenue received by the Company.
Related Party Transactions
BC Partners provides the Company's personnel and administrative services under staffing and administrative agreements and is an affiliate of the Company, but the Company and BC Partners are not under common control. BCPL and BCPA are affiliates of BC Partners. Each component of the ACIF Merger is therefore a related party transaction. At September 30, 2026, the Company reported the following related party balances arising from the ACIF Merger: Revenue Share Amount intangible asset of $12.2 million; and Remaining CIF Payable due to SCIM of $3.4 million.
17
Note 4. Net realized and change in unrealized gains (losses) from investment activities
The table below summarizes the net realized and change in unrealized gains (losses) from investment activities:
| For the three months ended September 30, | 2026 | 2025 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Net realized gains (losses) | Net unrealized gains (losses) | Credit releases (losses) | Total | Net realized gains (losses) | Net unrealized gains (losses) | Credit releases (losses) | Total | |||||||||||||||||||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Corporate loan | $ | (1,393) | $ | — | $ | 295 | $ | (1,098) | $ | — | $ | — | $ | — | $ | — | ||||||||||||||||||||||||||||||||||
| Equity securities | (1) | (153) | $ | — | (154) | 299 | 1,041 | — | 1,340 | |||||||||||||||||||||||||||||||||||||||||
| Derivatives | — | — | — | — | — | 2 | — | 2 | ||||||||||||||||||||||||||||||||||||||||||
Other invested assets1 | — | 208 | — | 208 | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||
| Debt obligation | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||
| Net realized and change in unrealized gains (losses) from investment activities — Asset Management | $ | (1,394) | $ | 55 | $ | 295 | $ | (1,044) | $ | 299 | $ | 1,043 | $ | — | $ | 1,342 | ||||||||||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Debt securities: | ||||||||||||||||||||||||||||||||||||||||||||||||||
| U.S. state, territories and municipalities | $ | (114) | $ | (107) | $ | — | $ | (221) | $ | — | $ | 13 | $ | — | $ | 13 | ||||||||||||||||||||||||||||||||||
| Other government and agency | — | (139) | — | (139) | — | 208 | — | 208 | ||||||||||||||||||||||||||||||||||||||||||
| Corporate | (605) | (7,388) | — | (7,993) | (706) | 3,645 | — | 2,939 | ||||||||||||||||||||||||||||||||||||||||||
| Asset and mortgage- backed securities | (923) | 213 | — | (710) | (361) | 478 | — | 117 | ||||||||||||||||||||||||||||||||||||||||||
| Corporate loans | 14 | (252) | — | (238) | — | (96) | — | (96) | ||||||||||||||||||||||||||||||||||||||||||
| Mortgage loans | (3,467) | — | 3,838 | 371 | — | — | 544 | 544 | ||||||||||||||||||||||||||||||||||||||||||
| Equity securities | — | (41) | — | (41) | — | (24) | — | (24) | ||||||||||||||||||||||||||||||||||||||||||
| Other invested assets | — | 66 | 211 | 277 | — | 40 | 34 | 74 | ||||||||||||||||||||||||||||||||||||||||||
| Net realized and change in unrealized gains (losses) from investment activities — Insurance Solutions | $ | (5,095) | $ | (7,648) | $ | 4,049 | $ | (8,694) | $ | (1,067) | $ | 4,264 | $ | 578 | $ | 3,775 | ||||||||||||||||||||||||||||||||||
| Investments of consolidated VIEs | (3,573) | 1,837 | — | (1,736) | 73 | (1,405) | — | (1,332) | ||||||||||||||||||||||||||||||||||||||||||
| Net realized and change in unrealized gains (losses) from investment activities — Insurance Solutions including consolidated VIEs | $ | (8,668) | $ | (5,811) | $ | 4,049 | $ | (10,430) | $ | (994) | $ | 2,859 | $ | 578 | $ | 2,443 | ||||||||||||||||||||||||||||||||||
(1) Includes $0.2 million of unrealized gains on purchase receivables that are presented in other assets on the condensed consolidated statements of financial position. Refer to Note 17. Other assets and Accrued expenses and other liabilities for further detail.
18
| For the nine months ended September 30, | 2026 | 2025 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Net realized gains (losses) | Net unrealized gains (losses) | Credit releases (losses) | Total | Net realized gains (losses) | Net unrealized gains (losses) | Credit releases (losses) | Total | |||||||||||||||||||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Corporate loan | $ | (1,393) | $ | — | $ | 299 | $ | (1,094) | $ | — | $ | — | $ | — | $ | — | ||||||||||||||||||||||||||||||||||
| Equity securities | 365 | (1,946) | — | (1,581) | 380 | 1,329 | — | 1,709 | ||||||||||||||||||||||||||||||||||||||||||
| Derivatives | — | — | — | — | — | 2 | — | 2 | ||||||||||||||||||||||||||||||||||||||||||
Other invested assets1 | — | 313 | — | 313 | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||
| Debt obligations | — | — | — | — | — | 1,339 | — | 1,339 | ||||||||||||||||||||||||||||||||||||||||||
| Net realized and change in unrealized gains (losses) from investment activities — Asset Management | $ | (1,028) | $ | (1,633) | $ | 299 | $ | (2,362) | $ | 380 | $ | 2,670 | $ | — | $ | 3,050 | ||||||||||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Debt securities: | ||||||||||||||||||||||||||||||||||||||||||||||||||
| U.S. state, territories and municipalities | $ | (119) | $ | (124) | $ | — | $ | (243) | $ | (4) | $ | 75 | $ | — | $ | 71 | ||||||||||||||||||||||||||||||||||
| Other government and agency | — | (102) | — | (102) | — | 205 | — | 205 | ||||||||||||||||||||||||||||||||||||||||||
| Corporate | (968) | (7,801) | — | (8,769) | (1,773) | 5,881 | — | 4,108 | ||||||||||||||||||||||||||||||||||||||||||
| Asset and mortgage- backed securities | (1,132) | (924) | — | (2,056) | (613) | 294 | — | (319) | ||||||||||||||||||||||||||||||||||||||||||
| Corporate loans | 19 | (1,250) | — | (1,231) | — | 1,330 | — | 1,330 | ||||||||||||||||||||||||||||||||||||||||||
| Mortgage loans | (8,088) | — | 6,810 | (1,278) | — | — | 260 | 260 | ||||||||||||||||||||||||||||||||||||||||||
| Equity securities | 3,597 | (3,425) | — | 172 | (246) | 74 | — | (172) | ||||||||||||||||||||||||||||||||||||||||||
| Other invested assets | — | (87) | 370 | 283 | (755) | 4,257 | 100 | 3,602 | ||||||||||||||||||||||||||||||||||||||||||
| Net realized and change in unrealized gains (losses) from investment activities — Insurance Solutions | $ | (6,691) | $ | (13,713) | $ | 7,180 | $ | (13,224) | $ | (3,391) | $ | 12,116 | $ | 360 | $ | 9,085 | ||||||||||||||||||||||||||||||||||
| Investments of consolidated VIEs | (4,220) | (2,403) | — | (6,623) | 310 | (2,194) | — | (1,884) | ||||||||||||||||||||||||||||||||||||||||||
| Net realized and change in unrealized gains (losses) from investment activities — Insurance Solutions including consolidated VIEs | $ | (10,911) | $ | (16,116) | $ | 7,180 | $ | (19,847) | $ | (3,081) | $ | 9,922 | $ | 360 | $ | 7,201 | ||||||||||||||||||||||||||||||||||
_______________
(1) Includes $0.3 million of unrealized gains on purchase receivables that are presented in other assets on the condensed consolidated statements of financial position. Refer to Note 17. Other assets and Accrued expenses and other liabilities for further detail.
19
Note 5. Net investment income
Net investment income for the Insurance Solutions segment is comprised primarily of Interest income and Dividend income. The table below summarizes Net investment income:
| Three months ended September 30, | Nine months ended September 30, | |||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||
| Debt securities | $ | 11,055 | $ | 11,014 | $ | 32,324 | $ | 33,618 | ||||||||||||||||||
| Corporate loans | 2,882 | 1,707 | 8,273 | 10,622 | ||||||||||||||||||||||
| Derivative income (expense) | (65) | 1,873 | (155) | (1,044) | ||||||||||||||||||||||
| Mortgage loans | 3,191 | 2,320 | 8,978 | 7,054 | ||||||||||||||||||||||
| Equity securities | 82 | 142 | 326 | 536 | ||||||||||||||||||||||
| Other | 481 | 381 | 1,579 | 1,118 | ||||||||||||||||||||||
| Gross investment income: | $ | 17,626 | $ | 17,437 | $ | 51,325 | $ | 51,904 | ||||||||||||||||||
| Less: | ||||||||||||||||||||||||||
| Investment expenses | (445) | (445) | (2,199) | (3,283) | ||||||||||||||||||||||
| Net investment income | $ | 17,181 | $ | 16,992 | $ | 49,126 | $ | 48,621 | ||||||||||||||||||
| Investment income of consolidated VIEs | 3,437 | 4,129 | 10,188 | 11,863 | ||||||||||||||||||||||
| Net investment income — Insurance Solutions, including consolidated VIEs | $ | 20,618 | $ | 21,121 | $ | 59,314 | $ | 60,484 | ||||||||||||||||||
20
Note 6. Investments
The following table outlines the carrying value of the Company’s investments:
| As of | September 30, 2026 | December 31, 2025 | ||||||||||||
| Asset Management | ||||||||||||||
| Corporate loans | $ | — | $ | 13,287 | ||||||||||
| Equity securities | 6,700 | 10,409 | ||||||||||||
| Equity method | 4,007 | 5,517 | ||||||||||||
| Derivatives | — | 13 | ||||||||||||
| Other invested assets | 68 | 72 | ||||||||||||
| Total investments - Asset Management | $ | 10,775 | $ | 29,298 | ||||||||||
| Insurance Solutions | ||||||||||||||
| Debt securities | $ | 576,545 | $ | 632,038 | ||||||||||
| Corporate loans | 111,033 | 124,067 | ||||||||||||
| Mortgage loans | 144,069 | 162,566 | ||||||||||||
| Equity securities | 4,401 | 15,053 | ||||||||||||
| Other invested assets | 26,590 | 23,084 | ||||||||||||
| Total investments - Insurance Solutions | $ | 862,638 | $ | 956,808 | ||||||||||
| Corporate loans of consolidated VIEs | 127,630 | 119,731 | ||||||||||||
| Equity securities of consolidated VIEs | 1,051 | 949 | ||||||||||||
| Total investments - Insurance Solutions, including consolidated VIEs | 991,319 | 1,077,488 | ||||||||||||
| Total investments | $ | 1,002,094 | $ | 1,106,786 | ||||||||||
21
Financial assets
The following tables summarize the measurement categories of financial assets held by the Company as of September 30, 2026, and December 31, 2025:
| As of September 30, 2026 | Fair value | Amortized cost | Fair value option | Total | ||||||||||||||||||||||
| Financial assets | ||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||
| Corporate loans | $ | — | $ | — | $ | — | $ | — | ||||||||||||||||||
| Equity securities | 6,700 | — | — | 6,700 | ||||||||||||||||||||||
| Other invested assets | 68 | — | — | 68 | ||||||||||||||||||||||
Total financial assets — Asset Management¹ | $ | 6,768 | $ | 0 | $ | — | $ | 6,768 | ||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||
| Debt securities: | ||||||||||||||||||||||||||
| U.S. government and agency | $ | 9,362 | $ | — | $ | — | $ | 9,362 | ||||||||||||||||||
| U.S. state, territories and municipalities | 2,385 | — | 1,776 | 4,161 | ||||||||||||||||||||||
| Other government and agency | — | — | 2,366 | 2,366 | ||||||||||||||||||||||
| Corporate | 147,129 | — | 93,825 | 240,954 | ||||||||||||||||||||||
| Asset and mortgage-backed securities | 204,394 | — | 115,308 | 319,702 | ||||||||||||||||||||||
| Corporate loans | — | — | 111,033 | 111,033 | ||||||||||||||||||||||
| Mortgage loans | — | 144,069 | — | 144,069 | ||||||||||||||||||||||
| Equity securities | 4,401 | — | — | 4,401 | ||||||||||||||||||||||
Other invested assets² | 13,740 | 11,819 | 1,031 | 26,590 | ||||||||||||||||||||||
| Total financial assets — Insurance Solutions | $ | 381,411 | $ | 155,888 | $ | 325,339 | $ | 862,638 | ||||||||||||||||||
| Corporate loans of consolidated VIEs | — | — | 127,630 | 127,630 | ||||||||||||||||||||||
| Equity securities of consolidated VIEs | 1,051 | — | — | 1,051 | ||||||||||||||||||||||
| Total financial assets — Insurance Solutions, including consolidated VIEs | 382,462 | 155,888 | 452,969 | 991,319 | ||||||||||||||||||||||
| Total financial assets | $ | 389,230 | $ | 155,888 | $ | 452,969 | $ | 998,087 | ||||||||||||||||||
_______________
(1)The MLC US Holdings Credit Facility (as hereinafter defined) is collateralized by assets held by MLC US Holdings, including assets totaling $15.2 million as of September 30, 2026.
(2)Other invested assets primarily include structured securities and loan receivables.
22
| As of December 31, 2025 | Fair value | Amortized cost | Fair value option | Total | ||||||||||||||||||||||
| Financial assets | ||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||
| Corporate loans | $ | — | $ | 13,287 | $ | — | $ | 13,287 | ||||||||||||||||||
| Equity securities | 10,409 | — | — | 10,409 | ||||||||||||||||||||||
| Derivatives | 13 | — | — | 13 | ||||||||||||||||||||||
| Other invested assets | 72 | — | — | 72 | ||||||||||||||||||||||
| Total financial assets — Asset Management¹ | $ | 10,494 | $ | 13,287 | $ | — | $ | 23,781 | ||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||
| Debt securities: | ||||||||||||||||||||||||||
| U.S. government and agency | $ | 10,348 | $ | — | $ | — | $ | 10,348 | ||||||||||||||||||
| U.S. state, territories and municipalities | 3,440 | — | 1,914 | 5,354 | ||||||||||||||||||||||
| Other government and agency | — | — | 2,475 | 2,475 | ||||||||||||||||||||||
| Corporate | 166,693 | — | 104,495 | 271,188 | ||||||||||||||||||||||
| Asset and mortgage-backed securities | 221,524 | — | 121,149 | 342,673 | ||||||||||||||||||||||
| Corporate loans | — | — | 124,067 | 124,067 | ||||||||||||||||||||||
| Mortgage loans | — | 162,566 | — | 162,566 | ||||||||||||||||||||||
| Equity securities | 15,053 | — | — | 15,053 | ||||||||||||||||||||||
| Other invested assets² | 4,878 | 17,097 | 1,109 | 23,084 | ||||||||||||||||||||||
| Total financial assets — Insurance Solutions | $ | 421,936 | $ | 179,663 | $ | 355,209 | $ | 956,808 | ||||||||||||||||||
| Corporate loans of consolidated VIEs | — | — | 119,731 | 119,731 | ||||||||||||||||||||||
| Equity securities of consolidated VIEs | 949 | — | — | 949 | ||||||||||||||||||||||
| Total financial assets — Insurance Solutions, including consolidated VIEs | 422,885 | 179,663 | 474,940 | 1,077,488 | ||||||||||||||||||||||
| Total financial assets | $ | 433,379 | $ | 192,950 | $ | 474,940 | $ | 1,101,269 | ||||||||||||||||||
_______________
(1)The MLC US Holdings Credit Facility (as hereinafter defined) is collateralized by assets held by MLC US Holdings, including assets totaling $34.8 million as of December 31, 2025.
(2)Other invested assets primarily include structured securities and loan receivables.
Available-for-sale – Insurance Solutions
The following table represents the cost or amortized cost, gross unrealized gains, gross unrealized losses, and fair value of available-for-sale (“AFS”) investments by asset type:
| As of September 30, 2026 | Cost or amortized cost | Gross unrealized gains | Gross unrealized losses | Fair value1 | ||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||
| Debt securities: | ||||||||||||||||||||||||||
| U.S. government and agency | $ | 10,252 | $ | — | $ | (891) | $ | 9,361 | ||||||||||||||||||
| U.S. state, territories and municipalities | 3,181 | — | (796) | 2,385 | ||||||||||||||||||||||
| Corporate | 165,130 | 437 | (18,437) | 147,130 | ||||||||||||||||||||||
| Asset and mortgage-backed securities | 206,615 | 4,458 | (6,679) | 204,394 | ||||||||||||||||||||||
| Other invested assets | 5,457 | — | (3,005) | 2,452 | ||||||||||||||||||||||
| Total AFS — Insurance Solutions | $ | 390,635 | $ | 4,895 | $ | (29,808) | $ | 365,722 | ||||||||||||||||||
23
| As of December 31, 2025 | Cost or amortized cost | Gross unrealized gains | Gross unrealized losses | Fair value1 | ||||||||||||||||||||||
| Financial assets | ||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||
| Debt securities: | ||||||||||||||||||||||||||
| U.S. government and agency | $ | 10,623 | $ | 75 | $ | (350) | $ | 10,348 | ||||||||||||||||||
| U.S. state, territories and municipalities | 4,154 | — | (714) | 3,440 | ||||||||||||||||||||||
| Corporate | 177,997 | 1,429 | (12,733) | 166,693 | ||||||||||||||||||||||
| Asset and mortgage-backed securities | 222,766 | 3,130 | (4,372) | 221,524 | ||||||||||||||||||||||
| Other invested assets | 5,439 | 1 | (1,824) | 3,616 | ||||||||||||||||||||||
| Total AFS — Insurance Solutions | $ | 420,979 | $ | 4,635 | $ | (19,993) | $ | 405,621 | ||||||||||||||||||
_______________
(1)There is no allowance for credit losses for AFS investments as of September 30, 2026 and December 31, 2025.
The maturity distribution for AFS securities is as follows:
| As of September 30, 2026 | ||||||||||||||
| Cost or amortized cost | Fair value | |||||||||||||
| Due in one year or less | $ | 7,768 | $ | 7,793 | ||||||||||
| Due after one year through five years | 83,487 | 81,874 | ||||||||||||
| Due after five years through ten years | 131,570 | 124,520 | ||||||||||||
| Due after ten years | 167,810 | 151,535 | ||||||||||||
| Total AFS securities | $ | 390,635 | $ | 365,722 | ||||||||||
Actual maturities can differ from contractual maturities as borrowers may have the right to call or prepay obligations with or without call or prepayment penalties.
The following table provides information about AFS securities for which an allowance for credit losses has not been recorded, aggregated by asset category and length of time the securities have been continuously in an unrealized loss position:
| Less than 12 months | 12 months or more | Total | |||||||||||||||||||||||||||
| As of September 30, 2026 | Fair value | Unrealized losses | Fair value | Unrealized losses | Fair value | Unrealized losses | |||||||||||||||||||||||
| Insurance Solutions | |||||||||||||||||||||||||||||
| Debt securities: | |||||||||||||||||||||||||||||
| U.S. government and agency | $ | 4,433 | $ | (499) | $ | 4,669 | $ | (392) | $ | 9,102 | $ | (891) | |||||||||||||||||
| U.S. state, territories and municipalities | — | — | 2,385 | (796) | 2,385 | (796) | |||||||||||||||||||||||
| Corporate | 75,365 | (3,477) | 43,580 | (14,961) | 118,945 | (18,438) | |||||||||||||||||||||||
| Asset and mortgage-backed securities | 87,631 | (3,451) | 35,808 | (3,228) | 123,439 | (6,679) | |||||||||||||||||||||||
| Other invested assets | 33 | (2) | 2,387 | (3,002) | 2,420 | (3,004) | |||||||||||||||||||||||
| Total AFS securities in a continuous loss position | $ | 167,462 | $ | (7,429) | $ | 88,829 | $ | (22,379) | $ | 256,291 | $ | (29,808) | |||||||||||||||||
24
| Less than 12 months | 12 months or more | Total | |||||||||||||||||||||||||||
| As of December 31, 2025 | Fair value | Unrealized losses | Fair value | Unrealized losses | Fair value | Unrealized losses | |||||||||||||||||||||||
| Insurance Solutions | |||||||||||||||||||||||||||||
| Debt securities: | |||||||||||||||||||||||||||||
| U.S. government and agency | $ | 778 | $ | (40) | $ | 5,172 | $ | (310) | $ | 5,950 | $ | (350) | |||||||||||||||||
| U.S. state, territories and municipalities | — | — | 3,440 | (714) | 3,440 | (714) | |||||||||||||||||||||||
| Corporate | 36,752 | (370) | 48,113 | (12,362) | 84,865 | (12,732) | |||||||||||||||||||||||
| Asset and mortgage-backed securities | 23,755 | (240) | 53,666 | (4,133) | 77,421 | (4,373) | |||||||||||||||||||||||
| Other invested assets | — | — | 3,565 | (1,824) | 3,565 | (1,824) | |||||||||||||||||||||||
| Total AFS securities in a continuous loss position | $ | 61,285 | $ | (650) | $ | 113,956 | $ | (19,343) | $ | 175,241 | $ | (19,993) | |||||||||||||||||
Unrealized gains and losses can arise from changes in interest rates or other factors, including changes in credit spreads. The Company had gross unrealized losses on below investment grade AFS securities of $6.0 million and $4.0 million as of September 30, 2026 and December 31, 2025, respectively. The single largest unrealized loss on AFS securities was $1.9 million and $1.2 million as of September 30, 2026 and December 31, 2025, respectively. The Company had 273 and 313 positions in an unrealized loss position as of September 30, 2026 and December 31, 2025, respectively.
As of September 30, 2026 and December 31, 2025, AFS securities in an unrealized loss position for 12 months or more consisted of 164 and 207 debt securities, respectively. These debt securities primarily relate to Corporate and U.S. state, municipal and political subdivisions securities, which have depressed values due primarily to an increase in interest rates since the purchase of these securities. Unrealized losses were not recognized in net income on these debt securities since the Company neither intends to sell the securities nor does it believe that it is more likely than not that it will be required to sell these securities before recovery of their cost or amortized cost basis. For securities with significant declines in value, individual security level analysis was performed utilizing underlying collateral default expectations, market data, and industry analyst reports.
Mortgage and corporate loans carried at amortized cost
Mortgage and corporate loans consist of the following:
| September 30, 2026 | December 31, 2025 | |||||||||||||
| Asset Management | ||||||||||||||
| Corporate loans | $ | — | $ | 13,586 | ||||||||||
| Total corporate loans | — | 13,586 | ||||||||||||
| Allowance for credit losses | — | (299) | ||||||||||||
| Total corporate loans, net of allowance for credit losses | $ | — | $ | 13,287 | ||||||||||
| Insurance Solutions | ||||||||||||||
| Commercial real estate mortgage loans | $ | 71,936 | $ | 65,070 | ||||||||||
| Multi-family mortgage loans | 75,361 | 107,532 | ||||||||||||
| Other invested assets - corporate loans | 12,395 | 18,043 | ||||||||||||
| Total mortgage and corporate loans | $ | 159,692 | $ | 190,645 | ||||||||||
| Allowance for credit losses | (3,804) | (10,982) | ||||||||||||
| Total mortgage and other invested assets - corporate loans, net of allowance for credit losses | $ | 155,888 | $ | 179,663 | ||||||||||
The maturity distribution for commercial real estate, multi-family mortgage loans and corporate loans were as follows as of September 30, 2026:
25
| Insurance Solutions | Commercial real estate mortgage loans | Multi-family mortgage loans | Other invested assets - corporate loans | Total loans | ||||||||||||||||||||||
| Remainder of 2026 | $ | 26,655 | $ | 9,776 | $ | — | $ | 36,431 | ||||||||||||||||||
| 2027 | 40,512 | 35,795 | — | 76,307 | ||||||||||||||||||||||
| 2028 | 4,769 | 28,130 | — | 32,899 | ||||||||||||||||||||||
| 2029 | — | — | — | — | ||||||||||||||||||||||
| 2030 | — | — | — | — | ||||||||||||||||||||||
| 2031 and thereafter | — | 1,660 | 12,395 | 14,055 | ||||||||||||||||||||||
| Total | $ | 71,936 | $ | 75,361 | $ | 12,395 | $ | 159,692 | ||||||||||||||||||
Actual maturities could differ from contractual maturities, because borrowers may have the right to prepay (with or without prepayment penalties) and loans may be refinanced.
The carrying value by credit risk and loan type were as follows:
| Asset Management | ||||||||||||||||||||||||||
| Loans – carrying value by credit risk | September 30, 2026 | December 31, 2025 | ||||||||||||||||||||||||
| Level 1 | $ | 0 | — | % | $ | 13,586 | 100 | % | ||||||||||||||||||
| Level 2 | — | — | % | — | — | % | ||||||||||||||||||||
| Level 3 | — | — | % | — | — | % | ||||||||||||||||||||
| Level 4 | — | — | % | — | — | % | ||||||||||||||||||||
| Level 5 | — | — | % | — | — | % | ||||||||||||||||||||
| Total by credit risk | $ | 0 | — | % | $ | 13,586 | 100 | % | ||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||
| Loans – carrying value by loan type | September 30, 2026 | December 31, 2025 | ||||||||||||||||||||||||
| Corporate loans | $ | — | — | % | $ | 13,586 | 100 | % | ||||||||||||||||||
| Total by loan type | $ | — | — | % | $ | 13,586 | 100 | % | ||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||
| Loans – carrying value by credit risk | September 30, 2026 | December 31, 2025 | ||||||||||||||||||||||||
| Level 1 | $ | 12,395 | 7.8 | % | $ | 18,043 | 9.5 | % | ||||||||||||||||||
| Level 2 | 122,800 | 76.9 | % | 107,259 | 56.3 | % | ||||||||||||||||||||
| Level 3 | 4,246 | 2.7 | % | 8,120 | 4.3 | % | ||||||||||||||||||||
| Level 4 | — | — | % | — | — | % | ||||||||||||||||||||
| Level 5 | 20,251 | 12.7 | % | 57,223 | 30.0 | % | ||||||||||||||||||||
| Total by credit risk | $ | 159,692 | 100 | % | $ | 190,645 | 100 | % | ||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||
| Loans – carrying value by loan type | September 30, 2026 | December 31, 2025 | ||||||||||||||||||||||||
| Commercial real estate mortgage loans | $ | 71,936 | 45.0 | % | $ | 65,070 | 34.1 | % | ||||||||||||||||||
| Multi-family mortgage loans | 75,361 | 47.1 | % | 107,532 | 56.4 | % | ||||||||||||||||||||
| Other invested assets - corporate loans | 12,395 | 7.8 | % | 18,043 | 9.5 | % | ||||||||||||||||||||
| Total by loan type | $ | 159,692 | 100 | % | $ | 190,645 | 100 | % | ||||||||||||||||||
26
The following tables summarize the activity related to the allowance for credit losses for the three and nine months ended September 30, 2026 and 2025:
| Asset Management | Corporate loans | Total loans | ||||||||||||
| Balance, June 30, 2026 | $ | 295 | $ | 295 | ||||||||||
| Charge-offs | — | — | ||||||||||||
| Recoveries | — | — | ||||||||||||
| Provision for credit losses | (295) | (295) | ||||||||||||
| Balance, September 30, 2026 | $ | — | $ | — | ||||||||||
| Asset Management | Corporate loans | Total loans | ||||||||||||
| Balance, December 31, 2025 | $ | 299 | $ | 299 | ||||||||||
| Charge-offs | — | — | ||||||||||||
| Recoveries | — | — | ||||||||||||
| Provision for credit losses | (299) | (299) | ||||||||||||
| Balance, September 30, 2026 | $ | — | $ | — | ||||||||||
| Insurance Solutions | Commercial real estate mortgage loans | Multi-family mortgage loans | Corporate loans | Total loans | ||||||||||||||||||||||
| Balance, June 30, 2026 | $ | 1,046 | $ | 6,011 | $ | 793 | $ | 7,850 | ||||||||||||||||||
| Charge-offs | — | — | — | — | ||||||||||||||||||||||
| Recoveries | — | — | — | — | ||||||||||||||||||||||
| Provision for credit losses | (24) | (3,804) | (218) | (4,046) | ||||||||||||||||||||||
| Balance, September 30, 2026 | $ | 1,022 | $ | 2,207 | $ | 575 | $ | 3,804 | ||||||||||||||||||
| Insurance Solutions | Commercial real estate mortgage loans | Multi-family mortgage loans | Corporate loans | Total loans | ||||||||||||||||||||||
| Balance, December 31, 2025 | $ | 2,355 | $ | 7,681 | $ | 946 | $ | 10,982 | ||||||||||||||||||
| Charge-offs | — | — | — | — | ||||||||||||||||||||||
| Recoveries | — | — | — | — | ||||||||||||||||||||||
| Provision for credit losses | (1,333) | (5,474) | (371) | (7,178) | ||||||||||||||||||||||
| Balance, September 30, 2026 | $ | 1,022 | $ | 2,207 | $ | 575 | $ | 3,804 | ||||||||||||||||||
| Asset Management | Corporate loans | Total loans | ||||||||||||
| Balance, June 30, 2025 | $ | 299 | $ | 299 | ||||||||||
| Charge-offs | — | — | ||||||||||||
| Recoveries | — | — | ||||||||||||
| Provision for credit losses | — | — | ||||||||||||
| Balance, September 30, 2025 | $ | 299 | $ | 299 | ||||||||||
| Asset Management | Corporate loans | Total loans | ||||||||||||
| Balance, December 31, 2024 | $ | 299 | $ | 299 | ||||||||||
| Charge-offs | — | — | ||||||||||||
| Recoveries | — | — | ||||||||||||
| Provision for credit losses | — | — | ||||||||||||
| Balance, September 30, 2025 | $ | 299 | $ | 299 | ||||||||||
27
| Insurance Solutions | Commercial real estate mortgage loans | Multi-family mortgage loans | Corporate loans | Total loans | ||||||||||||||||||||||
| Balance, June 30, 2025 | $ | 2,617 | $ | 3,601 | $ | 1,012 | $ | 7,230 | ||||||||||||||||||
| Charge-offs | — | — | — | — | ||||||||||||||||||||||
| Recoveries | — | — | — | — | ||||||||||||||||||||||
| Provision for credit losses | (295) | (203) | (34) | (532) | ||||||||||||||||||||||
| Balance, September 30, 2025 | $ | 2,322 | $ | 3,398 | $ | 978 | $ | 6,698 | ||||||||||||||||||
| Insurance Solutions | Commercial real estate mortgage loans | Multi-family mortgage loans | Corporate loans | Total loans | ||||||||||||||||||||||
| Balance, December 31, 2024 | $ | 2,615 | $ | 3,360 | $ | 1,078 | $ | 7,053 | ||||||||||||||||||
| Charge-offs | — | — | — | — | ||||||||||||||||||||||
| Recoveries | — | — | — | — | ||||||||||||||||||||||
| Provision for credit losses | (293) | 38 | (100) | (355) | ||||||||||||||||||||||
| Balance, September 30, 2025 | $ | 2,322 | $ | 3,398 | $ | 978 | $ | 6,698 | ||||||||||||||||||
The following tables present an analysis of past-due loans:
| September 30, 2026 | ||||||||||||||||||||||||||||||||||||||
| Asset Management | Loans 30-59 days past due | Loans 60-89 days past due | Loans 90 days or more past due | Nonaccrual loans | Current loans | Total loans | ||||||||||||||||||||||||||||||||
| Corporate loans | $ | — | $ | — | $ | — | $ | — | $ | — | $ | — | ||||||||||||||||||||||||||
| Total corporate loans | $ | — | $ | — | $ | — | $ | — | $ | — | $ | — | ||||||||||||||||||||||||||
| September 30, 2026 | ||||||||||||||||||||||||||||||||||||||
| Insurance Solutions | Loans 30-59 days past due | Loans 60-89 days past due | Loans 90 days or more past due | Nonaccrual loans | Current loans | Total loans | ||||||||||||||||||||||||||||||||
| Commercial real estate mortgage loans | $ | — | $ | — | $ | — | $ | 4,079 | $ | 67,857 | $ | 71,936 | ||||||||||||||||||||||||||
| Multi-family mortgage loans | — | — | — | 4,566 | 70,795 | 75,361 | ||||||||||||||||||||||||||||||||
| Other invested assets - corporate loans | — | — | — | — | 12,395 | 12,395 | ||||||||||||||||||||||||||||||||
| Total mortgage and other invested assets - corporate loans | $ | — | $ | — | $ | — | $ | 8,645 | $ | 151,047 | $ | 159,692 | ||||||||||||||||||||||||||
28
| December 31, 2025 | ||||||||||||||||||||||||||||||||||||||
| Asset Management | Loans 30-59 days past due | Loans 60-89 days past due | Loans 90 days or more past due | Nonaccrual loans | Current loans | Total loans | ||||||||||||||||||||||||||||||||
| Corporate loans | $ | — | $ | — | $ | — | $ | — | $ | 13,586 | $ | 13,586 | ||||||||||||||||||||||||||
| Total corporate loans | $ | — | $ | — | $ | — | $ | — | $ | 13,586 | $ | 13,586 | ||||||||||||||||||||||||||
| December 31, 2025 | ||||||||||||||||||||||||||||||||||||||
| Insurance Solutions | Loans 30-59 days past due | Loans 60-89 days past due | Loans 90 days or more past due | Nonaccrual loans | Current loans | Total loans | ||||||||||||||||||||||||||||||||
| Commercial real estate mortgage loans | $ | — | $ | — | $ | — | $ | 20,642 | $ | 44,428 | $ | 65,070 | ||||||||||||||||||||||||||
| Multi-family mortgage loans | — | — | — | 41,063 | 66,469 | 107,532 | ||||||||||||||||||||||||||||||||
| Other invested assets - corporate loans | — | — | — | — | 18,043 | 18,043 | ||||||||||||||||||||||||||||||||
| Total mortgage and other invested assets - corporate loans | $ | — | $ | — | $ | — | $ | 61,705 | $ | 128,940 | $ | 190,645 | ||||||||||||||||||||||||||
The Company designates individually evaluated loans on nonaccrual status as collateral-dependent loans, as well as other loans that management of the Company designates as having higher risk. Collateral dependent loans are loans for which the repayment is expected to be provided substantially through the operation or sale of the collateral and the borrower is experiencing financial difficulty. These loans do not share common risk characteristics and are not included within the collectively evaluated loans for determining the allowance for credit losses.
The following represents total nonaccrual loans:
| September 30, 2026 | ||||||||||||||||||||
| Insurance Solutions | Nonaccrual loans with no allowance | Nonaccrual loans with an allowance | Total nonaccrual loans | |||||||||||||||||
| Commercial real estate mortgage loans | $ | — | $ | 4,079 | $ | 4,079 | ||||||||||||||
| Multi-family mortgage loans | — | 4,566 | 4,566 | |||||||||||||||||
| Total loans | $ | — | $ | 8,645 | $ | 8,645 | ||||||||||||||
| December 31, 2025 | ||||||||||||||||||||
| Insurance Solutions | Nonaccrual loans with no allowance | Nonaccrual loans with an allowance | Total nonaccrual loans | |||||||||||||||||
| Commercial real estate mortgage loans | $ | 3,447 | $ | 17,195 | $ | 20,642 | ||||||||||||||
| Multi-family mortgage loans | — | 41,063 | 41,063 | |||||||||||||||||
| Total loans | $ | 3,447 | $ | 58,258 | $ | 61,705 | ||||||||||||||
The following represents accrued interest receivables written off:
29
| As of | September 30, 2026 | December 31, 2025 | ||||||||||||
| Insurance Solutions | ||||||||||||||
| Commercial real estate mortgage loans | $ | — | $ | 494 | ||||||||||
| Multi-family mortgage loans | — | 1,787 | ||||||||||||
| Other invested assets - corporate loans | — | — | ||||||||||||
| Total accrued interest receivables written off | $ | — | $ | 2,281 | ||||||||||
The following table represents the portfolio of mortgage and corporate loans by origination year as of September 30, 2026 and December 31, 2025:
| Performance status as of September 30, 2026 | 2026 | 2025 | 2024 | 2023 | 2022 | Prior | Total | |||||||||||||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||||||||||||||||||||
| Corporate loans | ||||||||||||||||||||||||||||||||||||||||||||
| Level 1 | $ | — | $ | — | $ | — | $ | — | $ | — | $ | — | $ | — | ||||||||||||||||||||||||||||||
| Level 2 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Level 3 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Level 4 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Level 5 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Total corporate loans | $ | — | $ | — | $ | — | $ | — | $ | — | $ | — | $ | — | ||||||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial real estate loans | ||||||||||||||||||||||||||||||||||||||||||||
| Level 1 | $ | — | $ | — | $ | — | $ | — | $ | — | $ | — | $ | — | ||||||||||||||||||||||||||||||
| Level 2 | 3,670 | 7,354 | 9,760 | 17,488 | 19,730 | 3,460 | 61,462 | |||||||||||||||||||||||||||||||||||||
| Level 3 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Level 4 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Level 5 | — | — | — | — | 1,914 | 8,560 | 10,474 | |||||||||||||||||||||||||||||||||||||
| Total commercial real estate loans | 3,670 | 7,354 | 9,760 | 17,488 | 21,644 | 12,020 | 71,936 | |||||||||||||||||||||||||||||||||||||
| Multi-family loans | ||||||||||||||||||||||||||||||||||||||||||||
| Level 1 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Level 2 | 16,712 | 28,570 | 16,057 | — | — | — | 61,339 | |||||||||||||||||||||||||||||||||||||
| Level 3 | — | 4,246 | — | — | — | — | 4,246 | |||||||||||||||||||||||||||||||||||||
| Level 4 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Level 5 | — | — | — | 4,100 | — | 5,676 | 9,776 | |||||||||||||||||||||||||||||||||||||
| Total multi-family loans | 16,712 | 32,816 | 16,057 | 4,100 | — | 5,676 | 75,361 | |||||||||||||||||||||||||||||||||||||
| Other invested assets - corporate loans | ||||||||||||||||||||||||||||||||||||||||||||
| Level 1 | 72 | 152 | 33 | 407 | 51 | 11,680 | 12,395 | |||||||||||||||||||||||||||||||||||||
| Level 2 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Level 3 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Level 4 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Level 5 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Total other invested assets - corporate loans | 72 | 152 | 33 | 407 | 51 | 11,680 | 12,395 | |||||||||||||||||||||||||||||||||||||
| Total mortgage and corporate loans | $ | 20,454 | $ | 40,322 | $ | 25,850 | $ | 21,995 | $ | 21,695 | $ | 29,376 | $ | 159,692 | ||||||||||||||||||||||||||||||
30
| Performance status as of December 31, 2025 | 2025 | 2024 | 2023 | 2022 | 2021 | Prior | Total | |||||||||||||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||||||||||||||||||||
| Corporate loans | ||||||||||||||||||||||||||||||||||||||||||||
| Level 1 | $ | — | $ | — | $ | — | $ | — | $ | — | $ | 13,586 | $ | 13,586 | ||||||||||||||||||||||||||||||
| Level 2 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Level 3 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Level 4 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Level 5 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Total corporate loans | $ | — | $ | — | $ | — | $ | — | $ | — | $ | 13,586 | $ | 13,586 | ||||||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial real estate loans | ||||||||||||||||||||||||||||||||||||||||||||
| Level 1 | $ | — | $ | — | $ | — | $ | — | $ | — | $ | — | $ | — | ||||||||||||||||||||||||||||||
| Level 2 | 7,354 | 5,220 | 17,554 | 10,840 | 3,460 | — | 44,428 | |||||||||||||||||||||||||||||||||||||
| Level 3 | — | — | — | — | 4,482 | — | 4,482 | |||||||||||||||||||||||||||||||||||||
| Level 4 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Level 5 | — | — | — | 1,914 | 10,799 | 3,447 | 16,160 | |||||||||||||||||||||||||||||||||||||
| Total commercial real estate loans | 7,354 | 5,220 | 17,554 | 12,754 | 18,741 | 3,447 | 65,070 | |||||||||||||||||||||||||||||||||||||
| Multi-family loans | ||||||||||||||||||||||||||||||||||||||||||||
| Level 1 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Level 2 | 21,586 | 33,614 | 7,631 | — | — | — | 62,831 | |||||||||||||||||||||||||||||||||||||
| Level 3 | 3,638 | — | — | — | — | — | 3,638 | |||||||||||||||||||||||||||||||||||||
| Level 4 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Level 5 | — | — | — | 9,487 | 19,107 | 12,469 | 41,063 | |||||||||||||||||||||||||||||||||||||
| Total multi-family loans | 25,224 | 33,614 | 7,631 | 9,487 | 19,107 | 12,469 | 107,532 | |||||||||||||||||||||||||||||||||||||
| Other invested assets - corporate loans | ||||||||||||||||||||||||||||||||||||||||||||
| Level 1 | 223 | 48 | 596 | 74 | 17,102 | — | 18,043 | |||||||||||||||||||||||||||||||||||||
| Level 2 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Level 3 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Level 4 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Level 5 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Total other invested assets - corporate loans | 223 | 48 | 596 | 74 | 17,102 | — | 18,043 | |||||||||||||||||||||||||||||||||||||
| Total mortgage and corporate loans | $ | 32,801 | $ | 38,882 | $ | 25,781 | $ | 22,315 | $ | 54,950 | $ | 15,916 | $ | 190,645 | ||||||||||||||||||||||||||||||
The following represents the carrying value of collateral-dependent loans of the Company as of September 30, 2026 and December 31, 2025:
| September 30, 2026 | December 31, 2025 | |||||||||||||
| Commercial real estate mortgage loans | $ | 4,079 | $ | 14,246 | ||||||||||
| Multi-family mortgage loans | 4,566 | 36,894 | ||||||||||||
| Total Loans | $ | 8,645 | $ | 51,140 | ||||||||||
The Company maintains a separate reserve for credit losses on off-balance sheet credit exposures, including unfunded loan commitments, which is included under the line item entitled “Accrued expenses and other liabilities” on the Condensed Consolidated Statements of Financial Position. The reserve for credit losses on off-balance sheet credit exposures is adjusted as a provision for credit losses in the income statement. The estimate includes consideration of the likelihood that funding will occur and an estimate of expected credit losses on commitments expected to be funded over its estimated life, utilizing the same models and approaches for the Company's other loan portfolio segments described above, as these unfunded commitments share similar risk characteristics as its loan portfolio segments. The unfunded off-balance sheet credit line commitments for corporate loans accounted for as held for investments (“HFI”) was $nil for Asset Management and $3.8 million for Insurance Solutions as of September 30, 2026 (December 31, 2025: $1.4 million and $4.3 million, for Asset Management and Insurance Solutions, respectively).
31
The liability for credit losses on off-balance sheet credit exposures for these loans included in Accrued expenses and other liabilities was less than $0.1 million for both Asset Management and Insurance Solutions as of both September 30, 2026 and December 31, 2025. Refer to Note 24. Commitments and contingencies for additional information of the Company’s investment commitments.
32
Note 7. Derivatives
The Company uses derivative instruments to manage interest rate risk. See Note 9. Fair value measurements for information about the fair value hierarchy for derivatives.
The following table presents the notional amount and fair value of freestanding derivative instruments:
| September 30, 2026 | December 31, 2025 | |||||||||||||||||||||||||||||||||||||
| Notional amount | Assets | Liabilities | Notional amount | Assets | Liabilities | |||||||||||||||||||||||||||||||||
| Derivatives designated as hedges | ||||||||||||||||||||||||||||||||||||||
| Interest rate swaps | $ | 187,000 | $ | — | $ | 11,596 | $ | 187,000 | $ | 481 | $ | 1,388 | ||||||||||||||||||||||||||
Derivatives designated as hedges
Cash flow hedges
The Company uses interest rate swaps to convert floating-rate interest receipts on its loan portfolio to fixed-rate interest receipts to reduce exposure to interest rate changes. The interest rate swaps will expire by October 2036. During the three and nine months ended September 30, 2026 and September 30, 2025, the Company reported losses of $8.1 million and $10.7 million and gains of $0.5 million in Other Comprehensive Income (“OCI”) associated with these hedges, respectively. There were no amounts deemed ineffective during the three and nine months ended September 30, 2026 and September 30, 2025. As of September 30, 2026 and September 30, 2025, a gain of $1.5 million and a loss of less than $0.1 million is expected to be reclassified into income as part of earnings within the next 12 months, respectively.
Embedded derivatives
The Company has embedded derivatives which are required to be separated from their host contracts and reported as derivatives. Host contracts include reinsurance agreements structured on a modified coinsurance (“Modco”) or funds withheld basis. The fair value of the embedded derivative liability is $38.9 million and $29.7 million as of September 30, 2026 and December 31, 2025, respectively.
Credit risk
The Company may be exposed to credit-related losses in the event of counterparty nonperformance on derivative financial instruments. Generally, the current credit exposure of the Company’s derivative contracts is the fair value at the reporting date less any collateral received from the counterparty.
The Company manages credit risk related to derivatives by entering into transactions with creditworthy counterparties. Where possible, the Company maintains collateral arrangements and uses master netting agreements that provide for a single net payment from one counterparty to another at each due date and upon termination. The Company has also established counterparty exposure limits, where possible, in order to evaluate if there is sufficient collateral to support the net exposure. Collateral arrangements typically require the posting of collateral in connection with its derivative instruments. Collateral agreements often contain posting thresholds, some of which may vary depending on the posting party’s financial strength ratings.
There is no difference between the current presentation of the fair value of the interest rate swaps and the presentation of fair value of the interest rate swaps after the application of any right of offset, as of September 30, 2026.
Note 8. Variable interest entities
Consolidated variable interest entities (“VIEs”) include collateralized loan obligations (“CLOs”) managed by the Company. The assets of consolidated VIEs are not available to creditors of the Company, and the investors in these consolidated VIEs have no recourse against the assets of the Company.
33
Revenues of consolidated VIEs - Insurance Solutions
The following summarizes the Condensed Consolidated Statements of Operations activity of the consolidated VIEs:
| For the three months ended September 30, | 2026 | 2025 | ||||||||||||
| Investment income | $ | 3,689 | $ | 4,276 | ||||||||||
| Investment expense | (252) | (147) | ||||||||||||
| Net investment income | 3,437 | 4,129 | ||||||||||||
| Unrealized gain/(loss) on investments | 1,837 | (1,405) | ||||||||||||
| Realized gain/(loss) on investments | (3,573) | 73 | ||||||||||||
| Net realized and change in unrealized gains (losses) from investment activities | (1,736) | (1,332) | ||||||||||||
| Net revenues of consolidated variable interest entities | $ | 1,701 | $ | 2,797 | ||||||||||
| For the nine months ended September 30, | 2026 | 2025 | ||||||||||||
| Investment income | $ | 11,054 | $ | 12,385 | ||||||||||
| Investment expense | (866) | (522) | ||||||||||||
| Net investment income | 10,188 | 11,863 | ||||||||||||
| Unrealized gain/(loss) on investments | (2,403) | (2,194) | ||||||||||||
| Realized gain/(loss) on investments | (4,220) | 310 | ||||||||||||
| Net realized and change in unrealized gains (losses) from investment activities | (6,623) | (1,884) | ||||||||||||
| Net revenues of consolidated variable interest entities | $ | 3,565 | $ | 9,979 | ||||||||||
Unconsolidated VIEs
The Company holds variable interests in certain VIEs for which it is not the primary beneficiary. The Company’s variable interests include equity interests, loans, and beneficial interests in CLOs and other entities, which are recorded within “Investments” in the Condensed Consolidated Statements of Financial Position. The following table presents the Company’s maximum exposure to losses relating to these VIEs for which the Company has a variable interest, but is not the primary beneficiary. The Company has exposure beyond the carrying value of its variable interests due to unfunded commitments on loans.
| September 30, 2026 | December 31, 2025 | |||||||||||||||||||||||||
| Carrying amount | Maximum exposure to loss | Carrying amount | Maximum Exposure to Loss | |||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||
| Variable interests in related parties | $ | 10,018 | $ | 10,018 | $ | 28,209 | $ | 29,622 | ||||||||||||||||||
| Total Asset Management | $ | 10,018 | $ | 10,018 | $ | 28,209 | $ | 29,622 | ||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||
| Variable interests | $ | 11,821 | $ | 11,821 | $ | 17,097 | $ | 17,097 | ||||||||||||||||||
| Variable interests in related parties | 11,881 | 11,881 | 15,355 | 15,355 | ||||||||||||||||||||||
| Total Insurance Solutions | $ | 23,702 | $ | 23,702 | $ | 32,452 | $ | 32,452 | ||||||||||||||||||
| Total | $ | 33,720 | $ | 33,720 | $ | 60,661 | $ | 62,074 | ||||||||||||||||||
Note 9. Fair value measurements
The following tables summarize the valuation of assets and liabilities measured at fair value by fair value hierarchy. Investments classified as Equity Method for which the Fair Value Option (“FVO”) has not been elected have been excluded from the table below.
34
| Fair Value Measurements | ||||||||||||||||||||||||||||||||
| September 30, 2026 | Level 1 | Level 2 | Level 3 | NAV | Total | |||||||||||||||||||||||||||
| Financial assets | ||||||||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||||||||
| Equity securities | $ | 615 | $ | — | $ | 6,085 | $ | — | $ | 6,700 | ||||||||||||||||||||||
| Derivatives | — | — | — | — | — | |||||||||||||||||||||||||||
| Other invested assets | — | — | 68 | — | 68 | |||||||||||||||||||||||||||
| Total financial assets — Asset Management | 615 | — | 6,153 | — | 6,768 | |||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||
| Debt securities: | ||||||||||||||||||||||||||||||||
| U.S. government and agency | — | 9,362 | — | — | 9,362 | |||||||||||||||||||||||||||
| U.S. state, territories and municipalities | — | 4,161 | — | — | 4,161 | |||||||||||||||||||||||||||
| Other government and agency | — | 2,366 | — | — | 2,366 | |||||||||||||||||||||||||||
| Corporate | — | 233,844 | 7,110 | — | 240,954 | |||||||||||||||||||||||||||
| Asset and mortgage-backed securities | — | 282,690 | 37,012 | — | 319,702 | |||||||||||||||||||||||||||
| Corporate loans | — | 17,732 | 93,301 | — | 111,033 | |||||||||||||||||||||||||||
| Equity securities | 129 | 2,195 | 317 | 1,760 | 4,401 | |||||||||||||||||||||||||||
| Other invested assets | — | 10,014 | 4,480 | 277 | 14,771 | |||||||||||||||||||||||||||
| Total financial assets — Insurance Solutions | 129 | 562,364 | 142,220 | 2,037 | 706,750 | |||||||||||||||||||||||||||
| Corporate loans of consolidated VIEs | — | — | 127,630 | — | 127,630 | |||||||||||||||||||||||||||
| Equity of consolidated VIEs | — | — | 1,051 | — | 1,051 | |||||||||||||||||||||||||||
| Total financial assets including consolidated VIEs | 129 | 562,364 | 270,901 | 2,037 | 835,431 | |||||||||||||||||||||||||||
| Derivatives | — | — | — | — | — | |||||||||||||||||||||||||||
| Total financial assets | $ | 744 | $ | 562,364 | $ | 277,054 | $ | 2,037 | $ | 842,199 | ||||||||||||||||||||||
| Financial liabilities | ||||||||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||
| Ceded reinsurance - embedded derivative | — | 38,894 | — | — | 38,894 | |||||||||||||||||||||||||||
| Interest rate swaps | — | 11,596 | — | — | 11,596 | |||||||||||||||||||||||||||
| Total financial liabilities — Insurance Solutions | — | 50,490 | — | — | 50,490 | |||||||||||||||||||||||||||
| Total financial liabilities | $ | — | $ | 50,490 | $ | — | $ | — | $ | 50,490 | ||||||||||||||||||||||
35
| Fair Value Measurements | ||||||||||||||||||||||||||||||||
| December 31, 2025 | Level 1 | Level 2 | Level 3 | NAV | Total | |||||||||||||||||||||||||||
| Financial assets | ||||||||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||||||||
| Equity securities | $ | 3,834 | $ | 91 | $ | 6,484 | $ | — | $ | 10,409 | ||||||||||||||||||||||
| Derivatives | — | — | 13 | — | 13 | |||||||||||||||||||||||||||
| Other invested assets | — | — | 72 | — | 72 | |||||||||||||||||||||||||||
| Total financial assets — Asset Management | 3,834 | 91 | 6,569 | — | 10,494 | |||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||
| Debt securities: | ||||||||||||||||||||||||||||||||
| U.S. government and agency | — | 10,348 | — | — | 10,348 | |||||||||||||||||||||||||||
| U.S. state, territories and municipalities | — | 5,354 | — | — | 5,354 | |||||||||||||||||||||||||||
| Other government and agency | — | 2,475 | — | — | 2,475 | |||||||||||||||||||||||||||
| Corporate | — | 261,039 | 10,149 | — | 271,188 | |||||||||||||||||||||||||||
| Asset and mortgage-backed securities | — | 323,246 | 19,427 | — | 342,673 | |||||||||||||||||||||||||||
| Corporate loans | — | 7,499 | 116,568 | — | 124,067 | |||||||||||||||||||||||||||
| Equity securities | 7,644 | 2,246 | 3,240 | 1,923 | 15,053 | |||||||||||||||||||||||||||
| Other invested assets | — | 51 | 5,637 | 299 | 5,987 | |||||||||||||||||||||||||||
| Total financial assets — Insurance Solutions | 7,644 | 612,258 | 155,021 | 2,222 | 777,145 | |||||||||||||||||||||||||||
| Corporate loans of consolidated VIEs | — | — | 119,731 | — | 119,731 | |||||||||||||||||||||||||||
| Equity securities of consolidated VIEs | — | — | 949 | — | 949 | |||||||||||||||||||||||||||
| Total financial assets including consolidated VIEs | 7,644 | 612,258 | 275,701 | 2,222 | 897,825 | |||||||||||||||||||||||||||
| Derivatives | — | 481 | — | — | 481 | |||||||||||||||||||||||||||
| Total financial assets | $ | 11,478 | $ | 612,830 | $ | 282,270 | $ | 2,222 | $ | 908,800 | ||||||||||||||||||||||
| Financial liabilities | ||||||||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||
| Ceded reinsurance - embedded derivative | — | 29,650 | — | — | 29,650 | |||||||||||||||||||||||||||
| Interest rate swaps | — | 1,388 | — | — | 1,388 | |||||||||||||||||||||||||||
| Total financial liabilities — Insurance Solutions | — | 31,038 | — | — | 31,038 | |||||||||||||||||||||||||||
| Total financial liabilities | $ | — | $ | 31,038 | $ | — | $ | — | $ | 31,038 | ||||||||||||||||||||||
The availability of observable inputs can vary depending on the financial asset and is affected by a wide variety of factors, including, for example, the type of instrument, whether the instrument has recently been issued, whether the instrument is traded on an active exchange or in the secondary market, and current market conditions. To the extent that valuation is based on models or inputs that are less observable or unobservable in the market, the determination of fair value requires additional judgment. Accordingly, the degree of judgment exercised by the Company in determining fair value is greatest for instruments categorized as Level 3. The variability and availability of the observable inputs affected by the factors described above may cause transfers between Levels 1, 2, and 3, as discussed further below.
Transfers between level 1 and level 2
The Company records transfers of assets between Level 1 and Level 2 at their fair values at the end of each reporting period. Assets are transferred out of Level 1 when they are no longer transacted with sufficient frequency and volume in an active market. Conversely, assets are transferred from Level 2 to Level 1 when transaction volume and frequency are indicative of an active market. During the three and nine months ended September 30, 2026 and September 30, 2025, there were no assets transferred between Level 1 and Level 2.
Transfers between level 1 or 2 and level 3
The Company records transfers of assets between Level 1 or 2 and Level 3 at the end of each reporting period. Assets are transferred into Level 3 when there is a lack of observable valuation inputs.
Conversely, assets are transferred out of Level 3 when valuation inputs become observable. Whether the assets are transferred into Level 1 or 2 will depend on whether the prices are unadjusted and quoted in an active market.
36
The following tables summarize changes in the Company’s investment portfolio measured and reporting at fair value for which Level 3 inputs were used in determining fair value:
| Net Change in Unrealized Appreciation (Depreciation) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Change in unrealized gains (losses) included in income on Level 3 assets and liabilities still held | Change in unrealized gains (losses) included in OCI on Level 3 assets and liabilities still held | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Purchases | Sales and repayments | Net realized gain (loss) | Included in income | Included in OCI | Transfer in ¹ | Transfer out ¹ | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Three months ended September 30, 2026 | Beginning Balance | Ending Balance | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Financial assets | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Equity securities | $ | 6,237 | $ | — | $ | — | $ | — | $ | (152) | $ | — | $ | — | $ | — | $ | 6,085 | $ | (152) | $ | — | ||||||||||||||||||||||||||||||||||||||||||||||
| Other invested assets | 71 | — | — | — | (3) | — | — | — | 68 | (3) | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets — Asset Management | 6,308 | — | — | — | (155) | — | — | — | 6,153 | (155) | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Debt securities: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Corporate | 10,001 | — | — | — | — | (91) | — | (2,800) | 7,110 | — | (91) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Asset and mortgage-backed securities | 40,373 | 2,577 | (2,394) | (559) | 323 | (982) | — | (2,326) | 37,012 | (31) | (982) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Corporate loans | 108,536 | 746 | (1,315) | 14 | (290) | — | — | (14,390) | 93,301 | (299) | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Equity securities | 301 | — | (22) | — | 38 | — | — | — | 317 | 38 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other invested assets | 4,749 | 21 | — | — | 56 | (346) | — | — | 4,480 | 55 | (346) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets — Insurance Solutions | 163,960 | 3,344 | (3,731) | (545) | 127 | (1,419) | — | (19,516) | 142,220 | (237) | (1,419) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Corporate loans of consolidated VIEs | 129,606 | 11,887 | (12,423) | (3,573) | 2,133 | — | — | — | 127,630 | 1,901 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Equity securities of consolidated VIEs | 1,116 | — | — | — | (65) | — | — | — | 1,051 | (65) | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total financial assets including consolidated VIEs - Insurance Solutions | 294,682 | 15,231 | (16,154) | (4,118) | 2,195 | (1,419) | — | (19,516) | 270,901 | 1,599 | (1,419) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total financial assets | $ | 300,990 | $ | 15,231 | $ | (16,154) | $ | (4,118) | $ | 2,040 | $ | (1,419) | $ | — | $ | (19,516) | $ | 277,054 | $ | 1,444 | $ | (1,419) | ||||||||||||||||||||||||||||||||||||||||||||||
37
| Net Change in Unrealized Appreciation (Depreciation) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Change in unrealized gains (losses) included in income on Level 3 assets and liabilities still held | Change in unrealized gains (losses) included in OCI on Level 3 assets and liabilities still held | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Purchases | Sales and repayments | Net realized gain (loss) | Included in income | Included in OCI | Transfer in ¹ | Transfer out ¹ | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Nine months ended September 30, 2026 | Beginning Balance | Ending Balance | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Financial assets | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Equity securities | $ | 6,484 | $ | — | $ | — | $ | — | $ | (399) | $ | — | $ | — | $ | — | $ | 6,085 | $ | (399) | $ | — | ||||||||||||||||||||||||||||||||||||||||||||||
| Derivatives | 13 | — | (14) | 3 | (2) | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other invested assets | 72 | — | — | — | (4) | — | — | — | 68 | (4) | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets — Asset Management | 6,569 | — | (14) | 3 | (405) | — | — | — | 6,153 | (403) | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Debt securities: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Corporate | 10,149 | — | — | — | — | (239) | 5,000 | (7,800) | 7,110 | — | (239) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Asset and mortgage-backed securities | 19,427 | 2,596 | (5,432) | (544) | 414 | 2,605 | 20,272 | (2,326) | 37,012 | (31) | 2,605 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Corporate loans | 116,568 | 2,189 | (17,856) | 14 | (724) | — | 7,500 | (14,390) | 93,301 | (777) | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Equity securities | 3,240 | — | (3,023) | — | 100 | — | — | — | 317 | 100 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other invested assets | 5,637 | 64 | (5) | — | (88) | (1,180) | 52 | — | 4,480 | (90) | (1,180) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets — Insurance Solutions | 155,021 | 4,849 | (26,316) | (530) | (298) | 1,186 | 32,824 | (24,516) | 142,220 | (798) | 1,186 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Corporate loans of consolidated VIEs | 119,731 | 62,936 | (49,530) | (4,220) | (1,287) | — | — | — | 127,630 | (2,832) | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Equity securities of consolidated VIEs | 949 | 530 | — | — | (428) | — | — | — | 1,051 | 428 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total financial assets including consolidated VIEs - Insurance Solutions | 275,701 | 68,315 | (75,846) | (4,750) | (2,013) | 1,186 | 32,824 | (24,516) | 270,901 | (3,202) | 1,186 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total financial assets | $ | 282,270 | $ | 68,315 | $ | (75,860) | $ | (4,747) | $ | (2,418) | $ | 1,186 | $ | 32,824 | $ | (24,516) | $ | 277,054 | $ | (3,605) | $ | 1,186 | ||||||||||||||||||||||||||||||||||||||||||||||
_______________
(1)Transfers into Level 3 are due to decrease in the quantity and reliability of broker quotes obtained. Transfers out of Level 3 are due to an increase in the quantity and reliability of broker quotes obtained. Transfers are assumed to have occurred at the end of the period.
38
| Net Change in Unrealized Appreciation (Depreciation) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Change in unrealized gains (losses) included in income on Level 3 assets and liabilities still held | Change in unrealized gains (losses) included in OCI on Level 3 assets and liabilities still held | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Purchases | Sales and repayments | Net realized gain (loss) | Included in income | Included in OCI | Transfer in ¹ | Transfer out ¹ | Change in consolidation | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Three months ended September 30, 2025 | Beginning Balance | Ending Balance | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Financial assets | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Equity securities | $ | 5,849 | $ | 945 | $ | (1,322) | $ | — | $ | 469 | $ | — | $ | — | $ | — | $ | — | $ | 5,941 | $ | 468 | $ | — | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Derivatives | — | 11 | — | — | 2 | — | — | — | — | 13 | 2 | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other Invested Assets | — | 73 | — | — | — | — | — | — | — | 73 | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets — Asset Management | 5,849 | 1,029 | (1,322) | — | 471 | — | — | — | — | 6,027 | 470 | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Debt securities: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Corporate | 5,067 | — | — | — | — | 41 | — | — | — | 5,108 | — | 41 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Asset and mortgage-backed securities | 15,113 | — | (232) | — | (7) | 335 | 3,623 | — | — | 18,832 | — | 335 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Corporate loans | 134,741 | 633 | (29,686) | — | 142 | — | 27,095 | — | — | 132,925 | 139 | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Equity securities | 3,000 | — | — | — | (19) | — | 366 | — | — | 3,347 | (19) | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other invested assets | 3,163 | — | — | — | 860 | 311 | 90 | — | — | 4,424 | 859 | 311 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets — Insurance Solutions | 161,084 | 633 | (29,918) | — | 976 | 687 | 31,174 | — | — | 164,636 | 979 | 687 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Corporate loans of consolidated VIEs | 128,805 | 31,297 | (30,037) | 73 | (972) | — | — | — | — | 129,166 | (1,333) | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Equity securities of consolidated VIEs | 247 | 824 | (104) | — | (72) | — | — | — | — | 895 | (72) | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total financial assets including consolidated VIEs - Insurance Solutions | 290,136 | 32,754 | (60,059) | 73 | (68) | 687 | 31,174 | — | — | 294,697 | (426) | 687 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total financial assets | $ | 295,985 | $ | 33,783 | $ | (61,381) | $ | 73 | $ | 403 | $ | 687 | $ | 31,174 | $ | — | $ | — | $ | 300,724 | $ | 44 | $ | 687 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Financial liabilities | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Debt obligations | 132 | — | — | — | — | — | — | — | — | 132 | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities — Asset Management | 132 | — | — | — | — | — | — | — | — | 132 | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total financial liabilities — Asset Management | $ | 132 | $ | — | $ | — | $ | — | $ | — | $ | — | $ | — | $ | — | $ | — | $ | 132 | $ | — | $ | — | ||||||||||||||||||||||||||||||||||||||||||||||||||
39
| Net Change in Unrealized Appreciation (Depreciation) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Change in unrealized gains (losses) included in income on Level 3 assets and liabilities still held | Change in unrealized gains (losses) included in OCI on Level 3 assets and liabilities still held | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Purchases | Sales and repayments | Net realized gain (loss) | Included in income | Included in OCI | Transfer in ¹ | Transfer out ¹ | Change in consolidation | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Nine months ended September 30, 2025 | Beginning Balance | Ending Balance | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Financial assets | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Equity securities | $ | 499 | $ | 5,945 | $ | (1,341) | $ | — | $ | 838 | $ | — | $ | — | $ | — | $ | — | $ | 5,941 | $ | 866 | $ | — | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Derivatives | — | 11 | — | — | 2 | — | — | — | — | 13 | 2 | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other Invested Assets | — | 73 | — | — | — | — | — | — | — | 73 | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets — Asset Management | 499 | 6,029 | (1,341) | — | 840 | — | — | — | — | 6,027 | 868 | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Debt securities: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Corporate | — | — | — | — | — | 108 | 5,000 | — | — | — | 5,108 | — | 108 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Asset and mortgage-backed securities | 8,641 | — | (761) | — | (8) | 485 | 10,475 | — | — | 18,832 | — | 485 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Corporate loans | 114,734 | 17,775 | (34,260) | — | 1,581 | — | 33,095 | — | — | 132,925 | 1,568 | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Equity securities | 2,918 | — | — | — | 64 | — | 365 | — | — | 3,347 | 64 | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other invested assets | 4,575 | — | (4,432) | (745) | 5,121 | (185) | 90 | — | — | 4,424 | 943 | (185) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets — Insurance Solutions | 130,868 | 17,775 | (39,453) | (745) | 6,758 | 408 | 49,025 | — | — | 164,636 | 2,575 | 408 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Corporate loans of consolidated VIEs | 125,757 | 65,248 | (60,971) | 310 | (1,178) | — | — | — | — | 129,166 | (2,228) | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Equity securities of consolidated VIEs | 141 | 824 | (104) | — | 34 | — | — | — | — | 895 | 34 | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total financial assets including consolidated VIEs - Insurance Solutions | 256,766 | 83,847 | (100,528) | (435) | 5,614 | 408 | 49,025 | — | — | 294,697 | 381 | 408 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total financial assets | $ | 257,265 | $ | 89,876 | $ | (101,869) | $ | (435) | $ | 6,454 | $ | 408 | $ | 49,025 | $ | — | $ | — | $ | 300,724 | $ | 1,249 | $ | 408 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Financial liabilities | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Debt obligations | $ | 1,471 | $ | — | $ | — | $ | — | $ | (1,339) | $ | — | $ | — | $ | — | $ | — | $ | 132 | $ | 1,339 | $ | — | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total financial liabilities — Asset Management | $ | 1,471 | $ | — | $ | — | $ | — | $ | (1,339) | $ | — | $ | — | $ | — | $ | — | $ | 132 | $ | 1,339 | $ | — | ||||||||||||||||||||||||||||||||||||||||||||||||||
_______________
(1)Transfers into Level 3 are due to a decrease in the quantity and reliability of broker quotes obtained. Transfers out of Level 3 are due to an increase in the quantity and reliability of broker quotes obtained. Transfers are assumed to have occurred at the end of the period.
40
The valuation techniques and significant unobservable inputs used in Level 3 valuations were as follows:
| Quantitative Information about Level 3 Fair Value Measurements | ||||||||||||||||||||||||||
| September 30, 2026 | Fair value | Valuation technique/ methodology | Unobservable input | Range (weighted average) | ||||||||||||||||||||||
| Financial assets | ||||||||||||||||||||||||||
| Asset management | ||||||||||||||||||||||||||
| Equity securities | $ | 6,010 | Equity value | Multiple | 8.5x - 10.5x (9.5x) | |||||||||||||||||||||
| Equity securities | 75 | Market approach | Privately quoted price | NA | ||||||||||||||||||||||
| Other invested assets | 68 | Probability-Weighted Expected Return Method | Independent probabilities | 5.0% - 5.0% (5.0%) | ||||||||||||||||||||||
| Probability-Weighted Expected Return Method | Dependent probabilities | 2.4% - 3.7% (3.1%) | ||||||||||||||||||||||||
| Probability-Weighted Expected Return Method | Years to exit | 2.5 - 4.5 (3.5) | ||||||||||||||||||||||||
| Total — Asset Management | $ | 6,153 | ||||||||||||||||||||||||
| Insurance | ||||||||||||||||||||||||||
| Debt securities¹: | ||||||||||||||||||||||||||
| Asset and mortgage-backed securities | $ | 37,012 | Discounted cash flow | Discount rate | 7.2% - 9.7% (9.4%) | |||||||||||||||||||||
| Corporate | 7,110 | Discounted cash flow | Discount rate | 6.5% - 8.7% (8.0%) | ||||||||||||||||||||||
| Corporate loans | 93,301 | Discounted cash flow | Discount rate | —% - 15.9% (8.5%) | ||||||||||||||||||||||
| Equity securities | 8 | Recent transaction | Transaction price | NA | ||||||||||||||||||||||
| Equity securities | 309 | Enterprise value | Multiple | 0.1x - 0.1x (0.1x) | ||||||||||||||||||||||
| Other invested assets | 4,480 | Discounted cash flow | Discount rate | —% - 18.7% (10.0%) | ||||||||||||||||||||||
| Total — Insurance Solutions | $ | 142,220 | ||||||||||||||||||||||||
| Equity securities of consolidated VIEs | $ | 1,051 | Enterprise value | Multiple | 10.6x - 10.6x (10.6x) | |||||||||||||||||||||
| Corporate loans of consolidated VIEs | 18,926 | Recent transaction | Transaction price | NA | ||||||||||||||||||||||
| Corporate loans of consolidated VIEs | 108,704 | Discounted cash flow | Discount rate | 5.0% - 14.8% (10.5%) | ||||||||||||||||||||||
| Total assets of consolidated VIEs - Insurance Solutions | $ | 128,681 | ||||||||||||||||||||||||
| Total financial assets including consolidated VIEs - Insurance Solutions | $ | 270,901 | ||||||||||||||||||||||||
| Total financial assets | $ | 277,054 | ||||||||||||||||||||||||
_______________
(1)For debt securities where the recent transaction price does not estimate fair value, the Company determines the fair value utilizing a yield analysis.
41
42
| Quantitative Information about Level 3 Fair Value Measurements | ||||||||||||||||||||||||||
| December 31, 2025 | Fair value | Valuation technique/ methodology | Unobservable input | Range (weighted average) | ||||||||||||||||||||||
| Financial assets | ||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||
| Equity securities | $ | 6,409 | Enterprise value | Multiple | 12.5x - 13.5x (13.0x) | |||||||||||||||||||||
| Equity securities | 75 | Market approach | Privately quoted price | NA | ||||||||||||||||||||||
| Equity securities | 13 | Option pricing model | Volatility | 116.2% - 126.2% (121.2%) | ||||||||||||||||||||||
| Option pricing model | Years to exercise | 0.1 - 0.3 (0.2) | ||||||||||||||||||||||||
| Other invested assets | 72 | Probability-Weighted Expected Return Method | Independent probabilities | 5.0% - 5.0% (5.0%) | ||||||||||||||||||||||
| Probability-Weighted Expected Return Method | Dependent probabilities | 2.4% - 3.7% (3.1%) | ||||||||||||||||||||||||
| Probability-Weighted Expected Return Method | Years to cash flows | 2.5 - 4.5 (3.5) | ||||||||||||||||||||||||
| Total — Asset Management | $ | 6,569 | ||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||
Debt securities¹: | ||||||||||||||||||||||||||
| Asset and mortgage-backed securities | 19,427 | Discounted cash flow | Discount rate | 6.3% - 8.5% (7.6%) | ||||||||||||||||||||||
| Corporate | 10,149 | Discounted cash flow | Discount rate | 7.4% - 8.9% (8.1%) | ||||||||||||||||||||||
| Corporate loans | 116,568 | Discounted cash flow | Discount rate | —% - 15.7% (8.2%) | ||||||||||||||||||||||
| Equity securities | 30 | Recent transaction | Transaction price | NA | ||||||||||||||||||||||
| Equity securities | 210 | Enterprise value | Multiple | 0.6x - 0.6x (0.6x) | ||||||||||||||||||||||
| Equity securities | 3,000 | Discounted cash flow | Discount rate | 5.6% - 5.6% (5.6%) | ||||||||||||||||||||||
| Other invested assets | 5,637 | Discounted cash flow | Discount rate | 9.6% - 19.7% (16.9%) | ||||||||||||||||||||||
| Total — Insurance Solutions | 155,021 | |||||||||||||||||||||||||
| Equity securities of consolidated VIEs | 949 | Enterprise value | Multiple | 10.0x - 16.0x (13.0x) | ||||||||||||||||||||||
| Corporate loans of consolidated VIEs | 30,123 | Recent transaction | Transaction price | NA | ||||||||||||||||||||||
| Corporate loans of consolidated VIEs | 89,608 | Discounted cash flow | Discount rate | 5.3% - 14.8% ( 9.6%) | ||||||||||||||||||||||
| Total assets of consolidated VIEs - Insurance Solutions | $ | 120,680 | ||||||||||||||||||||||||
| Total financial assets including consolidated VIEs - Insurance Solutions | 275,701 | |||||||||||||||||||||||||
| Total financial assets | $ | 282,270 | ||||||||||||||||||||||||
_______________
(1)For debt securities where the recent transaction price does not estimate fair value, the Company determines the fair value utilizing a yield analysis.
The Company typically determines the fair value of its performing Level 3 debt investments utilizing a yield analysis. In a yield analysis, a price is ascribed for each investment based upon an assessment of current and expected market yields for similar investments and risk profiles. Additional consideration is given to the expected life, portfolio company performance since close, and other terms and risks associated with an investment. Among other factors, a determinant of risk is the amount of leverage used by the portfolio company relative to the total enterprise value of the company, and the rights and remedies of the Company’s investment within each portfolio company’s capital structure.
Significant unobservable inputs include an illiquidity spread as well as a credit spread, both of which increase the discount rate. These rates are initially set at a level such that the loan valuation equals the initial purchase cost of the loan and are subsequently adjusted at each valuation date to reflect management’s current assessment of market conditions as well as of loan-specific credit and illiquidity risk. Discount rates are subject to adjustment based on both management’s current assessment of market conditions and the economic performance of individual investments. The significant unobservable inputs used in the fair value measurement of the Company’s Level 3 debt securities primarily include current market yields, including relevant market indices, but may also include quotes from brokers, dealers, and pricing services as indicated by comparable investments.
43
Financial instruments not carried at fair value
The following tables present carrying amounts and fair values of the Company’s financial assets and liabilities which are not carried at fair value as of September 30, 2026 and December 31, 2025:
| Fair Value Hierarchy | ||||||||||||||||||||||||||||||||
| September 30, 2026 | Carrying value | Fair value | Level 1 | Level 2 | Level 3 | |||||||||||||||||||||||||||
| Financial Assets | ||||||||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||||||||
| Corporate loans | $ | — | $ | — | $ | — | $ | — | $ | — | ||||||||||||||||||||||
| Total financial assets — Asset Management | — | — | — | — | — | |||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||
| Mortgage loans | 144,069 | 147,298 | — | — | 147,298 | |||||||||||||||||||||||||||
| Other invested assets | 11,819 | 11,805 | — | — | 11,805 | |||||||||||||||||||||||||||
| Total financial assets — Insurance Solutions | 155,888 | 159,103 | — | — | 159,103 | |||||||||||||||||||||||||||
| Total financial assets | $ | 155,888 | $ | 159,103 | $ | — | $ | — | $ | 159,103 | ||||||||||||||||||||||
| Financial Liabilities | ||||||||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||||||||
| Debt obligations | $ | 98,392 | $ | 89,814 | $ | 36,320 | $ | — | $ | 53,494 | ||||||||||||||||||||||
| Total financial liabilities — Asset Management | 98,392 | 89,814 | 36,320 | — | 53,494 | |||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||
| Debt obligations | 12,000 | 11,820 | — | — | 11,820 | |||||||||||||||||||||||||||
| Interest sensitive contract liabilities | 281,283 | 281,283 | — | 281,283 | — | |||||||||||||||||||||||||||
| Total financial liabilities —Insurance Solutions | 293,283 | 293,103 | — | 281,283 | 11,820 | |||||||||||||||||||||||||||
| Total financial liabilities | $ | 391,675 | $ | 382,917 | $ | 36,320 | $ | 281,283 | $ | 65,314 | ||||||||||||||||||||||
| December 31, 2025 | Carrying value | Fair value | Level 1 | Level 2 | Level 3 | |||||||||||||||||||||||||||
| Financial Assets | ||||||||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||||||||
| Corporate loans | $ | 13,287 | $ | 11,151 | $ | — | $ | — | $ | 11,151 | ||||||||||||||||||||||
| Total financial assets — Asset Management | 13,287 | 11,151 | — | — | 11,151 | |||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||
| Mortgage loans | 162,566 | 172,602 | — | — | 172,602 | |||||||||||||||||||||||||||
| Other invested assets | 17,097 | 17,488 | — | — | 17,488 | |||||||||||||||||||||||||||
| Total financial assets — Insurance Solutions | 179,663 | 190,090 | — | — | 190,090 | |||||||||||||||||||||||||||
| Total financial assets | $ | 192,950 | $ | 201,241 | $ | — | $ | — | $ | 201,241 | ||||||||||||||||||||||
| Financial Liabilities | ||||||||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||||||||
| Debt obligations | $ | 76,250 | $ | 72,880 | $ | — | $ | — | $ | 72,880 | ||||||||||||||||||||||
| Total financial liabilities — Asset Management | 76,250 | 72,880 | — | — | 72,880 | |||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||
| Debt obligations | 17,250 | 17,447 | — | — | 17,447 | |||||||||||||||||||||||||||
| Interest sensitive contract liabilities | 363,981 | 363,981 | — | 363,981 | — | |||||||||||||||||||||||||||
| Total financial liabilities —Insurance Solutions | 381,231 | 381,428 | — | 363,981 | 17,447 | |||||||||||||||||||||||||||
| Total financial liabilities | $ | 457,481 | $ | 454,308 | $ | — | $ | 363,981 | $ | 90,327 | ||||||||||||||||||||||
44
Fair value option
The following table presents the net realized and unrealized gains (losses) on financial instruments for which the FVO was elected:
| For the three months ended September 30, | 2026 | 2025 | ||||||||||||||||||||||||||||||||||||
| Net realized gains (losses) | Net unrealized gains (losses) | Total | Net realized gains (losses) | Net unrealized gains (losses) | Total | |||||||||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||||||||||||||
| Debt obligation | $ | — | $ | — | $ | — | $ | — | $ | — | $ | — | ||||||||||||||||||||||||||
| Net realized and change in unrealized gains (losses) from investment activities — Asset Management | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||||||||
| Debt securities: | ||||||||||||||||||||||||||||||||||||||
| U.S. state, territories and municipalities | — | (107) | (107) | — | 13 | 13 | ||||||||||||||||||||||||||||||||
| Other government and agency | — | (139) | (139) | — | 208 | 208 | ||||||||||||||||||||||||||||||||
| Corporate | — | (7,415) | (7,415) | (706) | 3,645 | 2,939 | ||||||||||||||||||||||||||||||||
| Asset and mortgage- backed securities | 43 | 214 | 257 | (23) | 478 | 455 | ||||||||||||||||||||||||||||||||
| Corporate loans | 14 | (252) | (238) | — | (96) | (96) | ||||||||||||||||||||||||||||||||
| Other invested assets | — | (113) | (113) | — | — | — | ||||||||||||||||||||||||||||||||
| Net realized and change in unrealized gains (losses) from investment activities — Insurance Solutions | 57 | (7,812) | (7,755) | (729) | 4,248 | 3,519 | ||||||||||||||||||||||||||||||||
| Investments of consolidated VIEs | (3,573) | 1,836 | (1,737) | 73 | (1,405) | (1,332) | ||||||||||||||||||||||||||||||||
| Net realized and change in unrealized gains (losses) from investment activities — Insurance Solutions including consolidated VIEs | $ | (3,516) | $ | (5,976) | $ | (9,492) | $ | (656) | $ | 2,843 | $ | 2,187 | ||||||||||||||||||||||||||
45
| For the nine months ended September 30, | 2026 | 2025 | ||||||||||||||||||||||||||||||||||||
| Net realized gains (losses) | Net unrealized gains (losses) | Total | Net realized gains (losses) | Net unrealized gains (losses) | Total | |||||||||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||||||||||||||
| Debt obligation | $ | — | $ | — | $ | — | $ | — | $ | 1,339 | $ | 1,339 | ||||||||||||||||||||||||||
| Net realized and change in unrealized gains (losses) from investment activities — Asset Management | — | — | — | — | 1,339 | 1,339 | ||||||||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||||||||
| Debt securities: | ||||||||||||||||||||||||||||||||||||||
| U.S. state, territories and municipalities | — | (124) | (124) | — | 75 | 75 | ||||||||||||||||||||||||||||||||
| Other government and agency | — | (102) | (102) | — | 205 | 205 | ||||||||||||||||||||||||||||||||
| Corporate | (4) | (7,803) | (7,807) | (1,815) | 5,881 | 4,066 | ||||||||||||||||||||||||||||||||
| Asset and mortgage- backed securities | 27 | (924) | (897) | (317) | 294 | (23) | ||||||||||||||||||||||||||||||||
| Corporate loans | 19 | (1,250) | (1,231) | — | 1,330 | 1,330 | ||||||||||||||||||||||||||||||||
| Other invested assets | — | (79) | (79) | (755) | 4,217 | 3,462 | ||||||||||||||||||||||||||||||||
| Net realized and change in unrealized gains (losses) from investment activities — Insurance Solutions | 42 | (10,282) | (10,240) | (2,887) | 12,002 | 9,115 | ||||||||||||||||||||||||||||||||
| Investments of consolidated VIEs | (4,220) | (2,404) | (6,624) | 310 | (2,194) | (1,884) | ||||||||||||||||||||||||||||||||
| Net realized and change in unrealized gains (losses) from investment activities — Insurance Solutions including consolidated VIEs | $ | (4,178) | $ | (12,686) | $ | (16,864) | $ | (2,577) | $ | 9,808 | $ | 7,231 | ||||||||||||||||||||||||||
The following table presents information for loans which the Company elected the FVO.
| September 30, 2026 | Unpaid Principal Balance | Mark to Fair Value | Fair Value | |||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||
| Corporate loans | $ | 115,846 | $ | (4,813) | $ | 111,033 | ||||||||||||||
| Other invested assets | 1,289 | (257) | 1,032 | |||||||||||||||||
| Insurance Solutions | 117,135 | (5,070) | 112,065 | |||||||||||||||||
| Corporate loans of consolidated VIEs | 139,490 | (11,860) | 127,630 | |||||||||||||||||
| Insurance Solutions including consolidated VIEs | $ | 256,625 | $ | (16,930) | $ | 239,695 | ||||||||||||||
| December 31, 2025 | Unpaid Principal Balance | Mark to Fair Value | Fair Value | |||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||
| Corporate loans | $ | 125,422 | $ | (1,355) | $ | 124,067 | ||||||||||||||
| Other invested assets | 1,289 | (179) | 1,110 | |||||||||||||||||
| Insurance Solutions | 126,711 | (1,534) | 125,177 | |||||||||||||||||
| Corporate loans of consolidated VIEs | 127,620 | (7,889) | 119,731 | |||||||||||||||||
| Insurance Solutions including consolidated VIEs | $ | 254,331 | $ | (9,423) | $ | 244,908 | ||||||||||||||
46
As of September 30, 2026 and December 31, 2025, there were no loans accounted for at fair value under the FVO which were 90 days or more past-due or in non-accrual status.
The following table presents the estimated amount of gains (losses) included in earnings attributable to changes in instrument-specific credit risk on corporate loans for which the Company elected the FVO.
| For the nine months ended September 30, | 2026 | 2025 | ||||||||||||
| Insurance Solutions | ||||||||||||||
| Corporate loans | $ | (1,124) | $ | 1,123 | ||||||||||
| Other invested assets | — | 3,471 | ||||||||||||
| Insurance Solutions | (1,124) | 4,594 | ||||||||||||
| Corporate loans of consolidated VIEs | 1,975 | (915) | ||||||||||||
| Insurance Solutions including consolidated VIEs | $ | 851 | $ | 3,679 | ||||||||||
The portion of gains and losses attributable to changes in instrument-specific credit risk is estimated by identifying loans with changes in credit ratings meeting certain criteria.
Note 10. Revenue from service contracts
The following table summarizes the Company’s revenue from service contracts for Asset Management:
| Three months ended September 30, | Nine months ended September 30, | ||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | ||||||||||||||||||||
| Management fees | $ | 1,874 | $ | 1,851 | $ | 5,204 | $ | 7,900 | |||||||||||||||
| Incentive fees | — | 431 | 813 | 1,208 | |||||||||||||||||||
| Advisory and transaction fees | — | — | 66 | — | |||||||||||||||||||
Servicing fees (expense)¹ | (795) | (409) | (2,273) | (1,451) | |||||||||||||||||||
_______________
(1)Servicing fees were a net expense for the Company as reimbursements to Sierra Crest Investment Management (“SCIM”) for certain costs and the specified investment advisory fee retained by SCIM exceeded the net economic benefit derived under the Alternative Credit Income Fund (“ACIF”) advisory agreement, for the three and nine months ended September 30, 2026 and September 30, 2025. Servicing fees are included within Administration and servicing fees in the Condensed Consolidated Statements of Operations.
Note 11. Goodwill and intangible assets
Goodwill
The carrying amount of goodwill by reportable segment was $1.0 million for Asset Management as of both September 30, 2026 and December 31, 2025, which is included within “Other assets” in the Condensed Consolidated Statements of Financial Position. The carrying amount of goodwill was $30.2 million for Insurance Solutions as of both September 30, 2026 and December 31, 2025.
The table below presents the changes in the carrying amount of goodwill by reporting unit in Insurance Solutions as of September 30, 2026 and December 31, 2025.
| Reporting Unit | ||||||||||||||||||||
| MYGA | LTC | Total | ||||||||||||||||||
| Goodwill, gross as of December 31, 2025 | $ | 30,193 | $ | 25,504 | $ | 55,697 | ||||||||||||||
Accumulated impairment losses¹ | — | (25,504) | (25,504) | |||||||||||||||||
| Goodwill, net as of September 30, 2026 | 30,193 | — | 30,193 | |||||||||||||||||
| Goodwill, gross as of December 31, 2024 | $ | 30,193 | $ | 25,504 | $ | 55,697 | ||||||||||||||
| Impairment losses | — | (25,504) | (25,504) | |||||||||||||||||
| Goodwill, net as of December 31, 2025 | $ | 30,193 | $ | — | $ | 30,193 | ||||||||||||||
47
_______________
(1)Accumulated impairment losses include the $25.5 million impairment loss recognized in relation to the LTC reporting unit during the year ended December 31, 2025 and there was no impairment loss recognized during the nine months ended September 30, 2026
Intangible assets
During the three months ended September 30, 2026, the Company recognized an intangible asset of $2.8 million and $12.2 million in connection with the TSA and the Revenue Share Amount, respectively, as described in Note 3. Business combinations and Asset Acquisitions. The Rebate mechanism associated to the TSA will result in cumulative catch-up amortization adjustments to the cost basis of this indefinite-lived asset in future periods as each $0.25 million tranche becomes probable and estimable.
Intangible assets consist of the following as of September 30, 2026 and December 31, 2025:
| September 30, 2026 | ||||||||||||||||||||||||||
| Gross carrying amount | Accumulated amortization | Accumulated impairment | Net carrying amount | |||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||
| Intangible assets — indefinite life | ||||||||||||||||||||||||||
| Investment management contracts | $ | 2,835 | $ | — | $ | — | $ | 2,835 | ||||||||||||||||||
| Profit sharing interest | $ | 8,191 | $ | — | $ | — | $ | 8,191 | ||||||||||||||||||
| Revenue sharing interest | 12,194 | — | — | 12,194 | ||||||||||||||||||||||
| Intangible assets — definite life | ||||||||||||||||||||||||||
| Investment management contracts | 11,148 | (10,008) | — | 1,140 | ||||||||||||||||||||||
| Total intangible assets — Asset Management | $ | 34,368 | $ | (10,008) | $ | — | $ | 24,360 | ||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||
| Intangible assets — indefinite life | ||||||||||||||||||||||||||
| State insurance licenses | 2,444 | — | — | 2,444 | ||||||||||||||||||||||
| Total intangible assets — Insurance Solutions | $ | 2,444 | $ | — | $ | — | $ | 2,444 | ||||||||||||||||||
| December 31, 2025 | ||||||||||||||||||||||||||
| Gross carrying amount | Accumulated amortization | Accumulated impairment | Net carrying amount | |||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||
| Intangible assets — indefinite life | ||||||||||||||||||||||||||
| Investment management contracts | $ | 19,204 | $ | — | $ | (19,204) | $ | — | ||||||||||||||||||
Profit sharing interest1 | 11,236 | — | (3,045) | 8,191 | ||||||||||||||||||||||
| Intangible assets — definite life | ||||||||||||||||||||||||||
| Investment management contracts | 11,544 | (8,381) | (393) | 2,770 | ||||||||||||||||||||||
| Total intangible assets — Asset Management | $ | 41,984 | $ | (8,381) | $ | (22,642) | $ | 10,961 | ||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||
| Intangible assets — indefinite life | ||||||||||||||||||||||||||
| State insurance licenses | 2,444 | — | — | 2,444 | ||||||||||||||||||||||
| Total intangible assets — Insurance Solutions | $ | 2,444 | $ | — | $ | — | $ | 2,444 | ||||||||||||||||||
_______________
(1)On July 15, 2025, the merging of Logan Ridge Finance Corporation (“Logan Ridge”) into Portman Ridge Finance Corporation (“Portman Ridge” or “Portman”) closed, with the new combined entity renamed to BCIC. Upon the close of this merger, the Company’s investment management agreement with Logan Ridge was terminated, resulting in an impairment loss for the full carrying amount of the investment management agreement. Upon termination of the investment management agreement with Logan Ridge, the Company acquired a profit-sharing agreement with the owner of SCIM, which is the manager of BCIC, for no cash consideration. The acquisition of the profit-sharing agreement is presented as a gain that offsets the accumulated impairment loss on the Logan Ridge investment management agreement, in “Amortization and impairment of intangible assets” on
48
the consolidated statements of operations for the year ended December 31, 2025. The profit-sharing agreement was determined to be an indefinite-lived intangible asset given the Company expects SCIM to be the investment manager of BCIC indefinitely, and for the owner of SCIM to hold its equity in SCIM indefinitely.
The following table represents estimated intangible amortization expense as of September 30, 2026:
| As of | September 30, 2026 | |||||||
| Remainder of 2026 | $ | 284 | ||||||
| 2027 | 791 | |||||||
| 2028 | 52 | |||||||
| 2029 | 13 | |||||||
| 2030 | — | |||||||
| 2031 and thereafter | — | |||||||
| Total | $ | 1,140 | ||||||
Note 12. Debt obligations
Asset Management
MLC US Holdings Credit Facility
The MLC US Holdings Credit Facility matures on August 20, 2027 and is secured by assets held by MLC US Holdings and guaranteed by the Company. On January 27, 2026, the Company repaid $22.5 million of the outstanding balance using proceeds from the Exchange Listed Notes described below, resulting in a partial extinguishment and a $0.5 million write-off of unamortized transaction costs, recognized within "loss on extinguishment of debt" in the Condensed Consolidated Statements of Operations for the nine months ended September 30, 2026. On April 7, 2026, the Company entered into a Guaranty assuming Legacy Mount Logan's obligations as guarantor under the facility. The Company was in compliance with all debt covenants as of September 30, 2026.
Seller notes
On October 29, 2021, the Company completed the Ability Acquisition through in part the issuance of an unsecured promissory note of $15.0 million, which bears interest at 5.0% per annum and is payable by October 29, 2031.
Unsecured debentures
The Company's unsecured debentures bear interest at 8.85% PIK with Initial Debenture Units carrying attached common share purchase warrants exercisable at C$11.61 per share, as adjusted for the Business Combination. On April 17, 2026, a subsidiary of the Company issued a further 5,597 Additional Initial Debentures for aggregate proceeds of $5.6 million, used to repay $2.3 million and $3.0 million in principal (plus accrued interest) of Ability surplus notes held by Sentinel Security Life Insurance Company and Atlantic Coast Life Insurance Company, respectively. These Additional Initial Debentures mature January 26, 2032 and carry no attached warrants.
Exchange listed notes
On January 26, 2026, the Company issued $40 million in aggregate principal amount of senior unsecured notes (“Exchange Listed Notes”) that bear interest at 8.0% per year and will mature on January 31, 2031. Transaction costs of $2.3 million were capitalized and will be accreted through the interest expense over the life of the debt. Net proceeds were used to repay $22.5 million of outstanding indebtedness under the MLC US Holdings Credit Facility, with remaining proceeds for general corporate purposes.
49
Debt obligations consisted of the following as of September 30, 2026 and December 31, 2025:
| As of September 30, 2026 | Maturity date | Stated interest rate | Effective interest rate | Extension options | Total facility | Outstanding balance | ||||||||||||||||||||||||||||||||
MLC US Holdings Credit Facility1 | August 2027 | SOFR +6.00% | 9.70 | % | N/A | $ | 13,500 | $ | 13,500 | |||||||||||||||||||||||||||||
| Seller note — Ability Acquisition | October 2031 | 5.00 | % | 5.00 | % | N/A | 15,000 | 15,000 | ||||||||||||||||||||||||||||||
| Exchange Listed Notes | January 2031 | 8.00 | % | 9.45 | % | N/A | 40,000 | 38,523 | ||||||||||||||||||||||||||||||
Debenture units2 | January 2032 | 8.85 | % | 8.93% - 9.28% | N/A | 26,849 | 31,548 | |||||||||||||||||||||||||||||||
| Total debt | $ | 95,349 | $ | 98,571 | ||||||||||||||||||||||||||||||||||
_______________
(1)The MLC US Holdings Credit Facility is secured by all assets and interests in assets and proceeds owned and acquired by MLC US Holdings.
(2)The warrants issued with the Initial Debenture Units are recorded in equity at fair value upon issuance and therefore are not required to be subsequently remeasured at fair value on an ongoing basis.
| As of December 31, 2025 | Maturity date | Stated interest rate | Effective interest rate | Extension options | Total facility | Outstanding balance | ||||||||||||||||||||||||||||||||
MLC US Holdings Credit Facility1 | August 2027 | SOFR +7.50% | 11.76 | % | N/A | 40,000 | 38,000 | |||||||||||||||||||||||||||||||
| Seller note — Ability Acquisition | October 2031 | 5.00 | % | 5.00 | % | N/A | 15,000 | 15,000 | ||||||||||||||||||||||||||||||
Debenture units2 | January 2032 | 8.85 | % | 8.91 | % | N/A | 21,252 | 24,075 | ||||||||||||||||||||||||||||||
| Total debt | $ | 76,252 | $ | 77,075 | ||||||||||||||||||||||||||||||||||
_______________
(1)The MLC US Holdings Credit Facility is secured by all assets and interests in assets and proceeds owned and acquired by MLC US Holdings.
(2)The warrants issued with the Initial Debenture Units are recorded in equity at fair value upon issuance and therefore are not required to be subsequently remeasured at fair value on an ongoing basis.
The scheduled principal repayments are as follows:
| As of | September 30, 2026 | ||||
| Remainder of 2026 | 3,500 | ||||
| 2027 | 16,000 | ||||
| 2028 | 3,000 | ||||
| 2029 | 3,000 | ||||
| 2030 | 3,000 | ||||
| 2031 and thereafter | 70,071 | ||||
| 98,571 | |||||
| Transaction costs (net of amortization) | (179) | ||||
| Total debt | $ | 98,392 | |||
For the three months ended September 30, 2026, interest expense, including the amortization of debt issuance costs and PIK interest, was $2.2 million (September 30, 2025 –$2.0 million). For the nine months ended September 30, 2026, interest expense, including the amortization of debt issuance costs and PIK interest, was $6.4 million (September 30, 2025 – $5.9 million).
Insurance Solutions
Debt obligations
Ability has the following surplus notes outstanding as of September 30, 2026 and December 31, 2025:
| As of September 30, 2026 | Date issued | Date of maturity | Interest rate | Par value | Carrying value of note | |||||||||||||||||||||||||||
| Revol One Insurance Company (formerly known as Pavonia Life Insurance Company of Michigan) | August, 2023 | December, 2032 | 10.00 | % | 12,000 | 12,000 | ||||||||||||||||||||||||||
| Total surplus notes | $ | 12,000 | $ | 12,000 | ||||||||||||||||||||||||||||
50
| As of December 31, 2025 | Date issued | Date of maturity | Interest rate | Par value | Carrying value of note | |||||||||||||||||||||||||||
| Sentinel Security Life Insurance Company | February, 2013 | June, 2028 | 5.00 | % | $ | 2,250 | $ | 2,250 | ||||||||||||||||||||||||
| Revol One Insurance Company (formerly known as Pavonia Life Insurance Company of Michigan) | August, 2023 | December, 2032 | 10.00 | % | 12,000 | 12,000 | ||||||||||||||||||||||||||
| Atlantic Coast Life Insurance Company | March, 2025 | March, 2033 | SOFR+6.00% | 3,000 | 3,000 | |||||||||||||||||||||||||||
| Total surplus notes | $ | 17,250 | $ | 17,250 | ||||||||||||||||||||||||||||
For the three and nine months ended September 30, 2026 and September 30, 2025, interest paid was $0.3 million and $1.2 million and $0.3 million and $1.0 million, respectively.
Refer to Note 9. Fair value measurements for fair value of financial liabilities carried at amortized cost.
The surplus notes are subordinated in right of payment of all indebtedness, policy claims, and other creditor claims, and payments of interest or principal require prior authorization by the Director of the Nebraska Department of Insurance. On April 17, 2026, the Company repaid $5.3 million of surplus notes, including $2.3 million owed to SSL and $3.0 million owed to Atlantic Coast Life Insurance Company (“ACL”).
Note 13. Deferred acquisition costs
The following table presents the rollforward of deferred acquisition costs (“DAC”) as of September 30, 2026 and September 30, 2025:
| For the Nine Months Ended September 30, 2026 | ||||||||||||||||||||||||||
| Beginning Balance | Capitalization | Amortization1 | Ending Balance | |||||||||||||||||||||||
| DAC: | ||||||||||||||||||||||||||
| MYGA | $ | 6,791 | $ | 170 | $ | (2,842) | $ | 4,119 | ||||||||||||||||||
| For the Nine Months Ended September 30, 2025 | ||||||||||||||||||||||||||
| Beginning Balance | Capitalization | Amortization | Ending Balance | |||||||||||||||||||||||
| DAC: | ||||||||||||||||||||||||||
| MYGA | $ | 6,524 | $ | 3,393 | $ | (2,389) | $ | 7,528 | ||||||||||||||||||
(1)Amortization for the nine months ended September 30, 2026 included $0.7 million associated with the 50% recapture of the SSL MYGA block liabilities. See Note 15. Interest sensitive contract liabilities for further details.
Significant methodologies and assumptions
The Company amortizes DAC related to long-duration contracts on a straight-line basis, at the individual contract level over the expected term of the related contract.
The amortization expense for DAC is included in the Amortization of deferred acquisition costs in the Condensed Consolidated Statements of Operations. The estimated future amortization expense related to DAC for the future years is as follows:
| As of | September 30, 2026 | |||||||
| Remainder of 2026 | $ | 420 | ||||||
| 2027 | 1,993 | |||||||
| 2028 | 1,176 | |||||||
| 2029 | 346 | |||||||
| 2030 | 119 | |||||||
| 2031 and thereafter | 65 | |||||||
| Total | $ | 4,119 | ||||||
51
Note 14. Future policy benefits and related reinsurance recoverable
Future policy benefits comprise substantially all obligations to insureds in the Company’s insurance operations. A summary of future policy benefits and reinsurance recoverable are presented below.
| As of | September 30, 2026 | December 31, 2025 | ||||||||||||
| Reinsurance recoverable | ||||||||||||||
| Long term care reinsurance | $ | 409,373 | $ | 452,254 | ||||||||||
| Other | 2,191 | 4,466 | ||||||||||||
Modco investments with Nichol International Reinsurance (S.A.C), Ltd¹ | (174,689) | (183,802) | ||||||||||||
| Total reinsurance recoverable | $ | 236,875 | $ | 272,918 | ||||||||||
| Future policy benefits | ||||||||||||||
| Long term care insurance | $ | 696,717 | $ | 777,412 | ||||||||||
| Other | 2,192 | 4,469 | ||||||||||||
| Total future policy benefits | $ | 698,909 | $ | 781,881 | ||||||||||
| Funds held under reinsurance contracts | ||||||||||||||
Funds held arrangement with Front Street Re¹ | $ | 222,028 | $ | 237,143 | ||||||||||
_______________
(1)The Company has a coinsurance or Modco with funds withheld arrangement with its two reinsurers. The Modco agreement with Nichol International Reinsurance (S.A.C), Ltd. (formerly known as Vista Life and Casualty Reinsurance Company) dictates that the assets held as collateral are held with the legal right of offset to the related insurance contract liabilities. Therefore, the collateral held for this agreement is netted against the reserves under this contract. The agreement with Front Street Re does not have the legal right of offset therefore the reserves are not presented net of the collateral held, instead they are in the line item “Funds held under reinsurance contracts” in the Condensed Consolidated Statements of Financial Position.
52
The following tables summarize balances of and changes in future policy benefits reserves:
| Nine months ended September 30, | ||||||||||||||
| Long-term care | 2026 | 2025 | ||||||||||||
| Present value of expected net premiums | ||||||||||||||
| Beginning Balance | $ | 273,395 | $ | 306,206 | ||||||||||
| Beginning balance at locked-in discount rate | 297,709 | 343,705 | ||||||||||||
| Effect of actual variances from expected experience | (6,156) | (8,307) | ||||||||||||
| Adjusted balance | 291,553 | 335,398 | ||||||||||||
| Interest accrual | 5,312 | 5,381 | ||||||||||||
| Net premiums collected | (31,713) | (33,807) | ||||||||||||
| Ending balance at locked-in discount rate | 265,152 | 306,972 | ||||||||||||
| Effect of changes in discount rate assumptions | (34,261) | (24,903) | ||||||||||||
| Ending Balance | $ | 230,891 | $ | 282,069 | ||||||||||
| Present value of Expected Future Policy Benefits | ||||||||||||||
| Beginning Balance | $ | 1,050,807 | $ | 1,071,361 | ||||||||||
| Beginning balance at locked-in discount rate | 1,239,275 | 1,306,356 | ||||||||||||
| Change in effect in cashflow assumptions | (4,236) | — | ||||||||||||
| Effect of actual variances from expected experience | (1,937) | 5,655 | ||||||||||||
| Adjusted balance | 1,233,102 | 1,312,011 | ||||||||||||
| Interest accrual | 22,848 | 21,280 | ||||||||||||
| Benefit payments | (81,039) | (82,212) | ||||||||||||
| Ending balance at locked-in discount rate | 1,174,911 | 1,251,079 | ||||||||||||
| Effect of changes in discount rate assumptions | (247,303) | (186,565) | ||||||||||||
| Ending Balance | $ | 927,608 | $ | 1,064,514 | ||||||||||
Net future policy benefit reserves ¹ | $ | 696,717 | $ | 782,445 | ||||||||||
Less: Reinsurance recoverables, net of allowance for credit losses ² | (409,373) | (454,732) | ||||||||||||
| Net future policy benefit reserves, after reinsurance recoverables | $ | 287,344 | $ | 327,713 | ||||||||||
_______________
(1)Net future policy benefit reserves excludes $2.2 million and $4.4 million as of September 30, 2026 and September 30, 2025, respectively, of Medico assumed reserves which are 100% ceded.
(2)Reinsurance recoverables, net of allowance for credit losses excludes $2.2 million and $4.4 million of reinsurance recoverable as of September 30, 2026 and September 30, 2025, respectively.
In the first nine months of 2026, the underlying cash flow assumptions remained unchanged for the Medico block. For the Guardian block, claim‑handling costs were separated from maintenance costs and the claim reserve assumption was also updated. These assumption updates resulted in a total of $4.2 million decrease on a gross basis in the liability for future policy benefits for the nine months ended September 30, 2026. The effect of actual variances from expected experience for the nine months ended September 30, 2026 observed a $4.2 million increase on a gross basis in the liability for future policy benefits, mainly driven by lower than expected premium receipts and higher claims.
In the first nine months of 2025, the underlying cash flow assumptions remained unchanged. The effect of actual variances from expected experience for the nine months ended September 30, 2025 observed a $14.0 million increase on a gross basis in the liability for future policy benefits, mainly driven by lower than expected premium receipts and higher claims.
53
The following tables provides the amount of undiscounted and discounted expected future gross premiums and expected future benefits and expenses for the LTC line of business:
| As of | September 30, 2026 | September 30, 2025 | ||||||||||||||||||||||||
| Long-term care | Undiscounted | Discounted¹ | Undiscounted | Discounted¹ | ||||||||||||||||||||||
| Expected future gross premiums | $ | 322,688 | $ | 230,891 | $ | 371,635 | $ | 282,069 | ||||||||||||||||||
| Benefit payments | $ | 1,656,891 | $ | 927,608 | $ | 1,765,145 | $ | 1,064,514 | ||||||||||||||||||
_______________
(1)Discount was determined using the current discount rate as of September 30, 2026 and September 30, 2025.
The following table provides the weighted-average durations of and weighted-average interest rates for the liability for future policy benefits:
| As of | September 30, 2026 | September 30, 2025 | ||||||||||||
| Weighted-average duration of liability (years) at current rate | 8.90 | 9.94 | ||||||||||||
| Weighted-average duration of liability (years) at original rate | 11.07 | 11.51 | ||||||||||||
| Weighted-average interest rate at current rate | 5.94 | % | 4.90 | % | ||||||||||
| Weighted-average interest rate at original rate | 3.13 | % | 3.07 | % | ||||||||||
Note 15. Interest sensitive contract liabilities
The following table shows the outstanding Interest sensitive contract liabilities which represents the policyholder balances for MYGA product line:
| Nine months ended September 30, | ||||||||||||||
| 2026 | 2025 | |||||||||||||
| Balance, beginning of year | $ | 363,981 | $ | 334,876 | ||||||||||
| Deposits | 911 | 42,996 | ||||||||||||
| Product charges | (429) | (1,766) | ||||||||||||
| Surrenders and withdrawals | (19,335) | (17,892) | ||||||||||||
| Benefit payments | (6,325) | (6,933) | ||||||||||||
| Interest credited | 12,639 | 11,969 | ||||||||||||
Other ¹ | (70,159) | — | ||||||||||||
| Balance, end of period | $ | 281,283 | $ | 363,250 | ||||||||||
| Weighted-average annual crediting rate | 5.00% | 5.00% | ||||||||||||
| At period end: | ||||||||||||||
| Cash surrender value | $ | 260,928 | $ | 334,969 | ||||||||||
| Net amount at risk: | ||||||||||||||
In the event of death 2 | $ | 281,283 | $ | 363,250 | ||||||||||
_______________
(1)Other represents decrease in interest sensitive contract liabilities resulting from SSL’s recapture of 50% of the quota share on the Recaptured Business, effective September 1, 2026. Refer to “Reinsurance Recapture” for further detail.
(2)For benefits that are payable in the event of death, the net amount at risk is defined as the current death benefit which is equal to the current account balances at the Condensed Consolidated Statements of Financial Position date. It represents the amount of the claim that the Company would incur if death claims were filed on all contracts at the Condensed Consolidated Statements of Financial Position date.
Reinsurance Recapture
Effective September 1, 2026, Sentinel Security Life Insurance Company (“SSL”) recaptured 50% of the quota share liability previously reinsured by Ability Insurance Company (“Ability”) on contracts issued and approved from July 1, 2022 through June 30, 2024 (the “Recaptured Business”). The remaining 50% of the quota share on those contracts ceded under the Reinsurance Agreement between SSL and Ability, remains in force on its existing terms.
54
Statutory reserves attributable to the Recaptured Business were $141.4 million as of August 31, 2026, of which $70.7 million related to the recaptured 50%. Ability transferred assets from the trust account maintained under the Reinsurance Agreement to SSL with an aggregate fair value of $68.3 million including $6.6 million in cash . This amount represents the recaptured statutory reserves, net of a recapture fee of $2.4 million retained by the Company. The recapture fee was settled by netting against the assets transferred and was not paid separately in cash.
The Company derecognized the related reinsurance liabilities included in interest sensitive contract liabilities of $70.2 million. Because the interest sensitive contract liabilities were $0.6 million lower than the corresponding statutory reserves, the derecognition resulted in a loss of $0.6 million. Together with the $2.4 million recapture fee earned, Ability recognized a net gain of $1.8 million, included in other income within insurance segment revenue for the three months ended September 30, 2026.
MYGA policyholder account balances totaled $281.3 million and $363.3 million, as of September 30, 2026, and September 30, 2025, respectively. The decrease in policyholder account balance for the nine months ended September 30, 2026 was primarily attributable to the decrease in reserves due to the SSL recapture of $70.2 million and surrenders, withdrawals, benefits and product charges of $26.1 million which was partially offset by interest credited of $12.6 million. For the nine months ended September 30, 2025 the increase in policyholder account balances was primarily attributable to $43.0 million of deposits due to the assumption of the NSG MYGA block and $12.0 million interest credited. This increase was partially offset by surrenders, withdrawals, benefits and product charges of $26.6 million for the nine months ended September 30, 2025. Interest on policyholder account balances is generally credited at minimum guaranteed rates, primarily between 2% and 7% at both September 30, 2026 and September 30, 2025.
Note 16. Reinsurance
The Company enters into reinsurance agreements primarily as a purchaser of reinsurance for its LTC line of business and also as a provider of reinsurance for the LTC and MYGA lines of business. The Company participates in reinsurance activities in order to limit losses, minimize exposure to significant risks and provide additional capacity for future growth.
Under the terms of the reinsurance agreements, the reinsurer agrees to reimburse the Company for the ceded amount in the event a claim is paid. Cessions under reinsurance agreements do not discharge the Company’s obligation as the primary insurer. In the event that reinsurers do not meet their obligations under the terms of the reinsurance agreements, Reinsurance recoverable balances could become uncollectible.
Accounting for reinsurance requires extensive use of assumptions and estimates, particularly related to the future performance of the underlying business and the potential impact of counterparty credit risks.
Reinsurance recoverable
The Company reinsures its business through three reinsurers. The Company monitors ratings and evaluates the financial strength of its reinsurers by analyzing their financial statements. In addition, the reinsurance recoverable balance due from each reinsurer is evaluated as part of the overall monitoring process. Recoverability of reinsurance recoverable balances is evaluated based on these analyses. The Company uses collateral for its reinsurance recoverable with funds withheld accounts. These reinsurance recoverable balances are stated net of allowance for expected credit loss of $0.8 million as of September 30, 2026 and $1.1 million as of December 31, 2025. The Company had $411.6 million and $456.7 million of net ceded reinsurance recoverable as of September 30, 2026 and December 31, 2025, respectively. The Company had $28.5 million and $41.3 million of unsecured Reinsurance recoverable balances as of September 30, 2026 and December 31, 2025, respectively.
55
The amounts in the Condensed Consolidated Statements of Financial Position include the impact of reinsurance. Information regarding the significant effects of reinsurance was as follows at:
| Long-term care | September 30, 2026 | December 31, 2025 | ||||||||||||
| Reinsurance recoverable | ||||||||||||||
| Medico Insurance Company | $ | 2,191 | $ | 4,466 | ||||||||||
| Front Street Re | 248,291 | 273,981 | ||||||||||||
| Nichol International Reinsurance (S.A.C), Ltd | 161,082 | 178,273 | ||||||||||||
| Nichol Modco Funds Withheld | (174,689) | (183,802) | ||||||||||||
| Total reinsurance recoverable | $ | 236,875 | $ | 272,918 | ||||||||||
| Future policy benefits | ||||||||||||||
| Direct | $ | 604,408 | $ | 673,636 | ||||||||||
| Reinsurance assumed | 94,501 | 108,245 | ||||||||||||
| Total future policy benefits | $ | 698,909 | $ | 781,881 | ||||||||||
The amounts in the Condensed Consolidated Statements of Operations include the impact of reinsurance. Information regarding the significant effects of reinsurance was as follows:
| Long-term care | ||||||||||||||
| Three months ended September 30, | 2026 | 2025 | ||||||||||||
| Net premiums | ||||||||||||||
| Direct premiums | $ | 9,299 | $ | 10,427 | ||||||||||
| Reinsurance assumed | 905 | 908 | ||||||||||||
| Reinsurance ceded | (14,593) | (15,827) | ||||||||||||
| Total net premiums | $ | (4,389) | $ | (4,492) | ||||||||||
Net policy benefit and claims (remeasurement gain on policy liabilities of $3,907 and $3,846, for the three months ended September 30, 2026 and 2025, respectively) | ||||||||||||||
| Direct | $ | 13,088 | $ | 14,557 | ||||||||||
| Reinsurance assumed | 1,940 | 1,979 | ||||||||||||
| Reinsurance ceded, net of provision for credit losses ¹ | (17,421) | (18,654) | ||||||||||||
| Total net policyholder benefits and claims | $ | (2,393) | $ | (2,118) | ||||||||||
| Long-term care | ||||||||||||||
| Nine months ended September 30, | 2026 | 2025 | ||||||||||||
| Net premiums | ||||||||||||||
| Direct premiums | $ | 28,343 | $ | 31,536 | ||||||||||
| Reinsurance assumed | 2,826 | 2,986 | ||||||||||||
| Reinsurance ceded | (44,276) | (47,265) | ||||||||||||
| Total net premiums | $ | (13,107) | $ | (12,743) | ||||||||||
Net policy benefit and claims (remeasurement gain on policy liabilities of $14,430 and $6,871, for the nine months ended September 30, 2026 and 2025, respectively) | ||||||||||||||
| Direct | $ | 39,145 | $ | 50,202 | ||||||||||
| Reinsurance assumed | 3,566 | 9,656 | ||||||||||||
Reinsurance ceded, net of provision for credit losses ¹ | (52,020) | (61,247) | ||||||||||||
| Total net policyholder benefits and claims | $ | (9,309) | $ | (1,389) | ||||||||||
_______________
(1)The provision for credit losses for reinsurance recoverables for the three and nine months ended September 30, 2026 was $(0.3) million. It was $(0.1) million and less than $0.1 million for the three and nine months ended September 30, 2025, respectively.
56
Note 17. Other assets and Accrued expenses and other liabilities
Other assets consist of the following:
| As of | September 30, 2026 | December 31, 2025 | ||||||||||||
| Asset Management | ||||||||||||||
| Management fee receivable - related parties | $ | 1,017 | $ | 1,477 | ||||||||||
| Management fee receivable | 717 | — | ||||||||||||
| Incentive fee receivable - related parties | — | 405 | ||||||||||||
| Prepaid income taxes | 769 | 693 | ||||||||||||
| Accrued interest and dividends receivable - related parties | — | 2,996 | ||||||||||||
Purchase receivables 2 | 4,333 | 2,311 | ||||||||||||
| Ovation goodwill | 1,000 | 1,000 | ||||||||||||
| Operating lease right of use asset | — | 405 | ||||||||||||
| Deferred offering costs | — | 265 | ||||||||||||
| Prepaid insurance | 635 | 553 | ||||||||||||
| Other - related parties | 835 | 367 | ||||||||||||
| Other | 662 | 693 | ||||||||||||
| Total other assets — Asset Management | 9,968 | 11,165 | ||||||||||||
| Insurance Solutions | ||||||||||||||
| Accrued investment income | 12,012 | 11,641 | ||||||||||||
Receivable for investments sold ¹ | 1,651 | — | ||||||||||||
| Guaranty funds on deposit | 67 | 83 | ||||||||||||
| Other | 5,290 | 2,575 | ||||||||||||
| Total other assets — Insurance Solutions | 19,020 | 14,299 | ||||||||||||
| Interest receivable of consolidated VIEs | 1,100 | 955 | ||||||||||||
| Total other assets — Insurance Solutions including consolidated VIEs | 20,120 | 15,254 | ||||||||||||
| Total other assets | $ | 30,088 | $ | 26,419 | ||||||||||
_______________
(1)Represents amounts due from third-parties for investment sales for which a cash settlement has not occurred.
(2)All purchase receivables were acquired during the fourth quarter of 2025 and the first quarter of 2026. For the three months ended September 30, 2026, $0.5 million repayments were received on these receivables which reduced cost, and there were $0.2 million unrealized gains from fair value movements. For the nine months ended September 30, 2026, $0.8 million repayments were received on these receivables which reduced cost, and there were $0.3 million unrealized gains from fair value movements.
Accrued expenses and other liabilities consist of the following:
| As of | September 30, 2026 | December 31, 2025 | ||||||||||||
| Asset Management | ||||||||||||||
| Operating lease liabilities | $ | — | $ | 408 | ||||||||||
Accounts payable and accrued liabilities¹ | 4,853 | 9,107 | ||||||||||||
| Total accrued expenses and other liabilities — Asset Management | 4,853 | 9,515 | ||||||||||||
| Insurance Solutions | ||||||||||||||
Payable for investments purchased² | 48 | 6,500 | ||||||||||||
| Other accrued expenses | 3,690 | 4,010 | ||||||||||||
| Total accrued expenses and other liabilities — Insurance Solutions | 3,738 | 10,510 | ||||||||||||
| Total accrued expenses and other liabilities | $ | 8,591 | $ | 20,025 | ||||||||||
_______________
(1)As part of its acquisition of TURN in connection with the Business Combination on September 12, 2025, the Company acquired benefit plans which TURN historically administered which provide medical and dental insurance for retirees and their spouses who, at the time of their retirement, attained certain years of service at a certain age. As of September 30, 2026, the Company had $0.4 million accumulated post-retirement benefit obligation. These plans were terminated prior to the acquisition date and provide medical benefits to former employees who are grandfathered under
57
the plan’s former terms. The net periodic post-retirement benefit cost includes service cost and interest cost on the accumulated post-retirement benefit obligation. Unrecognized actuarial gains and losses will be recognized as net periodic benefit cost within general, administrative and other expenses under the Asset Management segment. Unamortized prior service cost was fully amortized prior to the acquisition date. Refer to Note 3. Business combinations and Asset Acquisitions for more information on the Company’s acquisition of TURN.
(2)Represents amounts owed to third-parties for investment purchases for which a cash settlement has not occurred.
Note 18. Income taxes
Prior to the Domestication of Legacy Mount Logan to the United States on September 12, 2025, Legacy Mount Logan was subject to income tax in Canada, including on income earned through its US subsidiaries. Following the Domestication and the completion of the Business Combination, the Company is subject to U.S. federal, state, and local income taxes.
The Company’s income tax provision totaled nil and $2.3 million for the three months ended September 30, 2026 and 2025, respectively, and totaled nil and $2.3 million for the nine months ended September 30, 2026 and 2025, respectively. The Company’s effective income tax rate was approximately 0% and (20.72)% for the three months ended September 30, 2026 and 2025, respectively, and 0% and (12.45)% for the nine months ended September 30, 2026 and 2025, respectively.
The Company recorded a full valuation allowance against its net deferred tax assets, reflecting management's conclusion — based on cumulative losses and Section 382 limitations on loss and capital-loss carryforwards acquired from TURN — that the related deferred tax assets are not more-likely-than-not to be realized.
Each reporting period, the Company assesses available positive and negative evidence to estimate whether sufficient future taxable income will be generated to realize its deferred tax assets. There were no changes in the assessment of the realizability of the Company's deferred tax assets during the nine months ended September 30, 2026.
The Company had no material uncertain tax positions as of September 30, 2026.
Note 19. Equity
Common shares
The number of shares issued and outstanding, earnings per share, additional paid-in capital, dividends paid per share and all references to share quantities of the Company have been retrospectively adjusted to reflect the Company’s existing capital structure post merger with TURN. Refer to Note 3. Business combinations and Asset Acquisitions for further detail.
The Company is authorized to issue 150 million common shares, par value $0.001 per share. The common shares are not redeemable or convertible. Dividends are declared by the Company’s Board of Directors (the “Board”) at its discretion. Historically, the board of directors of Legacy Mount Logan has declared dividends on a quarterly basis and the amount could vary from quarter to quarter.
As of September 30, 2026, there were 11,490,883 common shares issued and outstanding (December 31, 2025 – 12,786,770). The Company repurchased 1,590,601 shares through a tender offer, a former officer returned 7,401 shares to the Company for withholding tax, and the Company issued 302,115 shares for the acquisition of the TSA associated with the Yieldstreet asset acquisition (refer to Note 3. Business combinations and Asset Acquisitions) during the nine months ended September 30, 2026. The Company issued 382,809 shares (net of tax) in respect of vested RSUs (inclusive of Dividend Equivalent Units (“DEUs”)), 4,101 shares in satisfaction of debt obligations owed in connection with the provision of certain consulting services, 637,880 common shares for the minority investment in Runway Growth Capital LLC (“Runway”), 122,308 common shares for the further investment in a Canadian fixed income manager, and 5,666,700 shares for the reverse acquisition of TURN during the nine months ended September 30, 2025. Subsequent to the Business Combination, during the three months ended September 30, 2025, the Company repurchased 160,637 common shares for an aggregate cost of $1.4 million. These repurchases are included in both the three- and nine-month periods ended September 30, 2025. There were no other transactions with shareholders for the three and nine months ended September 30, 2026 and 2025.
58
Dividends
Dividends to the Company's shareholders are recorded on the declaration date. The payment of any cash dividend to shareholders of the Company in the future will be at the discretion of the Board and will depend on, among other things, the financial condition, capital requirements and earnings of the Company, and any other factors that the Board may consider relevant.
The following table reflects the distributions declared on the common shares of the Company during the nine months ended September 30, 2026 and September 30, 2025:
| Dividend amount per share | Total dividend amount | |||||||||||||||||||||||||||||||||||||
| Declaration Date | Record Date | Payment Date | CAD | USD ¹ | CAD | USD ¹ | ||||||||||||||||||||||||||||||||
| March 5, 2026 | March 30, 2026 | April 15, 2026 | $ | — | $ | 0.03 | $ | — | $ | 336 | ||||||||||||||||||||||||||||
| May 14, 2026 | May 26, 2026 | June 10, 2026 | — | 0.03 | — | 333 | ||||||||||||||||||||||||||||||||
| August 11, 2026 | August 21, 2026 | August 31, 2026 | — | 0.03 | — | 338 | ||||||||||||||||||||||||||||||||
| $ | — | $ | 1,007 | |||||||||||||||||||||||||||||||||||
| Dividend amount per share | Total dividend amount | |||||||||||||||||||||||||||||||||||||
| Declaration Date | Record Date | Payment Date | CAD | USD ¹ | CAD | USD ¹ | ||||||||||||||||||||||||||||||||
| March 13, 2025 | April 3, 2025 | April 10, 2025 | $ | 0.08 | $ | 0.06 | $ | 573 | $ | 399 | ||||||||||||||||||||||||||||
| May 15, 2025 | May 27, 2025 | June 2, 2025 | 0.08 | 0.06 | 573 | 410 | ||||||||||||||||||||||||||||||||
| August 7, 2025 | August 19, 2025 | August 25, 2025 | 0.08 | 0.06 | 586 | 427 | ||||||||||||||||||||||||||||||||
| $ | 1,732 | $ | 1,236 | |||||||||||||||||||||||||||||||||||
_______________
(1)Dividends were issued and paid in CAD until the December 2025 dividend payment which was issued and paid in USD. For reporting purposes, CAD dividend amounts recorded in equity were translated to USD using the daily exchange rate on the date of declaration. Going forward, the Company expects to declare and pay dividends in USD.
Warrants
On January 26, 2024, Legacy Mount Logan issued 50 common share purchase warrants (each, a “Debenture Warrant”) for each of the 18,752 initial debenture units that were issued on a non-brokered private placement (refer to Note 12. Debt obligations for further detail). Following the completion of the Business Combination, every 4.22 Debenture Warrants entitle the holder to receive, upon exercise, one share of the Company's common stock at an exercise price of C$11.61 per share. As of September 30, 2026, an aggregate of up to 222,079 shares of the Company's common stock were issuable upon the exercise of the 937,600 Debenture Warrants outstanding (December 31, 2025 — 222,079). The Debenture Warrants are exercisable for a period of 8 years.
The Arrangement Warrants expired unexercised on October 19, 2025 and none were outstanding as of September 30, 2026 or December 31, 2025.
Each Debenture Warrant was exercisable to acquire one common share of Legacy Mount Logan at a price of C$2.75 per share for a period of eight (8) years from the issuance thereof, provided that the Debenture Warrants were not exercisable during the first twelve (12) months following the issuance. Accordingly, an aggregate of up to 222,079 shares of the Company are issuable upon the exercise of the 937,600 outstanding Debenture Warrants as of September 30, 2026 (December 31, 2025 - 222,079).
59
Accumulated other comprehensive income (loss)
| Unrealized investment gains (losses) on available-for-sale securities | Unrealized gains (losses) on hedging instruments | Remeasurement gains (losses) on future policy benefits related to discount rate | Cumulative translation adjustment | Accumulated other comprehensive income (loss) | ||||||||||||||||||||||||||||
| Balance at, December 31, 2025 | $ | (15,358) | $ | (907) | $ | 71,287 | $ | (21,858) | $ | 33,164 | ||||||||||||||||||||||
| Other comprehensive income (loss), before reclassifications | (11,801) | (10,844) | 20,901 | — | (1,744) | |||||||||||||||||||||||||||
| Less: reclassification adjustments for gains (losses) realized | (2,246) | (155) | — | — | (2,401) | |||||||||||||||||||||||||||
| Less: Income tax expense (benefit) | — | — | — | — | — | |||||||||||||||||||||||||||
| Balance at, September 30, 2026 | $ | (24,913) | $ | (11,596) | $ | 92,188 | $ | (21,858) | $ | 33,821 | ||||||||||||||||||||||
| Unrealized investment gains (losses) on available-for-sale securities | Unrealized gains (losses) on hedging instruments | Remeasurement gains (losses) on future policy benefits related to discount rate | Cumulative translation adjustment | Accumulated other comprehensive income (loss) | ||||||||||||||||||||||||||||
| Balance at, December 31, 2024 | $ | (21,318) | $ | (5,192) | $ | 85,409 | $ | (21,858) | $ | 37,041 | ||||||||||||||||||||||
| Other comprehensive income (loss), before reclassifications | 5,926 | 4,193 | (15,167) | — | (5,048) | |||||||||||||||||||||||||||
| Less: reclassification adjustments for gains (losses) realized | (258) | (1,044) | — | — | (1,302) | |||||||||||||||||||||||||||
| Less: Income tax expense (benefit) | — | — | — | — | — | |||||||||||||||||||||||||||
| Balance at, September 30, 2025 | $ | (15,134) | $ | 45 | $ | 70,242 | $ | (21,858) | $ | 33,295 | ||||||||||||||||||||||
Note 20. Equity based compensation
On May 30, 2019, the Company’s shareholders approved (i) a stock option plan (the “2019 Option Plan”) and (ii) a restricted share unit plan (the “2019 RSU Plan”), which were amended and re-approved by shareholders of the Company on June 7, 2024 to, among other things, increase the rolling limit thereunder from 10% to 15% of the common shares then issued and outstanding. Following the approval of Legacy Mount Logan shareholders on August 22, 2025 and the closing of the Business Combination, on November 5, 2025, the Board approved and ratified the 2025 Omnibus Incentive Plan (the “2025 Plan”). The effective date of the 2025 Plan was September 12, 2025 and upon its effectiveness, the 2019 Option Plan and 2019 RSU Plan were terminated and no further awards will be granted under either the 2019 Option Plan or the 2019 RSU Plan.
The Company awarded 922,302 RSUs with a grant date fair value of $2.8 million during the nine months ended September 30, 2026, under the 2025 Plan. The Company awarded 652,135 RSUs with a grant date fair value of $1.2 million during the nine months ended September 30, 2025, under the 2019 RSU Plan, which all accelerated and fully vested upon the closing of the Business Combination.
For the three months ended September 30, 2026 and 2025, the Company recorded equity-based compensation expense related to RSUs awarded under the 2025 Plan and 2019 RSU Plan of $0.4 million and $2.1 million, respectively. For the nine months ended September 30, 2026 and 2025, the Company recorded equity-based compensation expense related to RSUs awarded under the 2025 Plan and 2019 RSU Plan of $0.5 million and $2.8 million, respectively. As of September 30, 2026, there was $2.3 million of total unrecognized equity-based compensation expense related to unvested RSUs, which is expected to be recognized over a weighted-average term of 1.20 years . The Company has elected to account for forfeitures as they occur. Expense is recognized on a straight line basis over the life of the award.
A summary of the status of service-vesting awards granted under the 2025 Plan for the nine months ended September 30, 2026 is presented below:
60
| RSUs and DEUs Outstanding | ||||||||||||||||||||||||||||||||
| RSUs | Weighted average grant date fair value | DEUs | Weighted average grant date fair value | Total | ||||||||||||||||||||||||||||
| Unvested balance, January 1, 2026 | — | $ | — | — | $ | — | — | |||||||||||||||||||||||||
| Granted | 922,302 | 3.00 | — | — | 922,302 | |||||||||||||||||||||||||||
| Vested | — | — | — | — | — | |||||||||||||||||||||||||||
| Forfeitures | — | — | — | — | — | |||||||||||||||||||||||||||
| Unvested balance, September 30, 2026 | 922,302 | $ | 3.00 | — | $ | — | 922,302 | |||||||||||||||||||||||||
There were no options or awards issued or outstanding under the 2019 Option Plan as of September 30, 2026 (December 31, 2025 – nil)
Note 21. Earnings per share
Basic earnings per share is calculated by dividing net income or loss attributable to common shareholders by the weighted average number of common shares outstanding during the period. Diluted earnings per share is calculated in the same manner, with further adjustments made to reflect the dilutive impact of instruments convertible into the Company’s common shares.
The Company has granted RSUs that provided the right to receive, subject to vesting during continued employment, shares of common stock pursuant to the RSU Plan. Any dividend equivalent paid to an employee on RSUs were returned to the Company upon forfeiture of the award by the employee. Unvested RSUs that are entitled to forfeitable dividend equivalents do not qualify as participating securities and are excluded in the Company’s basic and diluted earnings per share computations. Vested RSUs qualify as participating securities and are included in the Company’s diluted earnings per share computation.
The Company also has issued warrants which are exercisable to acquire one common share at a defined exercise price.
The following table sets forth the computation of basic and diluted income (loss) per common share for the three and nine months ended September 30, 2026 and September 30, 2025:
| Three months ended September 30, | Nine months ended September 30, | |||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||
| Basic earnings per share | ||||||||||||||||||||||||||
| Net income (loss) | $ | (3,725) | $ | (13,436) | $ | (13,872) | $ | (21,075) | ||||||||||||||||||
| Weighted-average number of common shares outstanding | 11,313,555 | 8,174,426 | 11,430,978 | 7,185,669 | ||||||||||||||||||||||
| Basic earnings (loss) per share | $ | (0.33) | $ | (1.64) | $ | (1.21) | $ | (2.93) | ||||||||||||||||||
| Diluted earnings per share | ||||||||||||||||||||||||||
| Net income (loss) | $ | (3,725) | $ | (13,436) | $ | (13,872) | $ | (21,075) | ||||||||||||||||||
| Weighted-average number of common shares outstanding | 11,313,555 | 8,174,426 | 11,430,978 | 7,185,669 | ||||||||||||||||||||||
| Incremental Common Shares | ||||||||||||||||||||||||||
Assumed exercise of warrants ¹ | — | — | — | — | ||||||||||||||||||||||
Common shares potentially issuable ² | — | — | — | — | ||||||||||||||||||||||
| Weighted-average number of diluted common shares outstanding | 11,313,555 | 8,174,426 | 11,430,978 | 7,185,669 | ||||||||||||||||||||||
| Diluted earnings (loss) per share | $ | (0.33) | $ | (1.64) | $ | (1.21) | $ | (2.93) | ||||||||||||||||||
________________
(1)For the three and nine months ended September 30, 2025, both the Arrangement Warrants and the Debenture Warrants were anti-dilutive and are excluded from the calculation of diluted earnings per share. The Arrangement Warrants expired on October 19, 2025. For the three and nine months ended September 30, 2026, the Debenture Warrants were anti-dilutive and are excluded from the calculation of diluted earnings per share.
(2)For the three and nine months ended September 30, 2026 and 2025, RSUs granted and unvested were anti-dilutive and are excluded from the calculation of diluted earnings per share.
61
The following table summarizes the anti-dilutive securities that are excluded from the computation of diluted income (loss) per share:
| Three months ended September 30, | Nine months ended September 30, | |||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||
| Anti-dilutive Securities | ||||||||||||||||||||||||||
| Weighted-average number of unexercised warrants | 222,079 | 828,088 | 222,079 | 828,088 | ||||||||||||||||||||||
| Weighted-average number of RSUs outstanding, inclusive of DEUs | 803,097 | 345,984 | 320,870 | 424,441 | ||||||||||||||||||||||
| Total common shares equivalent | 1,025,176 | 1,174,072 | 542,949 | 1,252,529 | ||||||||||||||||||||||
The basic and diluted weighted average number of shares issued, anti-dilutive securities, and earnings per share have been retrospectively adjusted to reflect the equivalent number of shares issued to holders of the Company following the Business Combination.
Note 22. Related parties
Servicing Agreement
BC Partners Advisors L.P. (“BCPA”) provides administrative services to the Company under a servicing agreement, and is reimbursed for an allocable portion of compensation paid to the Company's Chief Financial Officer and associated management personnel, and out-of-pocket expenses. For the three and nine months ended September 30, 2026, the Company incurred administrative fees of $1.8 million and $6.1 million (September 30, 2025 – $1.5 million and $3.9 million). As of September 30, 2026, administrative fees payable to BCPA was $3.2 million (December 31, 2025 – $1.7 million).
Staffing and Resource Agreement
Under a Staffing and Resource Agreement, BCPA makes available certain personnel and other resources to support the Company's investment advisory operations. Personnel provided by BCPA are not employees of the Company. The Company pays BCPA a quarterly service fee calculated as a percentage of fee-earning assets under management and may pay equity-based compensation to BCPA or its designees. For the three and nine months ended September 30, 2026, the Company incurred fees payable to BCPA of $1.0 million and $3.0 million (September 30, 2025 – $nil). As of September 30, 2026, fees payable to BCPA was $2.0 million (December 31, 2025 – $1.0 million).
Transactions with Affiliates - servicing fees
Through MLC US Holdings, the Company provides administrative services to SCIM in respect of the management of Alternative Credit Income Fund ("ACIF") in exchange for a servicing fee, under which the Company receives the net economic benefit derived by SCIM under the ACIF advisory agreement, subject to certain retained amounts and expense reimbursements. For the three and nine months ended September 30, 2026, the Company incurred servicing fees of $0.8 million and $2.3 million (September 30, 2025 – $0.4 million and $1.5 million).
The Company, through MLC US Holdings, holds a promissory note issued to SCIM maturing October 30, 2040, bearing interest at 8.0% per annum. As of September 30, 2026, the outstanding principal value of the note was $nil (December 31, 2025 – $13.6 million). For the three and nine months ended September 30, 2026, total interest income was $0.3 million and $0.8 million (September 30, 2025 – $0.3 million and $0.8 million). As of September 30, 2026, accrued interest income receivable was $nil (December 31, 2025 – $3.0 million).
After the ACIF Merger, the Company will no longer provide administrative services to SCIM in respect of ACIF and therefore the Company will no longer receive the net economic benefit derived by SCIM under the ACIF advisory agreement. The promissory note issued to SCIM will no longer be outstanding and the Company will not be entitled to receive the outstanding principal value of the note or the accrued interest receivable at the time of the ACIF Merger.
Transactions with Affiliates - profit sharing interest
MLCSC Holdings LLC, a wholly-owned subsidiary of the Company, is entitled to 16.03% of BCPA's distributions from SCIM under a Profit-Sharing Agreement with BCPSC Holdings LLC, a wholly-owned subsidiary of BCPA and the majority owner of SCIM. The Company holds a 24.99% minority ownership interest in SCIM. The Profit-
62
Sharing Agreement is carried as an indefinite-lived intangible asset of $8.2 million. Income earned is recorded within "Other income (loss), net". For the three and nine months ended September 30, 2026, income earned was $0.2 million and $0.8 million (September 30, 2025 – 0.3 million).
After the ACIF Merger, the Company will be entitled to a 29.88% share of the revenues from BCPL in the form of the Revenue Share Amount. The Revenue Share Amount is an intangible asset recorded at $12.2 million as of September 30, 2026. The Company will remit one third of the Revenue Share Amount it receives from BCPL every quarter to SCIM in order to pay for the Remaining CIF Payable that remains after netting the $3.8 million and $7.2 million of accrued interest receivable and ACIF Economics Payable, respectively, as of the 9 months ended September 30, 2026.
Potential Conflicts of Interest
The Company's senior management team is comprised of substantially the same personnel as the senior management team of BCPA, and such personnel may serve in similar or other capacities for BCPA or to future investment vehicles affiliated with BC Partners. As a result, such personnel provide investment advisory services to the Company and certain investment vehicles considered affiliates of BC Partners.
Other Transactions with BCPA or their Affiliates
The Servicing Agent, BCPA, may, from time to time, pay amounts owed by the Company to third-party providers of goods or services, and the Company will subsequently reimburse the Servicing Agent for such amounts paid on its behalf. Amounts payable to the Servicing Agent are settled in the normal course of business without any formal payment terms. As of September 30, 2026, operating expenses reimbursable to BC Partners for amounts paid on behalf of the Company was $5.9 million (December 31, 2025 – $4.5 million).
The Company may, from time to time, enter into transactions in the normal course of operations with entities that are considered affiliates involved in the credit business of BCPA (“BCPA Credit Affiliates”). As of September 30, 2026, Asset Management held investments with affiliates of BCPA Credit Affiliates totaling $10.2 million (December 31, 2025 – $25.4 million), and Insurance Solutions held investments with affiliates of BCPA Credit Affiliates totaling $16.0 million (December 31, 2025 – $20.9 million). On these investments, Asset Management recognized (i) interest income of $0.3 million and $0.8 million for the three and nine months ended September 30, 2026 (September 30, 2025 - $0.3 million and $0.8 million) respectively, (ii) earnings on equity method investments of $0.1 million and $0.7 million for the three and nine months ended September 30, 2026 (September 30, 2025 - $0.5 million and $0.8 million) respectively, and (iii) dividend income on equity securities of less than $0.1 million for both the three and nine months ended September 30, 2026 (September 30, 2025 – less than $0.1 million) respectively. On these investments, Insurance Solutions recognized (i) interest income of $0.4 million and $1.3 million for the three and nine months ended September 30, 2026 and $nil and $0.9 million for the three and nine months ended September 30, 2025, respectively, and (ii) dividend income of less than $0.1 million and $0.1 million for the three and nine months ended September 30, 2026 and less than $0.1 million and $0.2 million for the three and nine months ended September 30, 2025, respectively.
Further, for the three and nine months ended September 30, 2026, the Company incurred expenses of $1.6 million and $5.0 million (September 30, 2025 - $1.8 million and $5.3 million) respectively to an affiliate, for third party administrative services relating to Ability for administering its long-term care block of business. As of September 30, 2026, there was a payable to this affiliate of $0.5 million (December 31, 2025 – $0.6 million).
Note 23. Segments
The Company conducts its business through two reportable segments: Asset Management and Insurance Solutions. The Company defines operating segments by type of product and business line. The Asset Management segment comprises all fee generating activities. The Insurance Solutions segment consists of two product lines within the insurance business, LTC and MYGA.
Segment information is utilized by the Company’s chief operating decision maker (“CODM”) to assess performance and to allocate resources. The Company’s Chief Executive Officer (“CEO”) is the CODM, who is also solely responsible for decisions related to the allocation of resources on a Company-wide basis.
For each segment, the CODM uses the key measure of Segment Income to allocate resources (including employees, financial or capital resources) to that segment in the annual budget and forecasting process. The performance is measured by the Company’s CODM on an unconsolidated basis because the CODM makes operating decisions and assesses the performance of each of the Company’s business segments based on financial and operating metrics and data that exclude the effects of consolidation. Each reportable segment is then responsible for managing its operating results,
63
developing products, defining strategies for services and distributions based on the profile and needs of its business and market.
Segment Income
Segment Income is the key performance measure used by the CODM in evaluating the performance of the asset management and insurance solutions segments. The CODM uses Segment Income to make key operating decisions such as the following:
•decisions related to the allocation of resources such as staffing decisions, including hiring and locations for deployment of the new hires;
•decisions related to capital deployment such as providing capital to facilitate growth for the business and/or to facilitate expansion into new businesses; and
•decisions related to expenses, such as determining annual discretionary bonuses and equity-based compensation awards to its employees and/or service providers.
Segment Income is a measure of profitability and has certain limitations in that it does not take into account certain items included under U.S. GAAP. Segment Income is the sum of (i) Fee Related Earnings and (ii) Spread Related Earnings (“SRE”). Segment Income excludes the effects of the consolidation of each segment, taxes and related payables, and other items unique to deriving each segment’s performance metric as explained respectively below.
Segment Income may not be comparable to similarly titled measures used by other companies and is not a measure of performance calculated in accordance with U.S. GAAP. We use Segment Income as a measure of operating performance, not as a measure of liquidity. Segment Income should not be considered in isolation or as a substitute for net income or other income data prepared in accordance with U.S. GAAP. The use of Segment Income without consideration of related U.S. GAAP measures is not adequate due to the adjustments described above. Management compensates for these limitations by using Segment Income as a supplemental measure to U.S. GAAP results, to provide a more complete understanding of our performance as management measures it. A reconciliation of Segment Income to its most directly comparable U.S. GAAP measure of income (loss) before income tax provision can be found in this footnote.
Fee Related Earnings
Fee Related Earnings (“FRE”) is a component of Segment Income that is used to assess the performance of the Asset Management segment. FRE is the sum of (i) management fees, (ii) performance fees received from certain managed funds, (iii) advisory and transactions fees, (iv) equity investment earnings related to fee generating vehicles, (v) interest income attributable to investment management activity, and (vi) other fee-related income derived from the Company’s profit-sharing agreement over a fee-generating vehicle less (a) fee-related compensation, excluding equity-based compensation, and (b) other associated operating expenses, which excludes amortization of acquisition-related intangible assets and interest and other credit facility expenses.
FRE excludes non-fee generating revenues and expenses, transaction-related charges, equity-based compensation costs, the amortization of intangible assets, the operating results of VIEs that are included in the Condensed Consolidated Financial Statements, and any other non-recurring income and expenses. In addition, FRE excludes interest and other financing costs related to the Company not attributable to any specific segment, and corporate overhead expenses incurred to support the operations of the business rather than directly fee-related. Management considers these types of costs corporate in nature, and are included only for reconciliation purposes to income (loss) before income tax (provision) benefit.
During the third quarter of 2026, the Company revised its definition of FRE to include a proportionate share of operating income on asset management investments held at fair value. Previously, these amounts were excluded from FRE. This change has been applied to all periods presented in the Segment Income table below, and prior period amounts have been recast to conform to the current presentations. The change had no impact on the Company’s condensed consolidated financial statements.
Spread Related Earnings
SRE is a component of Segment Income that is used to assess the performance of the Insurance Solutions segment, excluding certain market volatility, which consists of realized and unrealized investment gains (losses), other income and certain general, administrative & other expenses. For the Insurance Solutions segment, SRE equals the sum of
64
(i) the net investment earnings on Insurance Solutions segment’s net invested assets, excluding net realized gains (losses) on the sale of investments, and investment earnings on funds held under reinsurance contracts and Modco agreements, less (ii) cost of funds (as described below), (iii) compensation and benefits, (iv) interest expense and (v) operating expenses.
Cost of funds includes liability costs associated with the crediting cost on MYGA liabilities as well as other liability costs. Other liability costs include DAC amortization, the cost of liabilities associated with LTC, net of reinsurance, which includes change in reserves, premiums, actual claim experience including related expenses and certain product charges related to MYGA.
During the third quarter of 2026, the Company revised its definition of SRE to exclude net realized gains (losses) on the sale of investments from net investment earnings on Insurance Solutions segment’s net invested assets. Previously these amounts were included in SRE. This change has been applied to all periods presented in the Segment Income table below, and prior period amounts have been recast to conform to the current presentations. The change had no impact on the Company’s condensed consolidated financial statements.
The following presents financial data for the Company’s reportable segments and the reconciliation of Segment Income to Income (loss) before taxes reported in the Condensed Consolidated Statements of Operations:
65
| Three months ended September 30, | Nine months ended September 30, | |||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||
| Management fees | $ | 3,542 | $ | 3,471 | $ | 10,300 | $ | 12,300 | ||||||||||||||||||
| Incentive fees | — | 431 | 813 | 1,208 | ||||||||||||||||||||||
| Advisory and transaction fees, net | — | — | 66 | — | ||||||||||||||||||||||
| Equity investment earnings | 144 | 481 | 659 | 805 | ||||||||||||||||||||||
Interest income¹ | 274 | 275 | 813 | 814 | ||||||||||||||||||||||
| Share of Operating Income on Investments held at FV | 1 | 144 | 204 | 357 | ||||||||||||||||||||||
| Other fee-related income | 194 | 262 | 836 | 262 | ||||||||||||||||||||||
| Fee-related compensation | (1,371) | (1,175) | (3,708) | (3,777) | ||||||||||||||||||||||
| Other operating expenses: | ||||||||||||||||||||||||||
| Administration and servicing fees | (1,489) | (896) | (4,346) | (2,834) | ||||||||||||||||||||||
| General, administrative and other | (823) | (326) | (2,359) | (1,764) | ||||||||||||||||||||||
| Fee related earnings | 472 | 2,667 | 3,278 | 7,371 | ||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||
| Net investment income | 12,535 | 12,404 | 36,703 | 37,094 | ||||||||||||||||||||||
| Cost of funds | (6,721) | (7,273) | (18,115) | (23,946) | ||||||||||||||||||||||
| Compensation and benefits | — | (73) | — | (540) | ||||||||||||||||||||||
| Interest expense | (300) | (408) | (1,018) | (1,143) | ||||||||||||||||||||||
| General, administrative and other | (2,807) | (3,153) | (9,330) | (9,340) | ||||||||||||||||||||||
| Spread related earnings | 2,707 | 1,497 | 8,240 | 2,125 | ||||||||||||||||||||||
| Segment income | $ | 3,179 | $ | 4,164 | $ | 11,518 | $ | 9,496 | ||||||||||||||||||
| Asset Management Adjustments: | ||||||||||||||||||||||||||
| Intersegment management fee eliminations | (1,668) | (1,620) | (5,096) | (4,400) | ||||||||||||||||||||||
Administration and servicing fees ² | (904) | (668) | (2,654) | (1,779) | ||||||||||||||||||||||
| Transaction costs | (17) | (3,185) | (51) | (10,483) | ||||||||||||||||||||||
Compensation and benefits ² | (90) | (861) | (436) | (1,802) | ||||||||||||||||||||||
| Equity-based compensation | (422) | (1,240) | (502) | (1,632) | ||||||||||||||||||||||
| Amortization and impairment of intangible assets | (512) | (8,272) | (1,630) | (11,071) | ||||||||||||||||||||||
| Interest and other credit facility expenses | (2,185) | (1,970) | (6,362) | (5,876) | ||||||||||||||||||||||
General, administrative and other ² | (1,577) | (2,654) | (4,915) | (4,197) | ||||||||||||||||||||||
| Net realized and change in unrealized gains (losses) from investment activities | (1,044) | 1,342 | (2,362) | 3,050 | ||||||||||||||||||||||
| Dividend income | 9 | 22 | 74 | 89 | ||||||||||||||||||||||
| Interest income - bank interest | 8 | — | 154 | — | ||||||||||||||||||||||
| Other income (loss), net | 13 | (11) | 17 | 294 | ||||||||||||||||||||||
| Loss on extinguishment of debt | — | — | (472) | — | ||||||||||||||||||||||
| Gain on acquisition | — | 4,457 | — | 4,457 | ||||||||||||||||||||||
| Share of Operating Income on Investments held at FV | (1) | (144) | (204) | (357) | ||||||||||||||||||||||
| Insurance Solutions Adjustments: | ||||||||||||||||||||||||||
| Equity-based compensation | — | (885) | — | (1,166) | ||||||||||||||||||||||
| Net unrealized gains (losses) from investment activities | (1,252) | (1,116) | (5,890) | 2,959 | ||||||||||||||||||||||
| Other income | 2,128 | 76 | 2,272 | 230 | ||||||||||||||||||||||
| Intersegment management fee eliminations | 1,668 | 1,620 | 5,096 | 4,400 | ||||||||||||||||||||||
General, administrative and other ³ | (324) | (185) | (1,695) | (954) | ||||||||||||||||||||||
| Write down of DAC due to recapture | (734) | — | (734) | — | ||||||||||||||||||||||
| Income (loss) before taxes | $ | (3,725) | $ | (11,130) | $ | (13,872) | $ | (18,742) | ||||||||||||||||||
_______________
(1)Represents interest income on a loan asset related to a fee generating vehicle.
(2)Represents corporate overhead allocated to each segment.
(3)Represents costs incurred by the insurance segment for purposes of U.S. GAAP reporting including one-time upfront cost associated with the new initiatives but not the day-to-day operations of the insurance company.
66
The following presents financial data for the Company’s reportable segments and the reconciliation of Segment Revenue to total revenue reported in the Condensed Consolidated Statements of Operations:
| Three months ended September 30, | Nine months ended September 30, | |||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||
| Segment Revenues | ||||||||||||||||||||||||||
| Asset Management | $ | 4,155 | $ | 5,064 | $ | 13,691 | $ | 15,746 | ||||||||||||||||||
| Insurance Solutions | 12,535 | 12,404 | 36,703 | 37,094 | ||||||||||||||||||||||
| Total segment revenues | 16,690 | 17,468 | 50,394 | 52,840 | ||||||||||||||||||||||
| Asset Management Adjustments: | ||||||||||||||||||||||||||
| Intersegment management fee eliminations | (1,668) | (1,620) | (5,096) | (4,400) | ||||||||||||||||||||||
| Interest income | (274) | (275) | (813) | (814) | ||||||||||||||||||||||
| Other fee-related income | (194) | (262) | (836) | (262) | ||||||||||||||||||||||
| Share of Operating Income on Investments held at FV | $ | (1) | $ | (144) | (204) | (357) | ||||||||||||||||||||
| Insurance Solutions Adjustments: | ||||||||||||||||||||||||||
| Net Premiums | (4,389) | (4,492) | (13,107) | (12,743) | ||||||||||||||||||||||
| Product charges | 143 | 184 | 429 | 1,766 | ||||||||||||||||||||||
| Net realized and change in unrealized gains (losses) from investment activities | (1,252) | (1,116) | (5,890) | 2,959 | ||||||||||||||||||||||
| Other income | 2,128 | 76 | 2,272 | 230 | ||||||||||||||||||||||
| Intersegment management fee eliminations | 1,668 | 1,620 | 5,096 | 4,400 | ||||||||||||||||||||||
| Total revenues | $ | 12,851 | $ | 11,439 | $ | 32,245 | $ | 43,619 | ||||||||||||||||||
The following presents financial data for the Company’s reportable segments and the reconciliation of the Company’s total reportable segment assets to total assets reported in the Condensed Consolidated Statements of Financial Position:
| As of | September 30, 2026 | December 31, 2025 | ||||||||||||
| Segments Assets | ||||||||||||||
| Asset Management | $ | 134,015 | $ | 145,226 | ||||||||||
| Insurance Solutions | 1,361,588 | 1,534,295 | ||||||||||||
| Total segment assets | 1,495,603 | 1,679,521 | ||||||||||||
| Asset Management Adjustments: | ||||||||||||||
| Intersegment investments | (77,302) | (71,705) | ||||||||||||
| Intersegment receivables | (8,545) | (7,098) | ||||||||||||
| Total assets | $ | 1,409,756 | $ | 1,600,718 | ||||||||||
Note 24. Commitments and contingencies
Investment commitments
In the normal course of business, the Company may enter into commitments to fund investments, which are not reflected in the Condensed Consolidated Financial Statements. There were nil and $45.8 million of outstanding investment commitments as of September 30, 2026 for Asset Management and Insurance Solutions, respectively (December 31, 2025 – $1.4 million and $49.5 million).
Contingent liabilities and litigation
The Company may be subject to lawsuits in the normal course of business. Insurance in particular is a highly regulated industry and lawsuits related to claim payments should be expected in the normal course of business. In the Asset Management business certain types of investment vehicles, especially those offered to individual investors, may subject the Company to a variety of risks, including new and greater levels of public and regulatory scrutiny, regulation, risk of litigation and reputation risk, which could materially and adversely affect the Company. Other potential lawsuits include allegations of mis-selling in the Insurance Solutions segment, among others. The Company considers this risk to be less likely given that Ability currently does not directly write insurance policies.
67
Ability at different times may receive notifications of the insolvency of various insurance companies. It is expected that such insolvencies would result in a Guaranty Fund Assessment against Ability at some future date. At this time, the Company is unable to estimate the possible amounts, if any, of such assessments as no data is available from the National Organization of Life and Health Guaranty Associations in the United States. Accordingly, the Company is unable to determine the impact, if any, that such assessments may have on its financial position or results of operations.
Ability is subject to lawsuits and regulatory actions in the normal course of business that do not arise from or directly relate to claims on insurance policies. This category of business litigation typically involves, among other things, allegations of underwriting errors or misconduct and litigation related to regulatory activity. These nonclaims litigation matters are considered when determining general expense accruals are necessary. As of September 30, 2026 there were no litigation related expense accruals. Potential legal and regulatory actions are subject to inherent uncertainties, and future events could change management’s assessment of the probability or estimated amount of potential losses from pending or threatened legal and regulatory matters. A future adverse ruling by the courts in any pending cases could have a material adverse impact on the financial condition of Ability. Based on management’s best assessment at this time, Ability is adequately reserved for these cases as of September 30, 2026.
Note 25. Capital management and regulatory requirements
The Company’s capital structure consists of equity and debt. In order to maintain or adjust the capital structure, the Company actively manages its equity as capital and may adjust the amount of debt borrowings, dividends paid to shareholders, return capital to shareholders, issue new shares or sell assets. The Company's capital management framework takes into account the requirements of the Company as a whole as well as the needs and requirements of each of its subsidiaries. The Company’s officers and senior management are responsible for managing the Company’s capital and do so through quarterly portfolio management meetings and regular review of financial information.
As of September 30, 2026, the Company was in compliance with all financial covenants in its debt facilities. These include restrictions on the distribution capacity from MLC US Holdings to the Company.
Insurance capital requirements
Ability is subject to risk-based capital ("RBC") standards and other minimum capital and surplus requirements imposed by the Nebraska Department of Insurance. Regulatory action is triggered at an RBC ratio of 200% or below, and Ability must maintain a ratio in excess of 300% to reinsure new business. Ability's RBC ratio, tested annually as of Ability's fiscal year-end, was 501% as of December 31, 2025.
Insurance subsidiary dividend restrictions
Under Nebraska law, dividends payable from Ability's unassigned funds during any twelve-month period without prior approval of the Nebraska Department of Insurance are limited to the greater of 10% of Ability's surplus per the prior year-end statutory financial statement, or 100% of net gain from operations for the prior calendar year. Any dividend in excess of this limitation requires approval of the Insurance Director. During the three and nine months ended September 30, 2026 and 2025, Ability could not pay any dividends to its parent absent regulatory approval.
Ability’s statutory statements are presented on the basis of accounting practices determined by the Nebraska Department of Insurance (“NEDOI”). The NEDOI recognizes only permits and/or prescribes certain statutory accounting practices determining and reporting the financial condition and results of operations of an insurance company and for determining its solvency under insurance law. The amount of dividends that Ability may pay in a twelve-month period, without prior regulatory approval, is restricted by the laws of Nebraska.
Note 26. Concentration of Risks
Our current operations subject us to the following concentrations of risk:
Insurance Solutions
Historically, we have assumed our MYGA products, which is a part of our insurance operations, from two insurance companies, ACL and SSL. We have made a decision to no longer assume business from ACL and SSL as of June 30, 2024. However, the Company will continue to earn investment income from the cash proceeds of the existing MYGA contracts and the holders will continue to be a diversified base of numerous individuals. Effective March 31, 2025, Ability entered a new reinsurance treaty for additional MYGA with National Security Group (“NSG”), further diversifying its
68
reinsurance partners. Effective September 1, 2026, Sentinel Security Life Insurance Company (“SSL”) recaptured 50% of the quota share liability previously reinsured by the Company. See Note 15. Interest sensitive contract liabilities for further details.
Certain concentrations of credit risk related to reinsurance recoverable exist on LTC business, with the insurance organizations listed in the table below:
| As of September 30, 2026 | A.M. Best credit rating | Net reinsurance recoverable1 | Funds withheld payable | Net reinsurance credit exposure | ||||||||||||||||||||||
| Medico Insurance Company | A | $ | 2,191 | $ | — | $ | 2,191 | |||||||||||||||||||
| Front Street Re | Not Rated | 248,292 | 222,028 | 26,264 | ||||||||||||||||||||||
| Nichol International Reinsurance (S.A.C), Ltd. | Not Rated | 161,081 | 174,689 | — | ||||||||||||||||||||||
| Total | $ | 411,564 | $ | 396,717 | $ | 28,455 | ||||||||||||||||||||
| As of December 31, 2025 | A.M. Best credit rating | Net reinsurance recoverable1 | Funds withheld payable | Net reinsurance credit exposure | ||||||||||||||||||||||
| Medico Insurance Company | A | $ | 4,466 | $ | — | $ | 4,466 | |||||||||||||||||||
| Front Street Re | Not Rated | 273,981 | 237,143 | 36,838 | ||||||||||||||||||||||
| Nichol International Reinsurance (S.A.C), Ltd. | Not Rated | 178,273 | 183,802 | — | ||||||||||||||||||||||
| Total | $ | 456,720 | $ | 420,945 | $ | 41,304 | ||||||||||||||||||||
_______________
(1)Includes credit loss allowance of $0.8 million and $1.1 million as of September 30, 2026 and December 31, 2025 respectively, held against reinsurance recoverable.
Further, our Insurance Solutions segment has the following investment concentration risk:
| As of September 30, 2026 | ||||||||||||||
| Fair value | % of total | |||||||||||||
| Insurance Solutions | ||||||||||||||
| United States | $ | 633,159 | 73 | % | ||||||||||
| Cayman Islands | 182,834 | 21 | % | |||||||||||
Other¹ | 46,645 | 6 | % | |||||||||||
| Total insurance solutions | 862,638 | 100 | % | |||||||||||
| Insurance Solutions consolidated VIEs | ||||||||||||||
| United States | 120,897 | 94 | % | |||||||||||
Other² | 7,784 | 6 | % | |||||||||||
| Total insurance solutions consolidated VIEs | 128,681 | 100 | % | |||||||||||
| Total | $ | 991,319 | ||||||||||||
_______________
(1)Other consists of nominal investments primarily in Bermuda, Canada, and United Kingdom.
(2)Other consists of nominal investments primarily in Ireland and Canada.
| As of December 31, 2025 | ||||||||||||||
| Fair value | % of total | |||||||||||||
| Insurance Solutions | ||||||||||||||
| United States | $ | 688,545 | 72 | % | ||||||||||
| Cayman Islands | 207,034 | 22 | % | |||||||||||
Other¹ | 61,229 | 6 | % | |||||||||||
| Total insurance solutions | 956,808 | 100 | % | |||||||||||
| Insurance Solutions consolidated VIEs | ||||||||||||||
| United States | 111,781 | 93 | % | |||||||||||
Other2 | 8,899 | 7 | % | |||||||||||
| Total insurance solutions consolidated VIEs | 120,680 | 100 | % | |||||||||||
| Total | $ | 1,077,488 | ||||||||||||
_______________
69
(1)Other consists of nominal investments primarily in Bermuda, Canada, and United Kingdom.
(2)Other consists of nominal investments primarily in Ireland and Canada.
The Asset Management segment does not have meaningful investment concentration risk.
Note 27. Subsequent events
Management of the Company has evaluated subsequent events through the date these financial statements were issued. Based upon this evaluation, management has determined there were no items requiring adjustment of the financial statements. Management does note the following:
On October 20, 2026, the Company announced it had entered into a definitive agreement to become the new investment advisor to the Alternative Fund Advisors, LLC (“AFA”) Asset Based Lending Fund (“Fund”) (the “Transaction”). In connection with the Transaction, the Company and AFA, who is the Fund’s current investment advisor, have entered into an Asset Purchase Agreement (“APA”) pursuant to which the Company will acquire certain business records, intellectual property, and goodwill of AFA related to the management of the Fund which contains about $230 million of assets under management. The Company is expecting to pay $0.3 million in cash at closing and will make deferred cash installment payments to AFA based on the AUM of the Fund specified future dates. The Fund will be the Company’s second evergreen credit interval fund, complementing the Company’s Opportunistic Credit Interval Fund. The Transaction is expected to close in January 2027.
On November 3, 2026, the Board declared a cash dividend in the amount of $0.03 per common share to be paid on November 30, 2026 to shareholders of record on November 19, 2026.
70
Item 2. Management’s Discussion and Analysis of Financial Condition and Results of Operations
The following discussion and analysis of our financial condition and results of operations should be read in conjunction with Mount Logan’s condensed consolidated financial statements (the “Condensed Consolidated Financial Statements”) and the related notes within this Quarterly Report on Form 10-Q. As described in the section entitled “Cautionary Note Regarding Forward-Looking Statements,” this discussion contains forward-looking statements that are subject to known and unknown risks and uncertainties. Actual results and the timing of events may differ significantly from those expressed or implied in such forward-looking statements due to a number of factors, including those included in the section of the Company’s Annual Report on Form 10-K for the fiscal year ended December 31, 2025 entitled “Item 1A. Risk Factors.” The highlights listed below have had significant effects on many items within our Condensed Consolidated Financial Statements and affect the comparison of the current period’s activity with those of prior periods. Our historical results are not necessarily indicative of the results that may be expected for any period in the future, and our interim results are not necessarily indicative of the results we expect for the full fiscal year or any other period.
Nature of Business
General
Mount Logan’s Business
Mount Logan, together with its consolidated subsidiaries is an alternative asset management and insurance solutions company. Mount Logan manages its business through two business segments: Asset Management and Insurance Solutions. Its Asset Management segment is focused on investing in and actively managing credit investment opportunities in North America through its wholly-owned subsidiary Mount Logan Management LLC (“ML Management”). The Insurance Solutions segment is conducted by Ability Insurance Company (“Ability”), a Nebraska domiciled insurer that specializes in reinsuring annuity products for the increasing number of individuals seeking to fund retirement needs. Ability also holds a run-off book of long-term care policies. As of October 1, 2025 and through September 30, 2026, Mount Logan has no direct full time employees.
Asset Management
Mount Logan’s Asset Management segment focuses on generating recurring asset management fee streams across a variety of credit investing strategies. Mount Logan raises, invests and manages funds, accounts and other vehicles with an emphasis on private credit. As of September 30, 2026, Mount Logan had a total AUM of $1.8 billion.
As an alternative asset manager, through Mount Logan’s wholly and partially owned SEC-registered investment advisers (“RIAs”), Mount Logan earns management and incentive fees for providing investment advisory and management services to multiple diversified investment vehicles, which include Mount Logan’s Insurance Solutions segment. The majority of these vehicles are permanent or semi-permanent capital, generating recurring management and fee-related performance fees from indefinite term vehicles, that are measured and received on a recurring basis, primarily focused on North American and European direct and indirect private loan origination in the middle-market across the capital structure, as well as corporate credit, specialty finance, and other mandates across managed accounts and CLOs. Mount Logan benefits from its investment in and expansion into high-growth areas of private credit and private solutions investing, including asset-backed finance, opportunistic credit, and venture and growth lending. Beyond participation in the traditional primary and secondary credit markets, through Mount Logan’s origination and corporate solutions capabilities, Mount Logan seeks to originate assets with attractive risk-adjusted returns, in the funds Mount Logan manages, through the employment of rigorous and deep diligence on the opportunities Mount Logan assesses.
Through Mount Logan’s RIAs, Mount Logan seeks to invest in well-established middle market businesses that operate across a wide range of industries (i.e., no concentration in any one industry). Mount Logan employs fundamental credit analysis, targeting investments in businesses with relatively low levels of cyclicality and operating risk. Mount Logan has experience managing levered vehicles, both public and private, and seeks to enhance returns through the prudent use of leverage with a conservative approach that prioritizes downside protection and capital preservation. Mount Logan believes this strategy and approach offers attractive risk-adjusted returns with lower volatility featuring the potential for fewer defaults and greater resilience through market cycles.
The amount of fees charged for managing these assets depends on the underlying investment strategy, vehicle being managed, liquidity profile, and, ultimately, Mount Logan’s ability to generate returns for Mount Logan’s clients. After expenses associated with generating fee-related revenues, Mount Logan measures the resulting earnings stream “Fee Related Earnings” or “FRE”, which represents the primary performance measure for the Asset Management segment. FRE
71
is the sum of (i) management fees, (ii) performance fees received from certain managed funds, (iii) advisory and transaction fees, (iv) equity investment earnings related to fee generating vehicles, (v) interest income attributable to investment management activity, and (vi) other fee-related income derived from the Company’s profit-sharing agreement with BCPSC Holdings LLC, a wholly owned subsidiary of BCPA (the “Profit-Sharing Agreement”) over a fee-generating vehicle less (a) fee-related compensation, excluding equity-based compensation, and (b) other associated operating expenses, which excludes amortization of acquisition-related intangible assets and interest and other credit facility expenses. FRE excludes non-fee generating revenues and expenses, transaction-related charges, equity-based compensation costs, the amortization of intangible assets, the operating results of variable interest entities (“VIEs”) that are included in the Condensed Consolidated Financial Statements, and any other non-recurring income and expenses. In addition, FRE excludes interest and other financing costs related to Mount Logan not attributable to any specific segment, and corporate overhead expenses incurred to support the operations of the business rather than directly fee-related. Management considers these types of costs corporate in nature, and are included only for reconciliation purposes to income (loss) before income tax (provision) benefit. FRE is a key financial metric that we defined and report as a non-GAAP financial measure. See “—Segment Analysis—Asset Management” for a reconciliation of FRE to the most directly comparable U.S. GAAP measure.
The Asset Management segment also holds a minority interest in Sierra Crest Investment Management (“SCIM”), which manages BCIC, formerly known as Portman Ridge Finance Corp. (“Portman” or “Portman Ridge”), a United States business development company. SCIM is majority owned by BCPA.
Insurance Solutions
Mount Logan’s Insurance Solutions segment is operated by Ability, a Nebraska domiciled insurer and reinsurer of LTC policies and retirement savings products, licensed in 42 states and the District of Columbia. Upon closing of the acquisition of Ability in late 2021, ML Management entered into an investment management agreement with Ability (the “Ability IMA”) to manage certain of Ability’s assets that are within the scope of ML Management’s expertise in providing investment management advisory services (the assets of Ability managed by ML Management referred to herein as the “Managed Ability Portfolio”). In the second quarter of 2022, management began to implement its plan to expand and diversify the Insurance Solutions business, including ceasing to insure new long-term care risk and, instead, reinsuring multi-year guaranteed annuity (“MYGA”) policies. The Insurance Solutions segment also includes the economic benefits of the three Cornhusker CLOs (collectively, the “Cornhusker CLOs”), which represent consolidated VIEs. Annuity policies are contracts with insurers where individuals agree to pay a certain amount of money, either in a lump sum or through installments, which entitles them to receive a series of payments at a future date.
Long-term care insurance policies reimburse policyholders a daily amount, upon meeting certain requirements, for services to assist with daily living as they age. Ability’s long-term care portfolio’s morbidity risk has been largely reinsured to third-parties.
A reinsurance contract is a type of insurance contract that is issued by an entity (the reinsurer) to compensate another entity (the cedant) for claims arising from insurance contract(s) issued by the cedant.
Consistent with the overall business strategy, Ability assumes certain policy risks written by other insurance companies and cedes insurance risks to reinsurers. Reinsurance accounting is applied for reinsurance transactions when risk transfer provisions have been met. Ability reviews all contractual features, particularly those that may limit the amount of insurance risk to which the reinsurer is subject or features that delay the timely reimbursement of claims. Ability does not have any assumed or ceded reinsurance contracts for the LTC line of business that do not meet risk transfer requirements. The MYGA line of business does not meet the risk requirements to qualify as an insurance contract and is therefore considered an investment contract.
Ability uses ceded reinsurance contracts in the normal course of business to manage its risk exposure. For each of its reinsurance agreements, cessions under reinsurance agreements do not discharge Ability’s obligations as the primary insurer. Reinsurance assets represent the benefit derived from reinsurance agreements in force at the reporting date, considering the financial condition of the reinsurer. Amounts recoverable from reinsurers are estimated in accordance with the terms of the relevant reinsurance contract and historical reinsurance recovery information. Amounts recoverable from reinsurers are based on what Ability believes are reasonable estimates and the balance is reported as an asset in the Insurance section of the Condensed Consolidated Statements of Financial Position. However, the ultimate amount of the reinsurance recoverable is not known until all claims are settled.
Mount Logan provides a full suite of services for Ability’s investment portfolio, including direct investment management, asset allocation, mergers and acquisitions asset diligence and certain operational support services, including
72
investment compliance, tax, legal and risk management support. Mount Logan’s Insurance Solutions business focuses on generating spread income by combining the two core competencies of (1) sourcing long-term, persistent liabilities through reinsurance treaties and (2) using the scale and reach of Mount Logan’s Asset Management business to actively source or originate assets with Ability’s preferred risk and return characteristics. Ability’s investment philosophy is to invest a portion of its assets in securities that earn an incremental yield by taking measured liquidity and complexity risk and capitalize on its long-dated, persistent liability profile to prudently achieve higher net investment earned rates, rather than assuming incremental credit risk. Because Ability maintains discipline in reinsuring attractively priced liabilities, it has the ability to invest in a broad range of high-quality assets to generate attractive earnings.
Mount Logan uses Spread Related Earnings (“SRE”) to assess the performance of the Insurance Solutions segment. SRE is a component of Segment Income that is used to assess the performance of the Insurance Solutions segment, excluding certain market volatility, which consists of investment gains (losses), other income and certain general, administrative & other expenses. For the Insurance Solutions segment, SRE equals the sum of (i) the net investment earnings on Insurance Solutions segment’s net invested assets (excluding investment earnings on funds held under reinsurance contracts and modified coinsurance (“Modco”) agreement), less (ii) cost of funds (as described below), (iii) compensation and benefits, (iv) interest expense and (v) operating expenses. SRE represents the difference between actual earnings generated on the assets and investments made and the interest or crediting rate guaranteed to policyholders or participants. Rather than increasing allocations to higher risk securities to increase yields, or returns, on the assets invested, Ability and ML Management focus on proprietary origination of high-quality, predominantly senior secured loans and assets, which Mount Logan believes reduce downside risk.
The diagram below depicts Mount Logan’s current organizational structure:
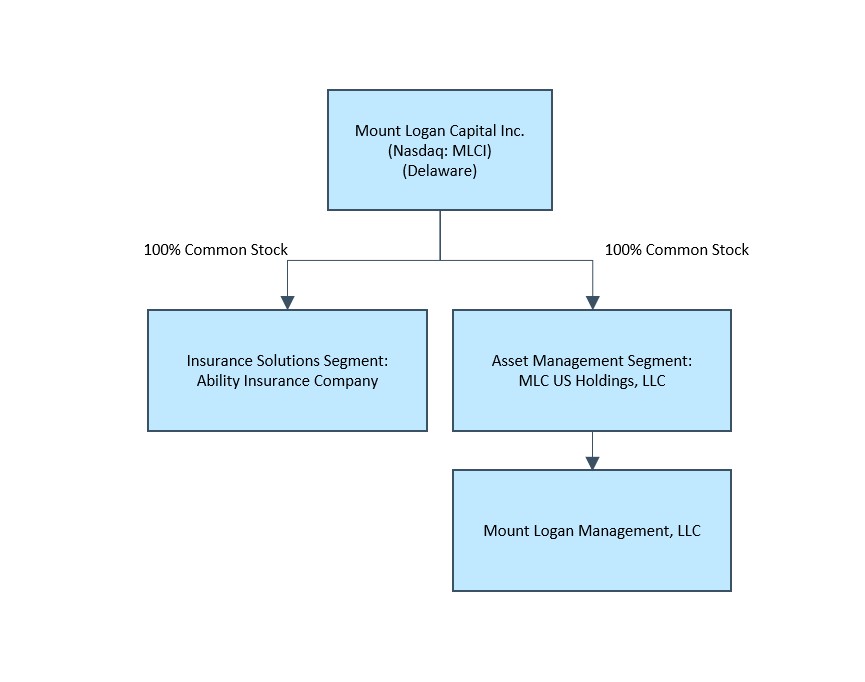
Note: The organizational structure chart above depicts a simplified version of the Mount Logan structure. It does not include all legal entities in the structure. The acquisition of 180 Degree Capital Corp. is reflected as part of the Asset Management segment.
Business Environment
Industry Trends and Market Conditions
Mount Logan’s asset management and insurance solutions businesses are affected by the conditions in the political environment and financial markets and economic conditions of the United States, such as changes in interest rates, availability of credit, and inflation rates (including persistent inflation). These conditions can significantly impact the
73
performance of Mount Logan’s business, including, but not limited to, the valuation of investments, including those of the vehicles Mount Logan manages, and related income that Mount Logan may recognize.
U.S. inflation increased to 3.7% as of September 30, 2026, and the Federal Reserve maintained the federal funds rate target range at 3.75%–4% throughout the third quarter. Continued inflation or interest rate volatility could adversely affect Mount Logan's business, financial condition, results of operations, liquidity, and cash flows.
Moreover, Ability is materially affected by conditions in the capital markets and the U.S. economy generally. Actual or perceived stressed conditions, volatility and disruptions in financial asset classes or various capital and credit markets may have an adverse effect on Mount Logan’s insurance business because such conditions may decrease the returns on, and value of, its investment portfolio.
Interest Rate Environment
Both medium-term and long-term rates increased between the second and third quarter of 2026, with the U.S. 10-year Treasury yield at 4.93% as of September 30, 2026 compared to 4.44% as of June 30, 2026. Short term rates decreased in the same period, with the 3-month average U.S. Secured Overnight Financing Rate (“SOFR”) at 3.68% as of September 30, 2026 compared to 3.73% as of June 30, 2026.
With respect to the Insurance Solutions segment, Ability’s investment portfolio consists predominantly of fixed maturity investments. Both rising and declining interest rates can negatively affect the income Ability derives from these interest rate spreads. During periods of rising interest rates, Ability may be contractually obligated to reimburse its clients for the greater amounts they credit on certain interest-sensitive products. However, Ability may not have the ability to immediately acquire investments with interest rates sufficient to offset the increased crediting rates on its reinsurance contracts. During periods of falling interest rates, Ability’s investment earnings will be lower because new investments in fixed maturity securities will likely bear lower interest rates. Ability may not be able to fully offset the decline in investment earnings with lower crediting rates on underlying annuity products related to certain of its reinsurance contracts. Higher interest rates may result in increased surrenders on interest-based products of Ability’s clients, which may affect its fees and earnings on those products. Lower interest rates may result in lower sales of certain insurance and investment products of Ability’s clients, which would reduce the demand for its reinsurance of these products. If interest rates remain low for an extended period, it may adversely affect Ability’s cash flows, financial condition and results of operations. Ability addresses interest rate risk through managing the duration of the liabilities it sources with assets it acquires through asset/liability management (“ALM”) programs. As part of its investment strategy, Ability purchases floating rate investments, which are expected to perform well in a rising interest rate environment and are expected to underperform in a declining rate environment. Ability manages its floating interest rate risk in a declining rate environment through hedging activity.
As of September 30, 2026, Ability’s net invested asset portfolio included $330.6 million of floating rate investments, or 50% of its net invested assets. In periods of prolonged low interest rates, the net investment spread may be negatively impacted by reduced investment income to the extent that Ability is unable to adequately reduce policyholder crediting rates due to policyholder guarantees in the form of minimum crediting rates or otherwise due to market conditions. A significant majority of the MYGA policies Ability reinsures have crediting rates that reset upon renewal. While Ability has the contractual right to not accept the renewals, its willingness to do so may be limited by competitive pressures.
Significant interest rate risk may arise from mismatches in the timing of cash flows from Ability’s assets and liabilities. Management of interest rate risk at the Company-wide level, and at the various operating company levels, is one of the main risk management activities in which MLC senior management engages.
Interest Rate Sensitivity
The following table summarizes the potential impact on net income of hypothetical base rate changes in interest rates on Mount Logan’s debt investments assuming a parallel shift in the yield curve, with all other variables remaining constant for the Insurance Solutions segment. The impact of interest rates sensitivity on the Asset Management segment is immaterial.
| As of | September 30, 2026 | December 31, 2025 | ||||||||||||
50 basis point increase1 | $ | 718 | $ | 653 | ||||||||||
50 basis point decrease1 | (718) | (653) | ||||||||||||
74
_______________
(1)Losses are presented in brackets and gains are presented as positive numbers.
Actual results may differ significantly from these sensitivity analyses. As such, the sensitivities should only be viewed as directional estimates of the underlying sensitivities for the respective factors based on the assumptions outlined above.
During the first quarter of 2024, Mount Logan entered into interest rate swaps to convert floating-rate interest receipts to fixed-rate interest receipts to reduce exposure to interest rate changes. Mount Logan recognize these derivatives as a Derivatives asset or Derivatives liability and they are presented on a gross basis in the Condensed Consolidated Statements of Financial Position and measured at fair value unless there is a legal right of set-off. Derivatives are initially measured at fair value with subsequent changes therein recognized in the Condensed Consolidated Statements of Comprehensive Income (Loss) as the swaps are in hedging relationships, with changes in fair value reclassified into Interest income in the same period as the hedged transactions affect earnings. Mount Logan’s derivative instruments are disclosed below:
| September 30, 2026 | Notional | Derivative assets | Derivative liabilities | |||||||||||||||||
| Interest rate swaps | $ | 187,000 | $ | — | $ | 11,596 | ||||||||||||||
| Total | 187,000 | — | 11,596 | |||||||||||||||||
| December 31, 2025 | Notional | Derivative assets | Derivative liabilities | |||||||||||||||||
| Interest rate swaps | $ | 187,000 | $ | 481 | $ | 1,388 | ||||||||||||||
| Total | 187,000 | 481 | 1,388 | |||||||||||||||||
The interest rate swaps are recorded in the Condensed Consolidated Statement of Financial Position as “Derivatives” within the Insurance Solutions segment with the mark-to-market changes in fair value being recorded as part of “Unrealized gains (losses) on hedging instruments” within the Insurance Solutions segment on the Condensed Consolidated Statement of Comprehensive Income (Loss).
Restricted cash posted as collateral consists of cash deposited at a bank that is pledged as collateral in connection with the interest rate swaps. The table below represents the cash posted as collateral associated with open derivative positions:
| As of | September 30, 2026 | December 31, 2025 | ||||||||||||
| Restricted cash posted as collateral | $ | 19,241 | $ | 9,973 | ||||||||||
| Total | 19,241 | 9,973 | ||||||||||||
Overview of Results of Operations
Financial Measures under U.S. GAAP - Asset Management
The following discussion of financial measures under U.S. GAAP is based on Mount Logan’s Asset Management business as of September 30, 2026.
Revenues
Management Fees
Mount Logan provides investment management services to investment funds, CLOs, managed accounts and other vehicles in exchange for a management fee. Management fees are determined quarterly using an annual rate which are generally based upon (i) a percentage of the capital committed during the commitment period, and thereafter based on the remaining invested capital of unrealized investments, or (ii) net asset value, gross assets, or as otherwise provided in the respective agreements. Management fees are recognized over time, during the period in which the related services are performed.
75
Incentive Fees
Mount Logan provides investment management services to investment funds, CLOs, managed accounts and other vehicles in exchange for a management fee, as discussed above and, in some cases an incentive fee, a type of performance revenue. The incentive fee consists of two parts: (i) an income incentive fee which is based on pre-incentive fee net investment income in excess of a hurdle rate and (ii) a capital gains incentive fee which is based on cumulative realized capital gains and losses and unrealized capital depreciation. Incentive fees are considered a form of variable consideration as they are based on the fund achieving certain investment return hurdles. Accordingly, the recognition of such fee is deferred until it is probable that a significant reversal in the amount of cumulative revenue will not occur, which is generally upon liquidation of the investment fund.
The following quarter to date and year to date tables summarize Mount Logan’s (i) management fees and (ii) incentive fees by fee generating vehicle:
| As of September 30, | As of September 30, | For the three months ended | For the three months ended | Quarter on Quarter change in Total Fees | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | September 30, 2026 | September 30, 2025 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Management Fees Receivable 7 | Incentive Fees Receivable 7 | Management Fees | Incentive Fees | Total Fees | Management Fees | Incentive Fees | Total Fees | $ Change | % Change | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Fee Generating Vehicle | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Ability (including consolidated VIEs) 1 | $ | 1,085 | $ | 537 | $ | — | $ | — | $ | 1,667 | $ | — | $ | 1,667 | $ | 1,620 | $ | — | $ | 1,620 | $ | 47 | 3 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||
BDCs 2 | — | — | — | — | — | — | — | 125 | — | 125 | (125) | (100) | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
CLOs 3 | 512 | 1,185 | — | — | 512 | — | 512 | 661 | — | 661 | (149) | (23) | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Interval Funds 4 | 296 | 109 | — | 430 | 566 | — | 566 | 364 | 430 | 794 | (228) | (29) | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Ovation Funds 5 | 209 | 139 | — | — | 319 | — | 319 | 383 | — | 383 | (64) | (17) | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Other 6 | 717 | 100 | — | — | 478 | — | 478 | 320 | — | 320 | 158 | 49 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Fees | $ | 2,819 | $ | 2,070 | $ | — | $ | 430 | $ | 3,542 | $ | — | $ | 3,542 | $ | 3,473 | $ | 430 | $ | 3,903 | $ | (361) | (9) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||
| As of September 30, | As of September 30, | For the nine months ended | For the nine months ended | Year on Year change in Total Fees | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | September 30, 2026 | September 30, 2025 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Management Fees Receivable 7 | Incentive Fees Receivable 7 | Management Fees | Incentive Fees | Total Fees | Management Fees | Incentive Fees | Total Fees | $ Change | % Change | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Fee Generating Vehicle | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Ability (including consolidated VIEs) 1 | $ | 1,085 | $ | 537 | $ | — | $ | — | $ | 5,096 | $ | — | $ | 5,096 | $ | 4,400 | $ | — | $ | 4,400 | $ | 696 | 16 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||
BDCs 2 | — | — | — | — | — | — | — | 1,729 | — | 1,729 | (1,729) | (100) | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
CLOs 3 | 512 | 1,185 | — | — | 1,669 | — | 1,669 | 2,124 | — | 2,124 | (455) | (21) | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Interval Funds 4 | 296 | 109 | — | 430 | 1,202 | 813 | 2,015 | 1,600 | 1,208 | 2,808 | (793) | (28) | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Ovation Funds 5 | 209 | 139 | — | — | 1,042 | — | 1,042 | 1,549 | — | 1,549 | (507) | (33) | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Other 6 | 717 | 100 | — | — | 1,291 | — | 1,291 | 899 | — | 899 | 392 | 44 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Fees | $ | 2,819 | $ | 2,070 | $ | — | $ | 430 | $ | 10,300 | $ | 813 | $ | 11,113 | $ | 12,301 | $ | 1,208 | $ | 13,509 | $ | (2,396) | (18) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||
______________
(1)ML Management earns a base management fee of 1% on the average statutory book value of the portion of Ability’s investments it manages. Management fees earned by ML Management from Ability are eliminated on consolidation.
(2)ML Management earned a base management fee of 1.75% on the gross assets of Logan Ridge until July 15, 2025 at which time Logan Ridge merged into Portman and became the newly merged entity - BCIC, and ML Management’s investment management agreement with Logan Ridge was terminated. Management fees earned indirectly through ML Management’s 24.99% interest in SCIM, which is the manager of BCIC (previously Portman), are excluded as management fee revenue, but are paid as cash distributions from SCIM. Upon the merger of Logan Ridge and Portman, on July 15, 2025, the Company through MLCSC Holdings LLC, a wholly owned subsidiary, entered into a profit-sharing agreement with BCPSC Holdings LLC, a wholly owned subsidiary of BCPA (the “Profit-Sharing Agreement”). MLCSC is entitled to 16.03% of BCPA’s
76
distributions from SCIM. Incremental management fees from BCIC are indirectly earned through the Profit-Sharing Agreement, and are excluded as management fee revenue, but recognized in other income.
(3)ML Management as the adviser to two CLOs, 2018-01 and 2019-01, earns senior and subordinated management fees on these vehicles, calculated on the outstanding collateral balance. CLO 2018-1 earns 0.25% senior and 0.35% subordinated fees, and 2019-1 earns 0.25% senior and 0.25% subordinated fees. These rates are fixed for the life of the transaction and are not subject to repricing.
(4)ML Management is the adviser to OCIF and earns management and incentive fees directly from this fund. Base management fees are earned at 1.25% of gross assets. Incentive fees are realized when the fund reaches a hurdle rate of return each quarter, based on the pre-incentive fee net investment income. When OCIF’s pre-incentive net investment income – i.e. interest income, dividend income and any other income accrued during the calendar quarter, less OCIF’s operating expenses for the quarter – exceeds the hurdle rate of return on OCIF’s adjusted capital of 1.5% (or 6% annualized), ML Management earns an incentive fee at 15% of the pre-incentive fee net investment income. All incentive fees recognized are considered realized as they are calculated and payable quarterly in arrears based on the pre-incentive fee net investment income for the immediately preceding calendar quarter. All recorded incentive fees have been subsequently received in cash.
(5)Mount Logan as the general partner accrues base management fees, calculated monthly, due and payable either monthly or quarterly in arrears at 0.125% of the net assets in the Ovation funds. Incentive fees, calculated monthly, due and payable quarterly in arrears, are calculated as 10% of pre-incentive fee distributable income. If pre-incentive fee distributable income amounts do not exceed 0% in any fiscal quarter, such shortfall (a “High Watermark Shortfall”) will carry forward to subsequent quarters. No incentive fees are payable to the general partner in any fiscal quarter in which a High Watermark Shortfall exists.
(6)Consists of several small, closed end private funds which are sub-advised by ML Management at 1% of net assets, as well as management fees earned from a portfolio of Nichol International Reinsurance (S.A.C), Ltd. (Nichol) (formerly known as Vista Life and Casualty Reinsurance Company) assets to which ML Management was appointed as the investment manager of, effective March 2025, at a rate of 1% on the average statutory book value of investments under management. Only fees which are crystallized and not subject to reversal are recognized and included. This also includes sub-advisory fees earned by ML Management from Yieldstreet Alternative Income Fund pursuant to the sub-advisory agreement entered into between ML Management and Willow Asset Management LLC that became effective on August 24, 2026.
(7)Management and incentive fees receivable are part of Other assets on the Condensed Consolidated Statement of Financial Position.
The fee rates described above are contractually fixed, however Mount Logan retains the right to voluntarily waive all or a portion of any management or incentive fee in circumstances where doing so would better align the economic interests of Mount Logan and the investors in a particular vehicle. Any such waiver would be approved by the applicable fund board.
Advisory and Transaction Fees
Mount Logan originates loan assets into the Ability investment portfolio, and also structures securitization transactions for third parties in exchange for a fee. The fees are structured and agreed on an individual deal basis and will vary from one transaction to another. Generally, Mount Logan will receive a fixed fee and bear no expenses, but from time to time may cover some transaction fees or split a fee with an origination partner.
Equity Investment Earning
Mount Logan owns a minority interest in SCIM which is accounted for as an investment in associate, and earns its share of the investee’s net income.
Expenses
Compensation and Benefits
Compensation and benefits expense consists of fixed salary, discretionary and non-discretionary bonuses, profit sharing expense associated with the performance fees earned and compensation expense associated with the vesting of non-cash equity-based awards. Mount Logan’s compensation arrangements with certain of its employees include non-cash equity-based awards, which are considered to be ‘performance-based incentives.’ The non-cash equity-based awards are granted subject to management’s discretion and approval by the Board of Directors. There are no clawback provisions associated with the non-cash equity-based awards; however, they are subject to a time-based vesting requirement and continued employment. To date, Mount Logan has not paid any profit sharing associated with performance fees. Because of these performance-based incentives, as Mount Logan’s net revenues increase, Mount Logan’s compensation costs rise. Mount Logan’s compensation costs also reflect the increased investment in people as Mount Logan continues to grow its AUM both organically and inorganically. During the fourth quarter of 2025, Mount Logan’s direct employees were transferred to BCPA. As such, as of September 30, 2026 Mount Logan has no direct employees. However, the compensation costs of BCPA employees who provide services to Mount Logan are attributed to Mount Logan based on AUM, and are now recorded within “Administration and servicing fees.”
Mount Logan grants equity awards to certain directors, officers, and service providers, consisting of Restricted Stock Units (“RSUs”) that generally vest and become exercisable in annual installments depending on the award terms. See Note 20. Equity based compensation to Mount Logan’s Condensed Consolidated Financial Statements for further discussion of equity-based compensation.
77
Administration and Servicing Fees
Under a Servicing Agreement with BCPA in place since November 2018, BCPA performs (or arranges for) Mount Logan's administrative functions, and Mount Logan reimburses BCPA for an allocable portion of the associated compensation and out-of-pocket costs. See Note 22. Related Parties in the Company’s Annual Report on Form 10-K for the fiscal year ended December 31, 2025 for the Servicing Agreement's terms, including renewal and termination provisions.
Mount Logan also earned a variable servicing fee, calculated quarterly, for administrative and reporting services provided to SCIM in respect of ACIF. However, After the ACIF Merger, the Company will no longer provide administrative services to SCIM in respect of ACIF and will no longer earn this variable servicing fee. See Note 22. Related Parties to our condensed consolidated financial statements for further detail on this arrangement.
Under a Staffing and Resource Agreement with BCPA in place since November 2025, BCPA makes personnel and other resources available to support Mount Logan's investment advisory operations, for a quarterly fee based on a percentage of fee-earning assets under management. See Note 22. Related Parties in the Company’s Annual Report on Form 10-K for the fiscal year ended December 31, 2025 for the agreement's term and termination provisions.
Other Expenses
The balance of our other expenses includes transaction costs, amortization and impairment of intangible assets, interest and other credit facility expenses, and general, administrative and other operating expenses. Transaction costs are related to any live, closed or dead deal costs. Amortization and impairment of intangible assets is related to purchased investment management agreements as discussed in Note 11. Goodwill and intangible assets to our condensed consolidated financial statements. Interest and credit facility expenses consists of interest and amortization of deferred financing costs related to our debt obligations as discussed in Note 12. Debt obligations to our condensed consolidated financial statements. General, administrative and other expenses includes professional fees and costs related to third party vendors, information technology, travel, and reporting and operations.
Investment and Other Income (Loss)
Net realized and change in unrealized gains (losses) from investment activities
Investment related gains (losses) primarily consist of (i) realized gains and losses on sales of investments, (ii) unrealized gains and losses on equity securities and investments, (iii) changes in the provision for credit losses, and (iv) minor foreign currency related gains and losses on Canadian payments.
Dividend and Interest Income
Dividend income consists primarily of distributions from equity investments, and interest income includes interest on the related party loan to SCIM as well as bank interest on cash held in money markets funds.
Other Income (Loss), Net
Other Income (loss) primarily consists of income from our profit sharing agreement over BCIC, and occasionally miscellaneous income.
Other
The balance of other income or loss includes gains or losses resulting from one-off events material enough to disclose separately.
Financial Measures under U.S. GAAP - Insurance Solutions
The following discussion of financial measures under U.S. GAAP is based on Mount Logan’s Insurance Solutions business, which is operated by Ability, as of September 30, 2026.
78
Revenues
Net Premiums
The net premiums for long duration contracts are negative as reinsurance ceded premiums exceeds direct and assumed premiums, primarily due to additional ceded premiums paid to transfer a substantial portion of risk under a reinsurance arrangement.
Product Charges
Product charges mainly include surrender charges on MYGA product which are earned when assessed against policyholder account balances during the period.
Net Investment Income
Net investment income primarily represents accrued interest and dividend income on Ability's fixed maturity and equity securities. See Note 2. Significant Accounting Policies in the Company’s Annual Report on Form 10-K for the fiscal year ended December 31, 2025 for the related recognition policy.
Net realized and change in unrealized gains (losses) from investment activities
Consists primarily of realized and unrealized gains and losses on investments and derivatives, and changes in the credit loss provision.
Net revenues of consolidated variable interest entities
Represents the net change in fair value, and related income and expenses, of Mount Logan's consolidated VIEs.
Net investment income (loss) on funds withheld
Net investment income (loss) on funds withheld reflects investment activity on assets supporting the Company's coinsurance with funds withheld arrangement with Front Street Re (covering the LTC business) and modified coinsurance arrangement with Nichol (covering the MYGA business). See Note 2. Significant Accounting Policies in the Company’s Annual Report on Form 10-K for the fiscal year ended December 31, 2025 related to Reinsurance for the terms of these arrangements and their balance sheet and income statement presentation.
Expenses
Interest sensitive contract benefits
Liabilities for the MYGA investment contracts equal the account value. See Note 15. Interest sensitive contract liabilities for further detail.
Net policy benefit and claims
Net policy benefit and claims reflects the change in future policy benefit reserves for the Company's LTC business, which are adjusted each period for updated cash flow assumptions with the effect recognized in current period earnings. See Critical Accounting Estimates — Insurance Solutions Segment below for the reserve methodology, including the cohort approach, the annual assumption review, and the locked-in discount rate.
Amortization of deferred acquisition costs
Costs directly related to the successful acquisition or renewal of MYGA contracts — primarily commissions — are capitalized as DAC and amortized straight-line over the expected contract term; all other costs are expensed as incurred.
79
Compensation and Benefits
This consists of fixed salary, discretionary and non-discretionary bonuses.
Interest expense
This includes interest expense on the debt obligations.
General, administrative and other
General, administrative and other expenses include normal operating expenses, integration, restructuring and other non-operating expenses.
Other Financial Measures under U.S. GAAP
Income Taxes
Mount Logan had no income tax expense in the third quarter of 2026 compared to $2.3 million income tax expense in the third quarter of 2025. Mount Logan’s income tax expense decreased in the nine months ended September 30, 2026 compared to the nine months ended September 30, 2025. For the nine months ended September 30, 2026, Mount Logan had no income tax expense while for the nine months ended September 30, 2025, Mount Logan incurred an income tax expense of $2.3 million. Income tax expense was $nil for the nine months ended September 30, 2026 as the statutory tax benefit arising from the pretax loss was fully offset by an increase in the valuation allowance against deferred tax assets and other items, as management determined that certain deferred tax assets generated in the period are not more-likely-than-not to be realized.
The Company considers its significant tax jurisdictions to include the United States and, before the acquisition of TURN, Canada. The Company remains subject to income tax examination in Canada for years after 2021 and in the U.S. federal jurisdiction for years after 2022. The Canada Revenue Agency is currently examining Canadian non-resident withholding taxes related to certain dividends paid by Legacy Mount Logan Capital Inc. during 2023 through 2025. No liability has been recorded in connection with the examination.
Managing Business Performance - Key Segment and Non-GAAP Performance Measures
Mount Logan believes that the presentation of Segment Income supplements a reader’s understanding of the economic operating performance of each of Mount Logan’s segments.
Segment Income is the key performance measure used by management in evaluating the performance of the Asset Management and Insurance Solutions segments. See Note 23. Segments to the Condensed Consolidated Financial Statements for more details regarding the components of Segment Income and management’s consideration of Segment Income. Mount Logan believes that Segment Income is helpful for an understanding of Mount Logan’s business and that investors should review the same supplemental financial measure that management uses to analyze Mount Logan’s segment performance. Segment Income is a measure of profitability and has certain limitations in that it does not take into account certain items included under U.S. GAAP. This measure supplements and should be considered in addition to and not in lieu of the results of operations discussed in “Overview of Results of Operations” that have been prepared in accordance with U.S. GAAP.
Fee Related Earnings and Spread Related Earnings
FRE is a component of Segment Income that is used to assess the performance of the Asset Management segment. FRE is the sum of (i) management fees, (ii) performance fees received from certain managed funds, (iii) advisory and transaction fees, (iv) equity investment earnings related to fee generating vehicles, (v) interest income attributable to investment management activity, and (vi) other fee-related income derived from the Company’s Profit-Sharing Agreement less (a) fee-related compensation, excluding equity-based compensation, and (b) other associated operating expenses, which excludes amortization of acquisition-related intangible assets and interest and other credit facility expenses.
FRE excludes non-fee generating revenues and expenses, transaction-related charges, equity-based compensation costs, the amortization and/or impairment of intangible assets, the operating results of VIEs that are included in the Condensed Consolidated Financial Statements, and any other non-recurring income and expenses. In addition, FRE excludes interest and other financing costs related to the Company not attributable to any specific segment, and corporate overhead expenses incurred to support the operations of the business rather than directly fee-related. Management
80
considers these types of costs corporate in nature, and are included only for reconciliation purposes to income (loss) before income tax (provision) benefit.
During the third quarter of 2026, the Company revised its definition of FRE to include a proportionate share of operating income on asset management investments held at fair value. Previously, these amounts were excluded from FRE. This change has been applied to all periods presented in the Segment Income table below, and prior period amounts have been recast to conform to the current presentations. The change had no impact on the Company’s condensed consolidated financial statements.
Spread Related Earnings (“SRE”) is a component of Segment Income that is used to assess the performance of the Insurance Solutions segment, excluding certain market volatility, which consists of investment gains (losses), other income and certain general, administrative & other expenses. For the Insurance Solutions segment, SRE equals the sum of (i) the net investment earnings on Insurance Solutions segment’s net invested assets (excluding investment earnings on funds held under reinsurance contracts and Modco agreement), less (ii) cost of funds (as described below), (iii) compensation and benefits, (iv) interest expense and (v) operating expenses.
Cost of funds includes liability costs associated with the crediting cost on MYGA liabilities as well as other liability costs. Other liability costs include DAC amortization, the cost of liabilities associated with LTC, net of reinsurance, which includes change in reserves, premiums, actual claim experience including related expenses and certain product charges related to MYGA.
Mount Logan uses FRE and SRE, which are non-GAAP measures, as measures of operating performance, not as measures of liquidity. These measures should not be considered in isolation or as a substitute for net income or other income data prepared in accordance with U.S. GAAP. The use of these measures without consideration of their related U.S. GAAP measures is not adequate due to the adjustments described above. See “Segment Analysis” for reconciliations of Segment Income, FRE and SRE to their most directly comparable measures under U.S. GAAP.
Results of Operations
Below is a discussion of Mount Logan’s Condensed Consolidated Statements of Operations for the three and nine months ended September 30, 2026 and 2025. For additional analysis of the factors that affected Mount Logan’s results at the segment level, see “Segment Analysis” below:
81
| Three months ended September 30, | Nine months ended September 30, | |||||||||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2025 | Change ($) | Change (%) | 2026 | 2025 | Change ($) | Change (%) | |||||||||||||||||||||||||||||||||||||||||||
| ($ in thousands) | ||||||||||||||||||||||||||||||||||||||||||||||||||
| REVENUES | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Management fees | $ | 1,874 | $ | 1,851 | $ | 23 | 1 | % | $ | 5,204 | $ | 7,900 | $ | (2,696) | -34 | % | ||||||||||||||||||||||||||||||||||
| Incentive fees | — | 431 | (431) | -100 | % | 813 | 1,208 | (395) | -33 | % | ||||||||||||||||||||||||||||||||||||||||
| Advisory and transaction fees, net | — | — | — | NM | 66 | — | 66 | NM | ||||||||||||||||||||||||||||||||||||||||||
| Equity investment earning | 144 | 481 | (337) | -70 | % | 659 | 805 | (146) | -18 | % | ||||||||||||||||||||||||||||||||||||||||
| 2,018 | 2,763 | (745) | -27 | % | 6,742 | 9,913 | (3,171) | -32 | % | |||||||||||||||||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net Premiums | (4,389) | (4,492) | 103 | -2 | % | (13,107) | (12,743) | (364) | 3 | % | ||||||||||||||||||||||||||||||||||||||||
| Product charges | 143 | 184 | (41) | -22 | % | 429 | 1,766 | (1,337) | -76 | % | ||||||||||||||||||||||||||||||||||||||||
| Net investment income | 17,181 | 16,992 | 189 | 1 | % | 49,126 | 48,621 | 505 | 1 | % | ||||||||||||||||||||||||||||||||||||||||
| Net realized and change in unrealized gains (losses) from investment activities | (8,694) | 3,775 | (12,469) | -330 | % | (13,224) | 9,085 | (22,309) | -246 | % | ||||||||||||||||||||||||||||||||||||||||
| Net revenues of consolidated variable interest entities | 1,701 | 2,797 | (1,096) | -39 | % | 3,565 | 9,979 | (6,414) | -64 | % | ||||||||||||||||||||||||||||||||||||||||
| Net investment income (loss) on funds withheld | 2,763 | (10,656) | 13,419 | -126 | % | (3,558) | (23,232) | 19,674 | -85 | % | ||||||||||||||||||||||||||||||||||||||||
| Other income | 2,128 | 76 | 2,052 | 2700 | % | 2,272 | 230 | 2,042 | 888 | % | ||||||||||||||||||||||||||||||||||||||||
| 10,833 | 8,676 | 2,157 | 25 | % | 25,503 | 33,706 | (8,203) | -24 | % | |||||||||||||||||||||||||||||||||||||||||
| Total revenues | $ | 12,851 | $ | 11,439 | $ | 1,412 | 12 | % | $ | 32,245 | $ | 43,619 | $ | (11,374) | -26 | % | ||||||||||||||||||||||||||||||||||
| EXPENSES | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Administration and servicing fees | $ | 3,764 | $ | 1,564 | $ | 2,200 | 141 | % | $ | 10,708 | $ | 4,613 | $ | 6,095 | 132 | % | ||||||||||||||||||||||||||||||||||
| Transaction costs | 17 | 3,185 | (3,168) | -99 | % | 51 | 10,483 | (10,432) | -100 | % | ||||||||||||||||||||||||||||||||||||||||
| Compensation and benefits | 512 | 4,161 | (3,649) | -88 | % | 938 | 8,377 | (7,439) | -89 | % | ||||||||||||||||||||||||||||||||||||||||
| Amortization and impairment of intangible assets | 512 | 8,272 | (7,760) | -94 | % | 1,630 | 11,071 | (9,441) | -85 | % | ||||||||||||||||||||||||||||||||||||||||
| Interest and other credit facility expenses | 2,185 | 1,970 | 215 | 11 | % | 6,362 | 5,876 | 486 | 8 | % | ||||||||||||||||||||||||||||||||||||||||
| General, administrative and other | 2,400 | 2,980 | (580) | -19 | % | 7,273 | 5,961 | 1,312 | 22 | % | ||||||||||||||||||||||||||||||||||||||||
| 9,390 | 22,132 | (12,742) | -58 | % | 26,962 | 46,381 | (19,419) | -42 | % | |||||||||||||||||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||||||||||||||||||||
Net policy benefit and claims (remeasurement gain on policy liabilities of $3,907 and $14,430 and $3,846 and $6,871 for the three and nine months ended September 30, 2026 and 2025, respectively) | (2,393) | (2,118) | (275) | 13 | % | (9,309) | (1,389) | (7,920) | 570 | % | ||||||||||||||||||||||||||||||||||||||||
| Interest sensitive contract benefits | 4,171 | 4,154 | 17 | — | % | 12,639 | 11,969 | 670 | 6 | % | ||||||||||||||||||||||||||||||||||||||||
| Amortization of deferred acquisition costs | 1,431 | 929 | 502 | 54 | % | 2,842 | 2,389 | 453 | 19 | % | ||||||||||||||||||||||||||||||||||||||||
| Compensation and benefits | — | 73 | (73) | -100 | % | — | 540 | (540) | -100 | % | ||||||||||||||||||||||||||||||||||||||||
| Interest expense | 300 | 408 | (108) | -26 | % | 1,018 | 1,143 | (125) | -11 | % | ||||||||||||||||||||||||||||||||||||||||
General, administrative and other (including related party amounts of $1,641 and $4,993 and $1,773 and $5,258 for the three and nine months ended September 30, 2026 and 2025, respectively) | 3,131 | 3,338 | (207) | -6 | % | 11,025 | 10,294 | 731 | 7 | % | ||||||||||||||||||||||||||||||||||||||||
| 6,640 | 6,784 | (144) | -2 | % | 18,215 | 24,946 | (6,731) | -27 | % | |||||||||||||||||||||||||||||||||||||||||
| Total expenses | $ | 16,030 | $ | 28,916 | $ | (12,886) | -45 | % | $ | 45,177 | $ | 71,327 | $ | (26,150) | -37 | % | ||||||||||||||||||||||||||||||||||
| Investment and other income (Loss) - Asset Management | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net realized and change in unrealized gains (losses) from investment activities | $ | (1,044) | $ | 1,342 | $ | (2,386) | -178 | % | $ | (2,362) | $ | 3,050 | $ | (5,412) | -177 | % | ||||||||||||||||||||||||||||||||||
| Dividend income | 9 | 22 | (13) | -59 | % | 74 | 89 | (15) | -17 | % | ||||||||||||||||||||||||||||||||||||||||
| Interest income | 282 | 275 | 7 | 3 | % | 967 | 814 | 153 | 19 | % | ||||||||||||||||||||||||||||||||||||||||
| Other income (loss), net | 207 | 251 | (44) | -18 | % | 853 | 556 | 297 | 53 | % | ||||||||||||||||||||||||||||||||||||||||
| Loss on extinguishment of debt | — | — | — | NM | (472) | — | (472) | NM | ||||||||||||||||||||||||||||||||||||||||||
| Gain on acquisition | — | 4,457 | (4,457) | -100 | % | — | 4,457 | (4,457) | -100 | % | ||||||||||||||||||||||||||||||||||||||||
| Total investment and other income (loss) | (546) | 6,347 | (6,893) | -109 | % | (940) | 8,966 | (9,906) | -110 | % | ||||||||||||||||||||||||||||||||||||||||
| Income (loss) before taxes | $ | (3,725) | $ | (11,130) | $ | 7,405 | -67 | % | $ | (13,872) | $ | (18,742) | $ | 4,870 | -26 | % | ||||||||||||||||||||||||||||||||||
| Income tax (expense) benefit — Asset Management | — | (2,306) | 2,306 | -100 | % | — | (2,333) | 2,333 | -100 | % | ||||||||||||||||||||||||||||||||||||||||
| Net income (loss) | $ | (3,725) | $ | (13,436) | $ | 9,711 | (72) | % | $ | (13,872) | $ | (21,075) | $ | 7,203 | (34) | % | ||||||||||||||||||||||||||||||||||
82
______________
Note: “NM” denotes not meaningful.
Three Months Ended September 30, 2026 Compared to Three Months Ended September 30, 2025
In this section, references to 2026 refer to the three months ended September 30, 2026 and references to 2025 refer to the three months ended September 30, 2025.
Asset Management Segment
Revenues
Revenues were $2.02 million in 2026, a decrease of $0.75 million from $2.76 million in 2025, driven by a decrease in incentive fees and equity investment earnings.
Management fees remained flat year over year. The decrease in fees stemmed from Logan Ridge due to the termination of the Logan Ridge investment management agreement ("IMA") following the July 2025 merger of Logan Ridge and Portman Ridge, as well as lower fees from Ovation funds, First Trust, and the CLO’s from continued wind-down or runoff of underlying vehicles. These decreases were offset by increased OCIF and Vista management fees as well as a third quarter 2026 addition of Yieldstreet fees.
Incentive fees decreased $0.4 million, due to third quarter 2026 OCIF incentive hurdles not being met.
Equity investment earnings decreased by $0.3 million due to lower net income results in SCIM mainly due to a decrease of management and performance fees.
Expenses
Expenses were $9.4 million in 2026, a decrease of $12.7 million from $22.1 million in 2025. The decrease was primarily driven by lower transaction costs, compensation and benefits costs, and amortization of intangible assets, partially offset by higher administration and servicing fees and interest and credit facility expenses.
Transaction costs decreased $3.2 million in 2026 given the 2025 transaction costs were related to Mount Logan’s merger with TURN, which closed in the third quarter of 2025. Refer to Note 3. Business combinations and Asset Acquisitions of the Condensed Consolidated Financial Statements for further detail. 2026 included no business acquisition costs and a net credit from reversals and refunds of other transaction costs.
Amortization and impairment of intangible assets decreased $7.8 million in 2026 as the Ovation IMA intangible asset is amortized on a basis that reflects the net asset value decline in the underlying fee-generating funds which are in wind-down. A larger value of assets were liquidated from the funds in 2025 than 2026, and thus amortization expense mirrors this.
Compensation and benefits costs decreased $3.6 million, primarily due to the acceleration of the RSUs vesting upon change in control related to Mount Logan’s merger with TURN and severance costs for several individuals.
Compensation and benefits decreased $3.6 million while administration and servicing fees increased $2.2 million primarily due to the Company’s employees being transferred to BCPA on October 1, 2025. This effectively resulted in direct compensation costs being exchanged for administrative and staffing fees charged by BCPA as servicing agent. As such, the decrease in on-going compensation costs related to these transferred employees was offset by the increase in administrative fees. The true compensation decrease is in relation to stock compensation expense. In 2025 under the 2019 RSU Plan, $2.1 million of compensation expense was recorded, compared to $0.4 million in 2026 for awards granted under the 2025 Plan. Refer to Note 20. Equity based compensation for further detail.
Administration and servicing fees increased $2.2 million in 2026 compared to 2025, primarily due to employees being transferred to BCPA on October 1, 2025 reducing direct compensation costs and increasing administrative and staffing fees. The increase in administrative and servicing fees is also driven by an increase in ACIF servicing costs in 2026 as compared to 2025.
General, administrative and other expenses decreased $0.6 million, primarily due to a reduction of the advisor fee expenses incurred in 2025 in relation to the Logan Ridge special dividend, partially offset by an increase in consulting and legal fees.
83
Interest and other credit facility expenses increased $0.2 million, as there was a net increase in debt obligations. The increase in debt from the issuance of exchange listed notes in January 2026 and the issuance of additional debenture units in April 2026 more than offset the partial paydown on the MLC US Holdings credit facility in January 2026 (refer to Note 12. Debt obligations of the condensed consolidated financial statements for further detail).
Investment and Other Income (Loss)
Total investment and other income was a loss of $0.5 million in 2026 compared with income of $6.3 million in 2025. The decrease of $6.9 million was primarily driven by the gain on TURN acquisition in 2025 and movements on assets and liabilities held at fair value.
Net realized and change in unrealized gains (losses) from investment activities decreased $2.4 million primarily driven by realized loss in relation to the derecognition of the SCIM Note and associated CECL allowance and valuation of the BCPL revenue share (refer to Note 12. Debt obligations of the Condensed Consolidated Financial Statements for further details regarding Mount Logan’s debt obligations).
Insurance Solutions Segment
Revenues
Revenues were $10.8 million in 2026, an increase of $2.2 million from $8.7 million in 2025. The increase was primarily driven by increases in net investment income (loss) on funds withheld, other income, net investment income, and net premiums. These increases were partially offset by decreases in net realized and change in unrealized gains (losses) from investment activities, net revenues of consolidated VIEs, and product charges.
Net investment income (loss) on funds withheld were a gain of $2.8 million in 2026, which reflects an increase of $13.4 million from a loss of ($10.7) million in 2025. This decrease was primarily driven by higher unrealized losses on the funds withheld assets due to higher yields.
Other income was 2.1 million in 2026, an increase of 2.1 million from 2025. This increase was primarily attributable to a recapture fee earned on the recapture of 50% of MYGA block liabilities related to SSL during the third quarter of 2026.
Net investment income was $17.2 million in 2026, an increase of $0.2 million from $17.0 million in 2025, primarily due to the reinvestment of proceeds, maturities, and paydowns into higher yielding assets due to the rate increases.
Net premiums were ($4.4) million in 2026, an increase of $0.1 million from ($4.5) million in 2025. The negative net premium reflects ceded premiums exceeding direct and assumed premiums within the LTC business, primarily due to additional ceded premium paid to transfer a substantial portion of LTC related risk under a reinsurance arrangement. The increase in net premiums was primarily driven by a decrease of $1.2 million in ceded premium compared to 2025, partially offset by a decrease of $1.1 million in direct and assumed premium related to the LTC business compared to 2025.
Net realized and change in unrealized gains (losses) from investment activities were losses of $8.7 million in 2026, a decrease of $12.5 million from gains of $3.8 million in 2025, primarily driven by higher unrealized losses resulting from interest rate movements as well as higher realized losses on the disposal of assets. This decrease was partially offset by the release of credit loss reserve following the disposal of non-performing assets.
Net revenues of consolidated VIEs were $1.7 million in 2026, a decrease of $1.1 million from $2.8 million in 2025, primarily driven by lower net investment income and higher realized losses in 2026.
Product charges were $0.1 million in 2026, which reflects a decrease of $0.1 million from $0.2 million in 2025, primarily driven by a decrease in early surrenders of MYGA policies in 2026 compared to 2025 which resulted in lower surrender charges/product charges paid by policyholders in 2026.
84
Expenses
Expenses were $6.6 million in 2026, a decrease of $0.1 million from $6.8 million in 2025. The decrease was driven by decreases in net policy benefit & claims, interest expense and general, administrative & other expenses. These decreases were partially offset by increase in DAC amortization.
Net policy benefit and claims were ($2.4) million in 2026, a decrease of $0.3 million from ($2.1) million in 2025, primarily driven by a favorable provision for credit losses on reinsurance recoverable.
Interest expense was $0.3 million in 2026, a decrease of $0.1 million from $0.4 million in 2025, primarily driven by repayment of surplus notes amounting to $5.3 million in 2026.
General, administrative & other expenses were $3.1 million in 2026, a decrease of $0.2 million from $3.3 million in 2025. This primarily reflects continued management efforts to improve operating efficiencies.
DAC amortization was $1.4 million in 2026, an increase of $0.5 million from $0.9 million in 2025, primarily due to write down of DAC related to the SSL block recapture. Partially offsetting this increase was lower early surrenders on existing MYGA policies compared to 2025. The higher level of surrenders in 2025 resulted in accelerated amortization of DAC associated with surrendered policies.
Income Tax (Provision) Benefit
Mount Logan recorded no income tax expense in 2026, a change from the small income tax benefit in 2025. Income tax expense was $nil in 2026 as the $0.8 million statutory tax benefit on the pre-tax loss of $3.7 million was offset primarily by an increase in the valuation allowance of $2.3 million, partially offset by a dividends received deduction of less than $0.1 million and nondeductible differences of $1.4 million, resulting in no net income tax expense or benefit for the period. The provision for income taxes includes federal, state, local and foreign income taxes, resulting in an effective income tax rate of 0.0% and (20.72)% for 2026 and 2025, respectively. For 2026, the most significant reconciling items between the U.S. federal statutory income tax rate of 21.0% and the effective income tax rate were nondeductible differences of $1.4 million and the increase in the valuation allowance against deferred tax assets of $2.3 million. See Note 18. Income taxes to the Condensed Consolidated Financial Statements for further details regarding Mount Logan’s income tax (provision) benefit.
Nine Months Ended September 30, 2026 Compared to Nine Months Ended September 30, 2025
In this section, references to 2026 refer to the nine months ended September 30, 2026, and references to 2025 refer to the nine months ended September 30, 2025.
Asset Management Segment
Revenues
Revenues were $6.7 million in 2026, a decrease of $3.2 million from $9.9 million in 2025. The decrease was driven by lower management and incentive fees, and equity investment earnings.
Management fees decreased $2.7 million primarily due to the termination of the Logan Ridge investment management agreement ("IMA") following the July 2025 merger of Logan Ridge and Portman Ridge, and lower fees from the Ovation funds, First Trust, the CLOs and OCIF. The declines in the Ovation, First Trust and CLO fee streams reflected continued wind-down or runoff of the underlying vehicles. OCIF management fees decreased primarily due to one-time out of period fee reimbursements in 2025, and higher contractual fee waivers in relation to expense caps on average net assets in 2026. These decreases were partially offset by an increase in fees from Vista under the Nichol IMA as the managed asset base increased after the mandate signed in March 2026 and added fees from the Yieldstreet sub-advisory agreement entered into and made effective in 2026.
Incentive fees decreased by $0.4 million, as lower incentive fee waivers in 2026 more than offset lower gross incentive fees. Gross incentive fees actually decreased due to third quarter 2026 OCIF incentive hurdles not being met.
Equity investment earnings decreased by $0.1 million due to unfavorable changes in net income from SCIM.
85
Advisory and transaction fees are a new, non-recurring fee stream that started in the fourth quarter of 2025. During 2026, the Company earned $0.1 million of origination fees related to assets originated into the Ability investment portfolio by ML Management.
Expenses
Expenses were $27.0 million in 2026, a decrease of $19.4 million from $46.4 million in 2025. The decrease was primarily driven by lower transaction costs and amortization of intangible assets, partially offset by higher general, administrative and other expenses, administration and servicing fees, and interest and other credit facility expenses.
Transaction costs decreased $10.4 million in 2026 given the 2025 transaction costs were related to Mount Logan’s merger with TURN, which closed in the third quarter of 2025. Refer to Note 3. Business combinations and Asset Acquisitions of the Condensed Consolidated Financial Statements for further details.
Amortization and impairment of intangible assets decreased $9.4 million in 2026 as the Ovation IMA intangible asset is amortized on a basis that reflects the net asset value decline in the underlying fee-generating funds which are in wind-down. A larger value of assets were liquidated from the funds in 2025 than 2026, and thus amortization expense mirrors this. The decrease in amortization and impairment of intangible assets is also driven by less impairment losses on the intangible asset associated with Logan Ridge during 2025, which is now the BCIC profit share. The BCIC profit share did not incur any impairment losses in 2026.
Compensation and benefits decreased $7.4 million while administration and servicing fees increased $6.1 million primarily due to the Company’s employees being transferred to BCPA on October 1, 2025. The related cost shift from direct compensation to fees under the Servicing Agreement and Staffing and Resource Agreement caused the offsetting movements in these line items. Refer to Note 22. Related parties for further detail on these agreements.
Taken together, compensation and benefits and administration and servicing fees were relatively unchanged. Outside of the cost shift, administration and servicing fees increased as the economic loss on the ACIF servicing arrangement was higher due to declining fees, and investment expenses were higher due to sub-investment management expenses related to the increased managed asset base on the Nichol IMA.
General, administrative and other expenses increased $1.3 million in 2026 primarily due to higher consulting and legal costs, and a one-time stock exchange tier entry listing fee.
Interest and other credit facility expenses increased by $0.5 million in 2026 as there was a net increase in debt obligations. The increase in debt from the issuance of exchange listed notes and additional debenture units outweighed the partial paydown on the MLC US Holdings credit facility (refer to Note 12. Debt obligations of the Condensed Consolidated Financial Statements for further details).
Investment and Other Income (Loss)
Total investment and other income decreased $9.9 million, primarily due to the gain in relation to the TURN acquisition in 2025, movements on assets and liabilities held at fair value, and the loss on extinguishment of debt from the partial paydown of the MLC US Holdings credit facility, partially offset by higher other income and interest income.
Net gains from investment activities decreased by $5.4 million into net losses, primarily due to unrealized gains recognized in 2025 on the seller note issued in relation to the Capitala acquisition, which was repaid at its final repayment amount of $0.1 million on October 31, 2025 (refer to Note 12. Debt obligations of the Condensed Consolidated Financial Statements for further details regarding Mount Logan’s debt obligations). There were no such gains in 2026, causing a negative year on year movement. There were also unrealized losses on equity investments contributing to current period losses, compared to unrealized gains on equity investments in 2025. In addition, a realized loss of $1.1 million in relation to the derecognition of the SCIM Note and associated CECL allowance in exchange for the BCPL profit share contributed to the decrease in gains on investment activities.
In proportion to the paydown on the MLC US Holdings credit facility, unamortized transaction costs that were capitalized were written-off as a loss on extinguishment of debt (refer to Note 12. Debt obligations of the Condensed Consolidated Financial Statements for further details regarding Mount Logan’s debt obligations).
86
Other income increased $0.3 million, primarily due to $0.6 million of income under the new Profit-Sharing Agreement entered in the third quarter of 2025 (refer to Note 22. Related parties of the Condensed Consolidated Financial Statements for further details regarding the Profit-Sharing Agreement). The increase was partially offset by the absence of approximately $0.3 million of tax refunds and other miscellaneous income recognized in 2025.
Interest income increased $0.2 million due to higher bank interest in line with the increase in cash balances.
Insurance Solutions Segment
Revenues
Revenues were $25.5 million in 2026, a decrease of $8.2 million from $33.7 million in 2025. The decrease was primarily driven by decreases in net realized and change in unrealized gains (losses) from investment activities, net revenues of consolidated VIEs, product charges, and net premiums. These decreases were partially offset by increases in net investment income (loss) on funds withheld, other income and net investment income.
Net realized and change in unrealized gains (losses) from investment activities were losses of $13.2 million in 2026, a decrease of $22.3 million from gains of $9.1 million in 2025. The decrease was primarily driven by higher unrealized losses resulting from interest rates movements and higher realized losses on sale of investments. This decrease was partially offset by the release of credit loss reserve following the disposal of non-performing assets in 2026.
Net revenues of consolidated VIEs were $3.6 million in 2026, a decrease of $6.4 million from $10.0 million in 2025, primarily driven by lower net investment income and higher realized losses from disposal of investments.
Product charges were $0.4 million in 2026, which reflects a decrease of $1.3 million from $1.8 million in 2025, primarily driven by a decrease in early surrenders of MYGA policies in 2026 compared to 2025 which resulted in lower surrender charges/product charges paid by policyholders in 2026.
Net premiums were ($13.1) million in 2026, a decrease of $0.4 million from ($12.7) million in 2025. The negative net premium reflects ceded premiums exceeding direct and assumed premiums within the LTC business, primarily due to additional ceded premiums paid to transfer a substantial portion of LTC related risk under a reinsurance arrangement. The decrease in net premiums was primarily driven by a decrease of $3.4 million in direct and assumed premiums compared to 2025, partially offset by a decrease of $3.0 million in ceded premium related to the LTC business compared to 2025.
Net investment income (loss) on funds withheld was a loss of ($3.6) million in 2026, an increase of $19.7 million from a loss of ($23.2) million in 2025. This increase was primarily driven by higher unrealized losses on the funds withheld assets due to higher yields and lower investment income in 2026.
Net investment income was $49.1 million in 2026, an increase of $0.5 million from $48.6 million in 2025, primarily driven by the reinvestment of proceeds, maturities, and paydowns into higher yielding assets due to the rate increases.
Expenses
Expenses were $18.2 million in 2026, a decrease of $6.7 million from $24.9 million in 2025. The decrease was primarily driven by a decrease in net policy benefit and claims and interest expense. This decrease was partially offset by increases in DAC amortization, general, administrative & other expenses and interest sensitive contract benefits.
Net policy benefits and claims were $(9.3) million in 2026, a decrease of $7.9 million from ($1.4) million in 2025, primarily driven by a favorable assumption update of $4.2 million, partially offset by an unfavorable experience adjustment of $2.8 million in the LTC business in 2026 while 2025 observed an unfavorable experience adjustment of $6.5 million on a net basis.
Interest expense was 1.0 million in 2026, a decrease of 0.1 million from 1.1 million in 2025, primarily driven by repayment of surplus notes amounting to $5.3 million in 2026.
DAC amortization was 2.8 million in 2026, an increase of 0.5 million from 2.4 million in 2025, primarily due to write down of DAC related to the SSL block recapture. Partially offsetting this increase was lower early surrenders on
87
existing MYGA policies compared to 2025. The higher level of surrenders in 2025 resulted in accelerated amortization of DAC associated with surrendered policies.
General, administrative and other expenses were $11.0 million in 2026, an increase of $0.7 million from $10.3 million in 2025. Expenses were higher in 2026, primarily due to upfront costs associated to support the transition to direct writing. The increase also reflects the inclusion of compensation and benefit costs within general, administrative and other expenses in 2026, which were presented separately in 2025. Following the transition to an administrative services model in October 2025, these costs are now incurred through administrative service fees, as the Company no longer has employees.
Interest sensitive contract benefits were $12.6 million in 2026, an increase of $0.7 million from $12.0 million in 2025, primarily driven by interest accretion on the MYGA block assumed from NSG in the second quarter of 2025.
Income Tax (Provision) Benefit
Mount Logan recorded no income tax expense in 2026, a decrease from the income tax expense of $2.3 million in 2025. Income tax expense was $nil in 2026 as the $2.9 million statutory tax benefit on the pre-tax loss of $13.9 million was offset primarily by an increase in the valuation allowance of $4.5 million, partially offset by a dividends received deduction of less than $0.1 million, resulting in no net income tax expense or benefit for the period. The provision for income taxes includes federal, state, local and foreign income taxes, resulting in an effective income tax rate of 0.0% and (12.45%) for 2026 and 2025, respectively. For 2026, the most significant reconciling items between the U.S. federal statutory income tax rate of 21.0% and the effective income tax rate was the increase in the valuation allowance against deferred tax assets of $4.5 million. See Note 18. Income taxes to the Condensed Consolidated Financial Statements for further details regarding Mount Logan’s income tax (provision) benefit.
Segment Analysis
Discussed below are Mount Logan’s results of operations for each of Mount Logan’s reportable segments. They represent the segment information available and utilized by management to assess performance and to allocate resources. See Note 23. Segments to Mount Logan’s Condensed Consolidated Financial Statements for more information regarding Mount Logan’s segment reporting.
We present certain performance measures for our reportable segments that are not calculated in accordance with U.S. GAAP, including FRE and SRE. Our management believes FRE and SRE are useful in evaluating our operating performance and by providing these non-GAAP measures, management intends to provide investors, securities analysts and other interested parties with a meaningful, consistent comparison of the Company’s profitability for the periods presented. These non-GAAP measures are not intended to be a substitute for U.S. GAAP financial measures and, as calculated, may not be comparable to other similarly titled measures of performance of other companies in other industries or within the same industry.
88
Asset Management
The following table presents FRE, the performance measure of Mount Logan’s Asset Management segment.
| Three months ended September 30, | Nine months ended September 30, | |||||||||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2025 | Change ($) | Change (%) | 2026 | 2025 | Change ($) | Change (%) | |||||||||||||||||||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Management fees | $ | 3,542 | $ | 3,471 | $ | 71 | 2 | % | $ | 10,300 | $ | 12,300 | $ | (2,000) | (16) | % | ||||||||||||||||||||||||||||||||||
| Incentive fees | — | 431 | (431) | (100) | % | 813 | 1,208 | (395) | (33) | % | ||||||||||||||||||||||||||||||||||||||||
| Advisory and transaction fees, net | — | — | — | NM | 66 | — | 66 | NM | ||||||||||||||||||||||||||||||||||||||||||
| Equity investment earnings | 144 | 481 | (337) | (70) | % | 659 | 805 | (146) | (18) | % | ||||||||||||||||||||||||||||||||||||||||
Interest income¹ | 274 | 275 | (1) | — | % | 813 | 814 | (1) | — | % | ||||||||||||||||||||||||||||||||||||||||
| Share of Operating Income on Investments held at FV | 1 | 144 | $ | (143) | (99.3) | % | 204 | 357 | (153) | (43) | % | |||||||||||||||||||||||||||||||||||||||
| Other fee-related income | 194 | 262 | $ | (68) | (26) | % | 836 | 262 | 574 | 219 | % | |||||||||||||||||||||||||||||||||||||||
| Fee-related compensation | (1,371) | (1,175) | (196) | 17 | % | (3,708) | (3,777) | 69 | (2) | % | ||||||||||||||||||||||||||||||||||||||||
| Other operating expenses: | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Administration and servicing fees | (1,489) | (896) | (593) | 66 | % | (4,346) | (2,834) | (1,512) | 53 | % | ||||||||||||||||||||||||||||||||||||||||
| General, administrative and other | (823) | (326) | (497) | 152 | % | (2,359) | (1,764) | (595) | 34 | % | ||||||||||||||||||||||||||||||||||||||||
| Fee related earnings | $ | 472 | $ | 2,667 | $ | (2,195) | (82) | % | $ | 3,278 | $ | 7,371 | $ | (4,093) | (56) | % | ||||||||||||||||||||||||||||||||||
______________
Note: “NM” denotes not meaningful.
(1)Represents interest income on a loan asset related to a fee generating vehicle.
Three Months Ended September 30, 2026 Compared to Three Months Ended September 30, 2025
In this section, references to 2026 refer to the three months ended September 30, 2026, and references to 2025 refer to the three months ended September 30, 2025.
FRE was $0.5 million in 2026, a decrease of $2.2 million compared to $2.7 million in 2025. The decrease was primarily attributable to lower incentive fees, lower equity investment earnings, and higher administration and servicing fees and general and administrative costs.
Other fee-related income represents the income earned from the new profit sharing agreement entered into in July 2025 between Mount Logan and the owner of SCIM. This fee represents 16.03% of the distributions received by the parent entity of SCIM via the profit sharing agreement.
Management fees, incentive fees, equity investment earnings, and administration and servicing fees moved for the same reasons discussed above under Results of Operations — Asset Management Segment. Differences between the dollar amounts presented there and the FRE components above reflect the FRE adjustments described under Managing Business Performance — Key Segment and Non-GAAP Performance Measures.
Nine Months Ended September 30, 2026 Compared to Nine Months Ended September 30, 2025
In this section, references to 2026 refer to the nine months ended September 30, 2026, and references to 2025 refer to the nine months ended September 30, 2025.
FRE was $3.3 million in 2026, a decrease of $4.1 million compared to $7.4 million in 2025. This decrease was primarily attributable to the decline in management and incentive fees, as well as an increase in both administrative and servicing fees and general and administrative fees.
Management fees and administration and servicing fees moved for the same reasons discussed above under Results of Operations — Asset Management Segment for the nine months ended September 30, 2026. The different dollar amounts reflect the FRE adjustments — including the reclassification of compensation costs to administrative fees
89
following the October 2025 employee transfer to BCPA — described under Managing Business Performance — Key Segment and Non-GAAP Performance Measures.
The decrease to FRE was partially offset by the following:
Other fee-related income increased $0.6 million from the new Profit-Sharing Agreement entered into in July 2025 between Mount Logan and the owner of SCIM. This fee represents 16.03% of the distributions received by the parent entity of SCIM, which is effectively the Company’s net incremental share in BCIC’s management and incentive fees.
Fee-related compensation decreased slightly in-line with underlying vehicle performance, consistent with decreasing fee revenue.
New advisory and transaction fees were earned in 2026 compared to 2025, as the Company started earning origination fees related to assets originated into the Ability investment portfolio by ML Management.
Asset Management Operating Metrics
Assets Under Management
The following presents Mount Logan’s total AUM by vehicle (in millions):
| Three months ended September 30, 2026 | ||||||||||||||||||||||||||||||||||||||||||||
| (in millions) | Ability (including consolidated VIEs) 1 | BDCs 2 | CLOs 3 | Interval Funds 4 | Ovation Funds | Other 5 | Total | |||||||||||||||||||||||||||||||||||||
Change in Total AUM6 | ||||||||||||||||||||||||||||||||||||||||||||
| Beginning of Period | $ | 953 | $ | 175 | $ | 375 | $ | 373 | $ | 92 | $ | 39 | $ | 2,007 | ||||||||||||||||||||||||||||||
| Inflows | 1 | 71 | — | 154 | — | — | 226 | |||||||||||||||||||||||||||||||||||||
| Outflows | (74) | (92) | — | (81) | (14) | (28) | (289) | |||||||||||||||||||||||||||||||||||||
| Net Flows | (73) | (21) | — | 73 | (14) | (28) | (63) | |||||||||||||||||||||||||||||||||||||
| Realizations | — | (3) | (15) | (11) | (1) | (4) | (34) | |||||||||||||||||||||||||||||||||||||
| Investment Income | — | 1 | — | — | — | — | 1 | |||||||||||||||||||||||||||||||||||||
| Market activity and other | (17) | 82 | (9) | (168) | 11 | 5 | (96) | |||||||||||||||||||||||||||||||||||||
Inter-vehicle eliminations7 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| End of Period | $ | 863 | $ | 234 | $ | 351 | $ | 267 | $ | 88 | $ | 12 | $ | 1,815 | ||||||||||||||||||||||||||||||
90
| Three months ended September 30, 2025 | ||||||||||||||||||||||||||||||||||||||||||||
| (in millions) | Ability (including consolidated VIEs) 1 | BDCs 2 | CLOs 3 | Interval Funds 4 | Ovation Funds | Other 5 | Total | |||||||||||||||||||||||||||||||||||||
Change in Total AUM6 | ||||||||||||||||||||||||||||||||||||||||||||
| Beginning of Period | $ | 827 | $ | 294 | $ | 491 | $ | 430 | $ | 113 | $ | 111 | $ | 2,266 | ||||||||||||||||||||||||||||||
| Inflows | — | 5 | — | 24 | — | — | 29 | |||||||||||||||||||||||||||||||||||||
| Outflows | — | (20) | — | (47) | (5) | (29) | (101) | |||||||||||||||||||||||||||||||||||||
| Net Flows | — | (15) | — | (23) | (5) | (29) | (72) | |||||||||||||||||||||||||||||||||||||
| Realizations | — | (4) | (16) | (7) | (1) | — | (28) | |||||||||||||||||||||||||||||||||||||
| Market activity and other | 9 | (66) | (1) | — | 2 | 2 | (54) | |||||||||||||||||||||||||||||||||||||
Inter-vehicle eliminations7 | — | — | — | (4) | — | — | (4) | |||||||||||||||||||||||||||||||||||||
| End of Period | $ | 836 | $ | 209 | $ | 474 | $ | 396 | $ | 109 | $ | 84 | $ | 2,108 | ||||||||||||||||||||||||||||||
| Nine month ended September 30, 2026 | ||||||||||||||||||||||||||||||||||||||||||||
| (in millions) | Ability (including consolidated VIEs) 1 | BDCs 2 | CLOs 3 | Interval Funds 4 | Ovation Funds | Other 5 | Total | |||||||||||||||||||||||||||||||||||||
Change in Total AUM6 | ||||||||||||||||||||||||||||||||||||||||||||
| Beginning of Period | $ | 873 | $ | 194 | $ | 441 | $ | 411 | $ | 109 | $ | 69 | $ | 2,097 | ||||||||||||||||||||||||||||||
| Inflows | 121 | 96 | — | 228 | — | — | 445 | |||||||||||||||||||||||||||||||||||||
| Outflows | (104) | (188) | — | (150) | (33) | (48) | (523) | |||||||||||||||||||||||||||||||||||||
| Net Flows | 17 | (92) | — | 78 | (33) | (48) | (78) | |||||||||||||||||||||||||||||||||||||
| Realizations | — | (13) | (65) | (24) | (5) | (7) | (114) | |||||||||||||||||||||||||||||||||||||
| Investment Income | — | 2 | — | — | — | — | 2 | |||||||||||||||||||||||||||||||||||||
| Market activity and other | (27) | 143 | (25) | (198) | 17 | (2) | (92) | |||||||||||||||||||||||||||||||||||||
Inter-vehicle eliminations7 | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| End of Period | $ | 863 | $ | 234 | $ | 351 | $ | 267 | $ | 88 | $ | 12 | $ | 1,815 | ||||||||||||||||||||||||||||||
91
| Nine month ended September 30, 2025 | ||||||||||||||||||||||||||||||||||||||||||||
| (in millions) | Ability (including consolidated VIEs) 1 | BDCs 2 | CLOs 3 | Interval Funds 4 | Ovation Funds | Other 5 | Total | |||||||||||||||||||||||||||||||||||||
Change in Total AUM6 | ||||||||||||||||||||||||||||||||||||||||||||
| Beginning of Period | $ | 746 | $ | 306 | $ | 564 | $ | 410 | $ | 212 | $ | 111 | $ | 2,349 | ||||||||||||||||||||||||||||||
| Inflows | 97 | 5 | — | 90 | — | 8 | 200 | |||||||||||||||||||||||||||||||||||||
| Outflows | (26) | (23) | — | (99) | (107) | (46) | (301) | |||||||||||||||||||||||||||||||||||||
| Net Flows | 71 | (18) | — | (9) | (107) | (38) | (101) | |||||||||||||||||||||||||||||||||||||
| Realizations | — | (6) | (79) | (21) | (10) | (1) | (117) | |||||||||||||||||||||||||||||||||||||
| Market activity and other | 19 | (73) | (11) | 20 | 14 | 12 | (19) | |||||||||||||||||||||||||||||||||||||
Inter-vehicle eliminations7 | — | — | — | (4) | — | — | (4) | |||||||||||||||||||||||||||||||||||||
| End of Period | $ | 836 | $ | 209 | $ | 474 | $ | 396 | $ | 109 | $ | 84 | $ | 2,108 | ||||||||||||||||||||||||||||||
_____________
(1)Ability’s AUM excludes assets held under the funds withheld and Modco agreements, and includes a portion of the Nichol assets to which ML Management was appointed as the investment manager of, effective March 2025.
(2)Mount Logan owns a 24.99% interest in SCIM, which is the manager of BCIC. Under the Profit-Sharing Agreement with BCPSC, the majority owner of SCIM, Mount Logan receives 16.03% of their SCIM distribution. BCIC is the new merged entity of Portman Ridge and Logan Ridge, which closed on July 15, 2025. Prior to Logan Ridge merging into Portman, ML Management was the manager of Logan Ridge.
(3)ML Management is the adviser to two CLOs 2018-01 and 2019-01.
(4)ML Management is the adviser to OCIF.
(5)Consists of several small closed end private funds and AUM which is sub-advised by ML Management.
(6)Inflows generally represent new capital which includes capital contributions, subscriptions, dividend reinvestments, draw downs on leverage facilities, and new MYGA flows and managed reinsurance assets added at Ability. Outflows include redemptions, pay downs on leverage facilities, and claims and benefits payments at Ability. Realizations represent distributions of realized income, repurchases of capital, and repayments on CLO notes. Market activity and other generally represents realized and unrealized gains (losses) on investments and other changes in AUM.
(7)Represents ACIF’s investment in OCIF. Ability’s investment in BCIC is $0.1 million.
(8)Several of the above funds are still subject to their reporting period audits or reviews, thus the AUM quoted above represents management’s best estimate of AUM as of September 30, 2026, but may be subject to change.
Three Months Ended September 30, 2026
Total AUM was $1.8 billion at September 30, 2026, a $0.2 billion decrease from $2.0 billion at June 30, 2026. The decrease is attributable to decreases in AUM across all vehicles except for the BDCs. Ability AUM decreased due to cash payments to service claims. Interval funds AUM decreased due to the ACIF Merger pursuant to which the Company is no longer entitled to the full economics of ACIF. CLO assets will continue to decline given both are in post reinvestment period and continue to harvest their assets. Ovation funds’ AUM will continue to decline pursuant to their wind down. The decrease in AUM is partially offset by an increase in AUM attributable to BDCs. BDCs AUM increased due to ACIF Merger in which the Company is entitled to receive the BCPL revenue share representing 29.88% of BCPL’s AUM.
Nine Months Ended September 30, 2026
Total AUM was $1.8 billion at September 30, 2026, a $282 million decrease from December 31, 2025. The decrease was driven by decreases in AUM across Ability, CLOs, Interval funds, Ovation funds, and small closed end private funds. Interval funds decreased due to ACIF merging with BCPL pursuant to which ACIF’s AUM is no longer attributable to the Company. The loss of the ACIF AUM is partially offset by the increase in the AUM of SOFIX due to the acquisition of the Yieldstreet Alternative Income Fund. We expect CLO assets will continue to decline given both are in post reinvestment period and continue to harvest their assets. We also expect Ovation funds’ AUM will also continue to decline pursuant to their wind down. Ability AUM decreased due to cash payments to service claims. the BDCs AUM increased pursuant to the ACIF Merger in which the Company becomes entitled to the BCPL revenue share representing 29.88% of BCPL’s AUM.
92
Insurance Solutions
During the third quarter of 2026, the Company revised its definition of SRE to exclude net realized gains (losses) on the sale of investments from net investment earnings on Insurance Solutions segment’s net invested assets. Previously these amounts were included in SRE. This change has been applied to all periods presented in the Segment Income table below, and prior period amounts have been recast to conform to the current presentations. The change had no impact on the Company’s condensed consolidated financials statements.
The following table presents Spread Related Earnings, the performance measure of Mount Logan’s Insurance Solutions segment:
| Three months ended September 30, | Nine months ended September 30, | |||||||||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2025 | Change ($) | Change (%) | 2026 | 2025 | Change ($) | Change (%) | |||||||||||||||||||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net investment income | $ | 12,535 | $ | 12,404 | $ | 131 | 1 | % | $ | 36,703 | $ | 37,094 | $ | (391) | (1) | % | ||||||||||||||||||||||||||||||||||
| Cost of funds | (6,721) | (7,273) | 552 | (8) | % | (18,115) | (23,946) | 5,831 | (24) | % | ||||||||||||||||||||||||||||||||||||||||
| Compensation and benefits | — | (73) | 73 | (100) | % | — | (540) | 540 | (100) | % | ||||||||||||||||||||||||||||||||||||||||
| Interest expense | (300) | (408) | 108 | (26) | % | (1,018) | (1,143) | 125 | (11) | % | ||||||||||||||||||||||||||||||||||||||||
| General, administrative and other | (2,807) | (3,153) | 346 | (11) | % | (9,330) | (9,340) | 10 | — | % | ||||||||||||||||||||||||||||||||||||||||
| Spread related earnings | $ | 2,707 | $ | 1,497 | $ | 1,210 | 81 | % | $ | 8,240 | $ | 2,125 | $ | 6,115 | 288 | % | ||||||||||||||||||||||||||||||||||
Three Months Ended September 30, 2026 Compared to Three Months Ended September 30, 2025
In this section, references to 2026 refer to the three months ended September 30, 2026, and references to 2025 refer to the three months ended September 30, 2025.
Spread Related Earnings
SRE was $2.7 million in 2026, an increase of $1.2 million, compared to $1.5 million in 2025. The increase in SRE was primarily driven by lower cost of funds, lower expenses, and higher investment income.
Cost of funds decreased $0.6 million, reflecting the combined effect of the changes in Net policy benefit and claims, DAC amortization, and Interest sensitive contract benefits discussed above under Results of Operations — Insurance Solutions Segment.
Expenses decreased $0.5 million, reflecting the effect of changes in expenses, including general, administrative, and other, interest, and compensation and benefits discussed above under Results of Operations — Insurance Solutions Segment.
Net investment income increased by $0.1 million, primarily driven by the effect of changes in net investment income discussed above under Results of Operations — Insurance Solutions Segment.
Net Investment Spread
| Three months ended September 30, | ||||||||||||||||||||
| 2026 | 2025 | Change | ||||||||||||||||||
| Net investment income | 1.72% | 1.60% | 12bps | |||||||||||||||||
| Cost of funds¹ | (1.46)% | (1.43)% | -3bps | |||||||||||||||||
| Net Investment spread | 0.26% | 0.17% | 9bps | |||||||||||||||||
_______________
(1)Excludes changes in future policy benefits liabilities of LTC line of business, to calculate net investment spread, which result from changes in actuarial assumptions and future cash flow projections.
93
Net investment spread was 0.26% in 2026, an increase of 9 basis points compared to 0.17% in 2025, primarily driven by higher net investment income and lower cost of funds, partially offset by a lower average net invested asset balance in 2026 compared to 2025.
Net investment income percent represents the percent of net investment income over average net invested assets. Net investment income was 1.72% in 2026, an increase of 12 basis points compared to 1.60% in 2025, primarily driven by the reinvestment of proceeds, maturities, and paydowns into higher yielding assets in 2026, partially offset by a lower average net invested assets due to the SSL recapture (including cash on hand) in 2026 compared to 2025.
Cost of funds percent represents the percent of cost of funds over average net invested assets. Cost of funds were lower in 2026 compared to 2025 primarily driven by the effect of changes in premiums, net policy benefits, and amortization of DAC, partially offset by an increase in interest sensitive contract benefits discussed above under Results of Operations — Insurance Solutions Segment,
Net invested assets represent investments that directly back the Insurance Solutions segment’s net reserve liabilities as well as surplus assets. Net invested assets for Insurance Solutions segment includes (a) total investments on the Condensed Consolidated Statements of Financial Position, with available-for-sale securities, trading securities and mortgage loans at cost or amortized cost, (b) cash and cash equivalents and restricted cash, (c) investments in related parties, (d) accrued investment income, (e) VIE assets, and (f) net investment payables and receivables. Net invested assets exclude the investment assets under funds withheld arrangement with FSR and assets under Modco agreement with Nichol. Net invested assets also exclude mark-to-market adjustment (net unrealized gains (losses)) including provision for credit losses recognized in Condensed Consolidated Statement of Operations during the year.
Nine Months Ended September 30, 2026 Compared to Nine Months Ended September 30, 2025
In this section, references to 2026 refer to the nine months ended September 30, 2026, and references to 2025 refer to the nine months ended September 30, 2025.
Spread Related Earnings
SRE was $8.2 million in 2026, an increase of $6.1 million, compared to $2.1 million in 2025. The increase in SRE was primarily driven by lower cost of funds, lower general, administrative and other expenses including compensation and benefits and interest cost, partially offset by lower net investment income.
Cost of funds decreased $5.8 million, reflecting the combined effect of the changes in Net policy benefit and claims, DAC amortization, and Interest sensitive contract benefits discussed above under Results of Operations — Insurance Solutions Segment for the nine months ended September 30, 2026.
Net investment income decreased by $0.4 million. The decrease was primarily driven by lower investment income from VIEs, partially offset by an increase in net investment income compared to 2025.
Expenses decreased $0.7 million, reflecting the effect of changes in expenses, including general, administrative, and other, interest, and compensation and benefits discussed above under Results of Operations — Insurance Solutions Segment.
Net Investment Spread
| Nine months ended September 30, | ||||||||||||||||||||
| 2026 | 2025 | Change | ||||||||||||||||||
| Net investment income | 4.99% | 4.87% | 12bps | |||||||||||||||||
| Cost of funds¹ | (4.42)% | (4.04)% | -38bps | |||||||||||||||||
| Net Investment spread | 0.57% | 0.83% | -26bps | |||||||||||||||||
_______________
(1)Excludes changes in future policy benefits liabilities of LTC line of business, to calculate net investment spread, which result from changes in actuarial assumptions and future cash flow projections.
94
Net investment spread was 0.57% in 2026, a decrease of 26 basis points compared to 0.83% in 2025, primarily driven by higher cost of funds and lower net investment income, partially offset by a lower average net invested asset balance in 2026 compared to 2025.
Net investment income percent represents the percent of net investment income over average net invested assets. Net investment income was 4.99% in 2026, an increase of 12 basis points compared to 4.87% in 2025, primarily driven by a lower average net invested assets (including cash on hand) and higher net investment income, partially offset by lower investment income from VIEs compared to 2025.
Cost of funds percent represents the percent of cost of funds over average net invested assets. Cost of funds were higher in 2026 compared to 2025. primarily driven by an increase in interest sensitive contract benefits from the assumption of the NSG MYGA block in the second quarter of 2025, partially offset by lower DAC amortization due to lower early surrenders related to MYGA policies in 2026.
Investment Portfolio and Net Investment Spread
Ability had total investments, including related parties and consolidated VIEs, of $991 million and $1,054 million as of September 30, 2026, and September 30, 2025, respectively. Total investments have decreased by 6% compared to 2025, which is primarily driven by the SSL recapture. Ability’s investment strategy seeks to achieve sustainable risk-adjusted returns through the disciplined management of its investment portfolio against its duration of liabilities. The investment strategies focus primarily on a buy and hold asset allocation strategy that may be adjusted periodically in response to changing market conditions and the nature of Ability’s liability profile. Ability takes advantage of its generally persistent liability profile by identifying investment opportunities with an emphasis on earning incremental yield by taking measured liquidity and complexity risk rather than assuming incremental credit risk. Ability has selected a diverse array of primarily high-grade fixed income assets including corporate bonds, structured securities and commercial real estate loans, among others. Ability also maintains holdings in floating rate and less rate-sensitive instruments, including CLOs, non-agency RMBS and various types of structured products, both as an expression of its macroeconomic views as well as to capture incremental returns versus fixed rate instruments. Depending on its market outlook, Ability will use financial hedges to increase or reduce its exposure to various macroeconomic factors, including interest rate, foreign currency exchange rate, and / or performance of market indices. In addition to its fixed income portfolio, Ability opportunistically allocates to alternative investments where it primarily focuses on fixed income-like, cash flow-based investments.
Segment Income
Segment Income is a measure of profitability and has certain limitations in that it does not take into account certain items included under U.S. GAAP. Segment Income is the sum of (i) FRE and (ii) SRE. The following presents a reconciliation of Net Income (loss) attributable to Mount Logan common shareholders to Segment Income:
95
| Three months ended September 30, | Nine months ended September 30, | |||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||
| Net income (loss) | $ | (3,725) | $ | (13,436) | $ | (13,872) | $ | (21,075) | ||||||||||||||||||
| Income tax (expense) benefit — Asset Management | — | (2,306) | — | (2,333) | ||||||||||||||||||||||
| Income (loss) before taxes | (3,725) | (11,130) | (13,872) | (18,742) | ||||||||||||||||||||||
| Asset Management Adjustments: | ||||||||||||||||||||||||||
| Intersegment management fee eliminations | 1,668 | 1,620 | 5,096 | 4,400 | ||||||||||||||||||||||
Administration and servicing fees 1 | 904 | 668 | 2,654 | 1,779 | ||||||||||||||||||||||
| Transaction costs | 17 | 3,185 | 51 | 10,483 | ||||||||||||||||||||||
Compensation and benefits 1 | 90 | 861 | 436 | 1,802 | ||||||||||||||||||||||
| Equity-based compensation | 422 | 1,240 | 502 | 1,632 | ||||||||||||||||||||||
| Amortization and impairment of intangible assets | 512 | 8,272 | 1,630 | 11,071 | ||||||||||||||||||||||
| Interest and other credit facility expenses | 2,185 | 1,970 | 6,362 | 5,876 | ||||||||||||||||||||||
General, administrative and other 1 | 1,577 | 2,654 | 4,915 | 4,197 | ||||||||||||||||||||||
| Net realized and change in unrealized gains (losses) from investment activities | 1,044 | (1,342) | 2,362 | (3,050) | ||||||||||||||||||||||
| Dividend income | (9) | (22) | (74) | (89) | ||||||||||||||||||||||
| Interest income - bank interest | (8) | — | (154) | — | ||||||||||||||||||||||
| Other income (loss), net | (13) | 11 | (17) | (294) | ||||||||||||||||||||||
| Loss on extinguishment of debt | — | — | 472 | — | ||||||||||||||||||||||
| Gain on acquisition | — | (4,457) | — | (4,457) | ||||||||||||||||||||||
| Share of Operating Income on Investments held at FV | 1 | 144 | 204 | 357 | ||||||||||||||||||||||
| Insurance Solutions Adjustments: | — | — | ||||||||||||||||||||||||
| Equity-based compensation | — | 885 | — | 1,166 | ||||||||||||||||||||||
| Net unrealized gains (losses) from investment activities | 1,252 | 1,116 | 5,890 | (2,959) | ||||||||||||||||||||||
| Other income | (2,128) | (76) | (2,272) | (230) | ||||||||||||||||||||||
| Intersegment management fee eliminations | (1,668) | (1,620) | (5,096) | (4,400) | ||||||||||||||||||||||
General, administrative and other 2 | 324 | 185 | 1,695 | 954 | ||||||||||||||||||||||
| Write down of DAC due to recapture | 734 | — | 734 | — | ||||||||||||||||||||||
| Segment Income | 3,179 | 4,164 | 11,518 | 9,496 | ||||||||||||||||||||||
_______________
(1)Represents corporate overhead allocated to each segment.
(2)Represents costs incurred by the insurance segment for purposes of U.S. GAAP reporting including one-time upfront cost associated with the new initiatives but not the day-to-day operations of the insurance company.
Liquidity and Capital Resources
Overview
Mount Logan primarily derives revenues and cash flows from the assets we manage and the retirement savings products we issue and reinsure. Based on management’s experience, we believe that our current liquidity position, together with the cash generated from revenues, will be sufficient to meet our anticipated expenses and other working capital needs for at least the next 12 months. For the longer-term liquidity needs of the Asset Management business, we expect to continue to fund the Asset Management business’s operations through management fees and incentive fees received. The principal sources of liquidity for the Insurance Solutions segment, in the ordinary course of business, are operating cash flows and holdings of cash, cash equivalents and other readily marketable assets. At September 30, 2026, we had $60.3 million of unrestricted cash and cash equivalents.
Primary Uses of Cash
Over the next 12 months, we expect our primary liquidity needs will be to:
•support the future growth of our businesses through strategic corporate investments;
96
•pay our operating expenses, including, general, administrative, and other expenses;
•make payments to policyholders for surrenders, withdrawals and payout benefits;
•make interest and principal payments on funding agreements;
•make share repurchases through its authorized share repurchase program;
•pay taxes; and
•pay cash dividends.
Over the long term, we believe we will be able to (i) grow our AUM and generate positive investment performance in the funds we manage, which we expect will allow us to grow our management fees and incentive fees and (ii) grow the investment portfolio of insurance solutions services, in each case in amounts sufficient to cover our long-term liquidity requirements, which may include:
•supporting the future growth of our businesses;
•creating new or enhancing existing products and investment platforms;
•making payments to policyholders;
•pursuing new strategic corporate investment opportunities; and
•paying interest and principal on our financing arrangements.
Cash Flow Analysis
The section below discusses in more detail our primary sources and uses of cash and the primary drivers of cash flows within our Condensed Consolidated Statements of Cash Flows:
| Nine months ended September 30, | ||||||||||||||
| (in thousands) | 2026 | 2025 | ||||||||||||
| Operating activities | $ | (35,553) | $ | (25,640) | ||||||||||
| Investing activities | 5,254 | 71,018 | ||||||||||||
| Financing activities | (33,843) | 14,734 | ||||||||||||
| Cash, cash equivalents and restricted cash, and cash and cash equivalents of consolidated VIEs, end of period | $ | 79,583 | $ | 161,815 | ||||||||||
Operating Activities
Our operating activities support our Asset Management and Insurance Solutions businesses. The primary sources of cash within operating activities include: (a) management, performance and advisory and transaction fees, (b) insurance premiums, (c) reinsurance recoverable, (d) proceeds from sales of investments from Mount Logan’s consolidated VIEs and (e) cash interest received from investments. The primary uses of cash within operating activities include: (a) investment purchases from Mount Logan’s consolidated VIEs (b) compensation and non-compensation related expenses through servicing fees, (c) benefit payments, (d) cash interest paid on debt obligations and (e) other operating expenses. A significant use of cash within operating activities pertain to future policy benefits incurred in the LTC business. As the LTC business is in run-off, this activity is expected to have less of an impact to cash outflow over time.
•During the nine months ended September 30, 2026 and September 30, 2025, cash used in operating activities reflects Asset Management expense reimbursements to BCPA under the Servicing Agreement for third-party costs incurred, direct vendor payments, interest expense on borrowings, compensation and quarterly tax payments. Cash used in operating activities also reflects net cash benefit payments associated with the LTC business, purchases of investments by consolidated VIEs, policy
97
acquisition costs, and other operating expenses within Insurance Solutions. These outflows were partially offset by inflows of management fees, realized incentive fees, and distributions from SCIM within Asset Management, and investment income, settlement of reinsurance recoverables related to the LTC business and proceeds from the sale of investments held by consolidated VIEs within Insurance Solutions.
Investing Activities
Our investing activities support the growth of our business. The primary sources of cash within investing activities include sales, maturities and repayments of investments. The primary uses of cash within investing activities include: (a) acquisition of consolidated business(es) and (b) purchases and acquisitions of new investments. The cash flow activities related to MYGA products is split across investing activities and financing activities. As Mount Logan assumes or directly write new MYGA products, the receipt of cash is reported in financing activities and the corresponding purchase of securities is reported in investing activities. As a result, as the MYGA portfolio grows, these cash flow activities while related, will continue to present an inflow to financing activities and an outflow to investing activities.
•During the nine months ended September 30, 2026, cash provided by investing activities primarily reflects sales, maturities and repayment of investments, partially offset by the purchase of investments, mainly available-for-sale (“AFS”) and mortgage loans within Insurance Solutions.
•During the nine months ended September 30, 2025, cash provided by investing activities primarily reflects the net assets acquired from the reverse acquisition of TURN, and sales, maturities and repayment of investments, partially offset by purchase of investments, mainly available-for-sale (“AFS”) and mortgage loans within Insurance Solutions.
Financing Activities
Our financing activities reflect our capital market transactions and transactions with equity holders. The primary sources of cash within financing activities primarily include proceeds from debt issuances and proceeds from direct writing and/or reinsurance of MYGA. The primary uses of cash within financing activities include dividends payments and repayments of debt.
•During the nine months ended September 30, 2026, cash used in financing activities primarily reflects payment of dividends, repurchase of common shares, repayment of borrowings and the payment of debt issuance costs in the Asset Management segment. Surrenders or benefit payments related to MYGA policies (classified as investment-type contracts) as well as repayment of borrowings within the Insurance Solutions segment also contributed to the use of cash. These outflows were partially offset by deposits from MYGA direct writing in Insurance Solutions and the issuance of exchange listed notes by the Asset Management segment.
•During the nine months ended September 30, 2025, cash provided by financing activities primarily reflects deposits from the assumption of the NSG MYGA block as well as increased borrowings in the Insurance Solutions segment. These inflows were partially offset by surrenders or benefit payments related to MYGA policies (classified as investment-type contracts) within the Insurance Solutions segment, and the repayment of debt within the Asset Management segment, payment of dividends and repurchase of common shares.
Contractual Obligations, Commitments and Contingencies
For a summary and a description of the nature of Mount Logan’s commitments, contingencies and contractual obligations, see Note 24. Commitments and contingencies to the Condensed Consolidated Financial Statements.
Consolidated VIEs
Mount Logan manages its liquidity needs by evaluating unconsolidated cash flows; however, Mount Logan’s financial statements reflect the financial position of Mount Logan as well as consolidated VIEs. The primary sources and uses of cash at Mount Logan's consolidated VIEs include: (a) proceeds from sales, maturities and repayments of investments and (b) purchase of investments.
98
Dividends and Distributions
For information regarding the quarterly dividends that were made to common shareholders and distribution equivalents on participating securities, see Note 19. Equity to the Condensed Consolidated Financial Statements. Although Mount Logan currently expects to pay dividends, Mount Logan may not pay dividends if, among other things, Mount Logan does not have the cash necessary to pay the dividends. To the extent it does not have sufficient cash on hand to pay dividends, Mount Logan may have to borrow funds to pay dividends, or it may determine not to pay dividends. The primary source of funds for dividends is distributions from Mount Logan’s operating subsidiaries, which are expected to be adequate to fund dividends and other cash flow requirements based on current estimates of future obligations. The ability of these operating subsidiaries to make distributions to Mount Logan will depend on satisfying applicable law with respect to such distributions, including surplus and minimum solvency requirements among others.
On March 5, 2026 Mount Logan declared a cash dividend of US$0.03 per share of its common stock, which was paid on April 15, 2026, to holders of record at the close of business on March 30, 2026. On May 14, 2026 Mount Logan declared a cash dividend in the amount of US$0.03 per common share to be paid on June 10, 2026 to shareholders of record on May 26, 2026. On August 11, 2026 Mount Logan declared a cash dividend of US$0.03 per common share to be paid on August 31, 2026 to holders of record at the close of business on August 21, 2026.
Asset Management Liquidity
Mount Logan’s Asset Management business requires limited capital resources to support the working capital or operating needs of the business. For the Asset Management business’s longer term liquidity needs, Mount Logan expects to continue to fund the Asset Management business’s operations through management fees and performance fees received. Liquidity needs are also met through proceeds from borrowings and equity issuances as described in Note 12. Debt obligations and Note 19. Equity to the Condensed Consolidated Financial Statements, respectively. From time to time, if Mount Logan determines that market conditions are favorable after taking into account Mount Logan’s liquidity requirements, we may seek to raise proceeds through the issuance of additional debt or equity instruments.
At September 30, 2026, the Asset Management business had $3.1 million of unrestricted cash and cash equivalents.
Future Debt Obligations
The Asset Management business had long-term debt outstanding of $98.6 million at September 30, 2026, which includes notes with maturities in 2027, 2031 and 2032. There are also scheduled incremental repayments of principal on the credit facility in 2026. See Note 12. Debt obligations to the Condensed Consolidated Financial Statements for further information regarding the Asset Management business’s debt arrangements.
Future Cash Flows
Mount Logan’s ability to execute Mount Logan’s business strategy, particularly Mount Logan’s ability to increase Mount Logan’s AUM, depends on Mount Logan’s ability to establish new funds and to raise additional investor capital within such funds. Mount Logan’s liquidity will depend on a number of factors, such as Mount Logan’s ability to project our financial performance, which is highly dependent on the funds it manages and its ability to manage our projected costs, fund performance, access to credit facilities, compliance with the existing credit agreement, as well as industry and market trends. Also, during economic downturns the funds Mount Logan manages might experience cash flow issues or liquidate entirely. In these situations, Mount Logan might be asked to reduce or eliminate the management fee and incentive fees it charges, which could adversely impact Mount Logan’s cash flow in the future. An increase in the fair value of the investments of the funds Mount Logan manages, by contrast, could favorably impact its liquidity through higher management fees where the management fees are calculated based on the net asset value, gross assets or adjusted assets. Additionally, higher incentive fees not yet realized would generally result when investments appreciate over their cost basis which would not have an impact on the Asset Management business’s cash flow until realized.
Consideration of Financing Arrangements
As noted above, the Asset Management business has and may continue to issue debt to supplement its liquidity. The decision to enter into a particular financing arrangement is made after careful consideration of various factors,
99
including the Asset Management business’s cash flows from operations, future cash needs, current sources of liquidity, demand for the Asset Management business’s debt or parent's equity, and prevailing interest rates.
Executed Transactions
Yieldstreet Alternative Income Fund Inc. Transaction Services and Sub-advisory Agreements
As previously disclosed, on March 18, 2026, the Opportunistic Credit Interval Fund (“SOFIX”), a fund managed by ML Management, entered into definitive agreements with ML Management and Willow Asset Management LLC (“Willow”) to acquire the assets and assume the liabilities of Yieldstreet Alternative Income Fund (“YS AIF”) (the “Asset Acquisition”) from Willow. In connection with the Asset Acquisition, ML Management entered into a Transition Services Agreement (“TSA”) with Willow, the advisor of YS AIF, pursuant to which Willow will provide access to books and records of YS AIF, certain transition services and licenses in exchange for aggregate consideration of up to $5 million. Additionally, ML Management entered into the Sub-Advisory Agreement with Willow making ML Management a sub-advisor to the YS AIF. Under the Sub-Advisory Agreement, ML Management acts as non-discretionary sub-adviser to a legacy private credit fund portfolio managed by Willow, unrelated to the YS AIF assets, in exchange for a sub-advisory fee. The $5 million of consideration the Company will pay to Willow is payable in $2 million in cash, $1 million in shares of the Company’s common stock and $2 million payable as rebates against fees otherwise due to ML Management under the Sub-Advisory Agreement. This transaction closed on August 24, 2026.
The Company concluded the YS AIF assets acquired under the TSA do not meet the definition of a business under ASC 805-10-55-3A through 55-9, as no workforce, substantive process, or output-generating capability transferred to the Company. Accordingly, the transaction is accounted for as an asset acquisition under ASC 805-50. Total consideration was allocated between (i) an intangible asset, representing the YS AIF assets and the associated license, and (ii) the transition services, on a relative-fair-value basis in accordance with ASC 805-50-30-3. The transition services are expensed as consumed over the two-year service period. The intangible asset was valued using an income approach (with or without), as no observable market exists for a comparable asset. The intangible asset has an indefinite life and therefore will be assessed for impairment on an annual basis.
The $1.0 million in MLCI restricted shares issued to Willow is accounted for under ASC 718 as consideration for the YS AIF assets, license, and transition services received, measured at grant-date fair value as of the YS AIF Transaction Closing Date, without a discount for lack of marketability and allocated between the intangible asset and transition services consistent with the allocation described above.
The Company may pay up to $2.0 million in additional TSA consideration in the form of rebates against Sub-Advisory Fees otherwise payable by Willow. This consideration is not accounted for as a reduction of the amount of Sub-Advisory Fee revenue under ASC 606 as the payment is for a distinct service. As of September 30, 2026, none of the rebate had been recognized as additional consideration. See Note 3. Business Combinations and Asset Acquisitions to the Condensed Consolidated Financial Statements for further detail.
As of September 30, 2026, the carrying value of the intangible asset recognized in connection with this transaction was $2.8 million, and it is not impaired as of the three months ended September 30, 2026. See Note 11. Goodwill and intangible assets, Intangible assets for further detail.
Alternative Credit Income Fund (“ACIF”) completed merger with BC Partners Lending Corporation (“BCPL”)
As previously disclosed, effective September 29, 2026, ACIF merged with and into BCPL and ACIF did not survive. In connection with the ACIF Merger, (i) SCIM and BCPA, the investment adviser to BCPL, entered into a Revenue Share Agreement under which BCPA pays 29.88% of the management and incentive fees it receives under its investment advisory agreement with BCPL to SCIM, net of the allocable compensation costs of the BCPL sales force, (the "Revenue Share Amount"); and (ii) SCIM and Mount Logan Capital US Holdings LLC ("MLC USH"), a wholly owned consolidated subsidiary of the Company, entered into an Assignment and Cancellation Agreement (the "Cancellation Agreement") under which SCIM's rights to the Revenue Share Amount were assigned to MLC USH in exchange for the cancellation of the SCIM Note. While SCIM served as the investment manager of ACIF, the Company was entitled to 100% of the economics of ACIF despite the Company’s 24.99% ownership percentage in SCIM.
The cancellation of the SCIM Note involved the Company to write off the principal balance of the SCIM Note and its associated CECL allowance. The SCIM Note had a $13.6 million principal balance and a $0.3 million CECL allowance as of September 30, 2026. Upon cancellation of the SCIM Note, the Company recognized the Revenue Share Amount as an intangible asset at an estimated value of $12.2 million. This exchange of the SCIM Note for the Revenue Share Amount
100
caused the Company to recognize a loss from investment activities of $1.1 million for the three and nine month period ended September 30, 2026.
In addition to the exchange of the SCIM Note for the Revenue Share Amount, the Company had $3.8 million of accrued interest receivable attributable to the SCIM Note as of September 30, 2026. The Company had also accrued a $7.2 million payable due to SCIM resulting from the negative economics of ACIF (the “ACIF Economics Payable”) as of September 30, 2026. The $3.8 million in accrued interest receivable and the $7.2 million ACIF Economics Payable were netted against each other, with the remaining $3.4 million balance still owed to SCIM by the Company. The Company will make quarterly payments to SCIM using one third of the Revenue Share Amount that the Company receives every quarter. This transaction was executed on September 29, 2026, refer to Note 3. Business Combinations and Asset Acquisitions in the Condensed Consolidated Financial Statements for further detail.
Reinsurance Recapture
Effective September 1, 2026, Sentinel Security Life Insurance Company (“SSL”) recaptured 50% of the quota share liability previously reinsured by Ability Insurance Company (“Ability”) on contracts issued and approved from July 1, 2022 through June 30, 2024 (the “Recaptured Business”). The remaining 50% of the quota share on those contracts ceded under the Reinsurance Agreement, remains in force on its existing terms.
Statutory reserves attributable to the Recaptured Business were $141.4 million as of August 31, 2026, of which $70.7 million related to the recaptured 50%. Ability transferred assets from the trust account maintained under the Reinsurance Agreement to SSL with an aggregate fair value of $68.3 million. This amount represents the recaptured statutory reserves, net of a recapture fee of $2.4 million retained by the Company. The recapture fee was settled by netting against the assets transferred and was not paid separately in cash.
The Company derecognized the related reinsurance liabilities included in interest sensitive contract liabilities of $70.2 million. Because the interest sensitive contract liabilities were $0.6 million lower than the corresponding statutory reserves, the derecognition resulted in a loss of $0.6 million. Together with the $2.4 million recapture fee earned, Ability recognized a net gain of $1.8 million, included in other income within insurance segment revenue for the three months ended September 30, 2026.
Pending Transactions
In October 2026, the Company has entered into a definitive agreement to become the new investment advisor to the Alternative Fund Advisors, LLC (“AFA”) Asset Based Lending Fund (“Fund”) (the “Transaction”). In connection with the Transaction, the Company and AFA, who is the Fund’s current investment advisor, have entered into an Asset Purchase Agreement (“APA”) pursuant to which the Company will acquire certain business records, intellectual property, and goodwill of AFA related to the management of the Fund. The Fund will be the Company’s second evergreen credit interval fund, complementing the Company’s Opportunistic Credit Interval Fund. The Transaction is expected to close in January 2027.
Insurance Solutions Liquidity and funding risk
Liquidity risk is the risk that an entity will encounter difficulty in meeting obligations associated with its financial liabilities as they fall due or can only do so on terms that are materially disadvantageous. Prudent liquidity risk management includes maintaining sufficient cash on hand and the availability of funding through an adequate amount of committed credit facilities. Mount Logan also has the ability to raise additional liquidity through the issuance of debt, and through the sale of its portfolio investments. Periodic cash flow forecasts are performed to ensure Ability has sufficient cash to meet operational and financing costs.
101
Liquid assets
Liquid assets, including high-quality assets that are marketable, can be pledged as security for borrowings, and can be converted to cash in a time frame that meets liquidity and funding requirements.
| As of | September 30, 2026 | December 31, 2025 | ||||||||||||
Cash and cash equivalents1 | $ | 57,277 | $ | 118,753 | ||||||||||
| Restricted cash | 19,241 | 9,973 | ||||||||||||
| Investments | 576,349 | 639,221 | ||||||||||||
| Receivable for investments sold | 1,651 | — | ||||||||||||
Accrued interest and dividend receivable1 | 13,112 | 12,596 | ||||||||||||
| Total liquid assets | $ | 667,630 | $ | 780,543 | ||||||||||
_______________
(1)Cash and cash equivalents and accrued interest & dividend receivable includes cash and cash equivalent and accrued interest of consolidated VIEs, respectively.
The liquid assets held by Mount Logan's insurance company, Ability, are subject to restrictions which prevent Mount Logan from transferring these assets to other entities within the group without insurance regulatory approvals. These assets are not restricted for use within the insurance company.
Insurance Subsidiaries’ Operating Liquidity
The primary cash flow sources for Ability include retirement services product inflows, investment income, and principal repayments on its investments. Uses of cash include investment purchases, payments to policyholders for surrenders, withdrawals and payout benefits, interest and principal payments on funding agreements and outstanding debt, policy acquisition and general operating costs.
Ability’s policyholder obligations are generally long-term in nature. However, policyholders may elect to withdraw some, or all, of their account value in amounts that exceed Ability’s estimates and assumptions over the life of an annuity contract. Ability includes provisions within its annuity policies, such as surrender charges and market value adjustments, which are intended to protect it from early withdrawals. As of September 30, 2026, and September 30, 2025, approximately 77% of Ability’s MYGA policies were subject to penalty upon surrender. In addition, as of September 30, 2026, and September 30, 2025, approximately 94% and 60%, respectively, of policies contained Market Value Adjustments (“MVAs”) that may also have the effect of limiting early withdrawals if interest rates increase but may encourage early withdrawals by effectively subsidizing a portion of surrender charges when interest rates decrease.
Dividends from Insurance Subsidiaries
The NAIC has established minimum capital requirements in the form of RBC that factors the type of business written by an insurance company, the quality of its assets and various other aspects of its business to develop a minimum level of capital known as “authorized control level risk-based capital” and compares this level to adjusted statutory capital that includes capital and surplus as reported under SAP, plus certain investment reserves. Should the ratio of adjusted statutory capital to control level RBC fall below 200%, a series of remedial actions by the affected company would be required. As of December 31, 2025, and 2024, the RBC ratio of Ability was 501% and 325% , respectively.
The ability to pay dividends is limited by applicable laws and regulations of the jurisdiction where Ability is domiciled, as well as agreement(s) entered into with regulators. These laws and regulations require, among other things, Ability to maintain minimum solvency requirements and limit the amount of dividends Ability can pay. Nebraska state insurance laws and regulations require that the statutory surplus following any dividend or distribution must be reasonable in relation to their outstanding liabilities and adequate for its financial needs.
Future Debt Obligations
Ability had long-term debt of $12.0 million as of September 30, 2026, which includes notes with maturities in 2032. See Note 12. Debt obligations to the Condensed Consolidated Financial Statements for further information regarding Ability’s debt arrangements.
102
Capital
Ability believes it has a strong capital position and is well positioned to meet policyholder and other obligations. Ability measures capital sufficiency using various internal capital metrics which reflect management’s view on the various risks inherent to its business, the amount of capital required to support its core operating strategies and the amount of capital necessary to maintain its current ratings in a recessionary environment. The amount of capital required to support Ability’s core operating strategies is determined based upon internal modeling and analysis of economic risk, as well as inputs from rating agency capital models and consideration of NAIC RBC requirements. Capital in excess of this required amount is considered excess equity capital, which is available to deploy. As of December 31, 2025, and December 31, 2024, Ability’s RBC ratio was 501% and 325%, respectively. The formulas for determining the amount of RBC specify various weighting factors that are applied to financial balances or various levels of activity based on the perceived degree of risk.
Critical Accounting Estimates
This Management’s Discussion and Analysis of Financial Condition and Results of Operations is based upon the Condensed Consolidated Financial Statements, which have been prepared in accordance with U.S. GAAP. The preparation of financial statements in accordance with U.S. GAAP requires the use of estimates and assumptions that could affect the reported amounts of assets and liabilities, the disclosure of contingent assets and liabilities and the reported amounts of revenues and expenses. Actual results could differ from these estimates. A summary of our significant accounting policies is presented in Note 2. Summary of significant accounting policies to our Condensed Consolidated Financial Statements. The following is a summary of our accounting policies that are affected most by judgments, estimates and assumptions.
Critical Accounting Estimates - Overall
Consolidation
Mount Logan assesses all entities in which Mount Logan has a variable interest for consolidation including management companies, insurance companies, investment companies, CLOs, and other entities. A variable interest is an investment or other interest that will absorb portions of an entity’s expected losses and/or receive expected residual returns. Fees earned by Mount Logan that (i) include terms, conditions, or amounts that are customarily present in arrangements for similar services negotiated at arm’s length, (ii) are commensurate with the level of effort required to provide those services, and (iii) where Mount Logan does not hold other economic interests in the entity that would absorb more than an insignificant amount of the expected losses or returns of the entity, would not be considered to be variable interests.
Pursuant to its consolidation policy, once Mount Logan determines it has a variable interest in an entity, Mount Logan considers whether the entity is a VIE. Entities that do not qualify as VIEs are assessed for consolidation as voting interest entities (“VOEs”) under the voting interest model.
An entity is a VIE if one of the following conditions exist: (a) the equity at risk is not sufficient for the entity to finance its activities without additional subordinated financial support, (b) the holders of the equity at risk (as a group) lack the ability to make decisions about the activities that most significantly impact the entity’s economic performance, or (c) the voting rights of some investors are disproportionate to their obligation to absorb the expected losses of the legal entity, their rights to receive the expected residual returns of the legal entity, or both and substantially all of the legal entity's activities either involve or are conducted on behalf of an investor with disproportionately few voting rights. Limited partnerships and other similar entities where limited partners, not affiliated with the general partner, have not been granted (i) substantive participation rights or (ii) substantive rights to either dissolve the partnership or remove the general partner are VIEs.
Mount Logan consolidates VIEs in which it is the primary beneficiary. Mount Logan is the primary beneficiary if it holds a controlling financial interest which is defined as possessing both (a) the power to direct the activities of a VIE that most significantly impact the VIE's economic performance and (b) the obligation to absorb losses of the VIE or the right to receive benefits from the VIE that could potentially be significant to the VIE. Mount Logan determines whether it is the primary beneficiary of a VIE at the time it becomes involved with a VIE and reconsiders that conclusion on an ongoing basis if facts and circumstances change.
Entities determined not to be VIEs are VOEs and are evaluated under the voting interest model. Mount Logan typically consolidates VOEs when it has a majority voting interest.
103
Each entity is assessed for consolidation individually considering the specific facts and circumstances surrounding that entity. The consolidation assessment, including the determination whether an entity is a VIE or VOE, depends on the facts and circumstances for each entity, and therefore Mount Logan’s investment companies may qualify as VIEs or VOEs.
With respect to CLOs (which are generally VIEs), as collateral manager, Mount Logan generally has the power to direct the activities of the CLO that most significantly impact the CLO’s economic performance. In some, but not all cases, Mount Logan, through its ownership in the CLOs, may have variable interests that represent an obligation to absorb losses of, or a right to receive benefits from, the CLO that could potentially be significant to the CLO. In cases where Mount Logan has both the power to direct the activities of the CLO that most significantly impact the CLO’s economic performance and the obligation to absorb losses of the CLO or the right to receive benefits from the CLO that could potentially be significant to the CLO, Mount Logan is deemed to be the primary beneficiary and consolidates the CLO.
Assets and liabilities of the consolidated VIEs are primarily presented in separate sections within the Condensed Consolidated Statements of Financial Position. Changes in the fair value of the consolidated VIEs’ assets and liabilities and related interest, dividend and other income and expenses are primarily presented within revenues of consolidated variable interest entities and Income of consolidated variable interest entities, for the Asset Management and Insurance Solutions segments, respectively, in the Condensed Consolidated Statements of Operations.
Income Taxes
Significant judgment is required in determining tax expense and in evaluating certain and uncertain tax positions. Mount Logan recognizes the tax benefit of uncertain tax positions when the position is “more likely than not” to be sustained upon examination, including resolution of any related appeals or litigation processes, based on the technical merits of the position. The tax benefit is measured as the largest amount of benefit that has a greater than 50% likelihood of being realized upon ultimate settlement. If a tax position is not considered more likely than not to be sustained, then no benefits of the position are recognized. Mount Logan’s tax positions are reviewed and evaluated quarterly to determine whether Mount Logan has uncertain tax positions that require financial statement recognition.
Deferred tax assets and liabilities are recognized for the expected future tax consequences of differences between the carrying amount of assets and liabilities and their respective tax bases using currently enacted tax rates. The effect on deferred tax assets and liabilities of a change in tax rates is recognized in income in the period during which the change is enacted. Deferred tax assets are reduced by a valuation allowance when it is more likely than not that all or a portion of the deferred tax assets will not be realized.
Critical Accounting Estimates - Asset Management Segment
Investments, at Fair Value
On a quarterly basis, Mount Logan utilizes a valuation committee consisting of members from senior management, to review and approve the valuation results related to the investments of the funds ML Management manages. Mount Logan also retains external valuation firms to provide third-party valuation consulting services to Mount Logan, which consist of certain limited procedures that management identifies and requests them to perform. The limited procedures provided by the external valuation firms assist management with validating their valuation results or determining fair value. Mount Logan performs various back-testing procedures to validate their valuation approaches, including comparisons between expected and observed outcomes, forecast evaluations and variance analyses. However, because of the inherent uncertainty of valuation, the estimated values may differ significantly from the values that would have been used had a ready market for the investments existed, and the differences could be material. The fair values of the investments in the funds Mount Logan manages can be impacted by changes to the assumptions used in the underlying valuation models. There have been no material changes to the valuation approaches utilized during the periods that Mount Logan’s financial results are presented in this report.
Fair Value of Financial Instruments
Except for Mount Logan’s debt obligations (each as defined in Note 12. Debt obligations to Mount Logan’s Condensed Consolidated Financial Statements), Mount Logan's financial instruments are recorded at fair value or at amounts whose carrying values approximate fair value. See “Investments, at Fair Value” above. While Mount Logan's valuations of portfolio investments are based on assumptions that Mount Logan believes are reasonable under the
104
circumstances, the actual realized gains or losses will depend on, among other factors, future operating results, the value of the assets and market conditions at the time of disposition, any related transaction costs and the timing and manner of sale, all of which may ultimately differ significantly from the assumptions on which the valuations were based. Financial instruments’ carrying values generally approximate fair value because of the short-term nature of those instruments or variable interest rates related to the borrowings.
Revenue Recognition
Management Fees
ML Management provides investment management services to investment funds, CLOs, and other vehicles in exchange for a management fee. Management fees are determined quarterly using an annual rate which are generally based upon (i) a percentage of the capital committed during the commitment period, and thereafter based on the remaining invested capital of unrealized investments, or (ii) net asset value, gross assets, or as otherwise provided in the respective agreements. Management fees are recognized over time, during the period in which the related services are performed.
Incentive Fees
ML Management provides investment management services to investment funds, CLOs, managed accounts and other vehicles in exchange for a management fee, as discussed above and, in some cases an incentive fee, a type of performance revenue. The incentive fee consists of two parts: (i) an income incentive fee which is based on pre-incentive fee net investment income in excess of a hurdle rate and (ii) a capital gains incentive fee which is based on cumulative realized capital gains and losses and unrealized capital depreciation. Incentive fees are considered a form of variable consideration as they are based on the fund achieving certain investment return hurdles. Accordingly, the recognition of such fee is deferred until it is probable that a significant reversal in the amount of cumulative revenue will not occur, which is generally upon liquidation of the investment fund.
Critical Accounting Estimates - Insurance Solutions Segment
Investments
Mount Logan is responsible for the fair value measurement of investments presented in the Condensed Consolidated Financial Statements. Mount Logan performs regular analysis and review of its valuation techniques, assumptions and inputs used in determining fair value to evaluate if the valuation approaches are appropriate and consistently applied, and the various assumptions are reasonable. Mount Logan also performs quantitative and qualitative analysis and review of the information and prices received from commercial pricing services and broker-dealers, to verify it represents a reasonable estimate of the fair value of each investment. In addition, Mount Logan uses both internally-developed and commercially-available cash flow models to analyze the reasonableness of fair values using credit spreads and other market assumptions, where appropriate. For investment funds, Mount Logan typically recognizes its investment, including those for which it has elected the fair value option, based on net asset value information provided by the general partner or related asset manager. For a discussion of investment funds for which it has elected the fair value option, see Note 9. Fair value measurements to the Condensed Consolidated Financial Statements.
105
Valuation of Fixed Maturity Securities, Equity Securities and Mortgage Loans
The following tables presents the fair value of fixed maturity securities, equity securities and mortgage loans, including those with related parties and those held by consolidated VIEs, by fair value hierarchy. Investments classified as Equity Method for which the Fair Value Option (“FVO”) has not been elected have been excluded from the table below:
| Fair Value Measurements | ||||||||||||||||||||||||||||||||
| September 30, 2026 | Level 1 | Level 2 | Level 3 | NAV | Total | |||||||||||||||||||||||||||
| Financial assets | ||||||||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||||||||
| Equity securities | $ | 615 | $ | — | $ | 6,085 | $ | — | $ | 6,700 | ||||||||||||||||||||||
| Derivatives | — | — | — | — | — | |||||||||||||||||||||||||||
| Other invested assets | — | — | 68 | — | 68 | |||||||||||||||||||||||||||
| Total financial assets — Asset Management | 615 | — | 6,153 | — | 6,768 | |||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||
| Debt securities: | ||||||||||||||||||||||||||||||||
| U.S. government and agency | — | 9,362 | — | — | 9,362 | |||||||||||||||||||||||||||
| U.S. state, territories and municipalities | — | 4,161 | — | — | 4,161 | |||||||||||||||||||||||||||
| Other government and agency | — | 2,366 | — | — | 2,366 | |||||||||||||||||||||||||||
| Corporate | — | 233,844 | 7,110 | — | 240,954 | |||||||||||||||||||||||||||
| Asset and mortgage-backed securities | — | 282,690 | 37,012 | — | 319,702 | |||||||||||||||||||||||||||
| Corporate loans | — | 17,732 | 93,301 | — | 111,033 | |||||||||||||||||||||||||||
| Equity securities | 129 | 2,195 | 317 | 1,760 | 4,401 | |||||||||||||||||||||||||||
| Other invested assets | — | 10,014 | 4,480 | 277 | 14,771 | |||||||||||||||||||||||||||
| Total financial assets — Insurance Solutions | 129 | 562,364 | 142,220 | 2,037 | 706,750 | |||||||||||||||||||||||||||
| Corporate loans of consolidated VIEs | — | — | 127,630 | — | 127,630 | |||||||||||||||||||||||||||
| Equity of consolidated VIEs | — | — | 1,051 | — | 1,051 | |||||||||||||||||||||||||||
| Total financial assets including consolidated VIEs | 129 | 562,364 | 270,901 | 2,037 | 835,431 | |||||||||||||||||||||||||||
| Derivatives | — | — | — | — | — | |||||||||||||||||||||||||||
| Total financial assets | $ | 744 | $ | 562,364 | $ | 277,054 | $ | 2,037 | $ | 842,199 | ||||||||||||||||||||||
| Financial liabilities | ||||||||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||
| Ceded reinsurance - embedded derivative | — | 38,894 | — | — | 38,894 | |||||||||||||||||||||||||||
| Interest rate swaps | — | 11,596 | — | — | 11,596 | |||||||||||||||||||||||||||
| Total financial liabilities — Insurance Solutions | — | 50,490 | — | — | 50,490 | |||||||||||||||||||||||||||
| Total financial liabilities | $ | — | $ | 50,490 | $ | — | $ | — | $ | 50,490 | ||||||||||||||||||||||
106
107
| Fair Value Measurements | ||||||||||||||||||||||||||||||||
| December 31, 2025 | Level 1 | Level 2 | Level 3 | NAV | Total | |||||||||||||||||||||||||||
| Financial assets | ||||||||||||||||||||||||||||||||
| Asset Management | ||||||||||||||||||||||||||||||||
| Equity securities | $ | 3,834 | $ | 91 | $ | 6,484 | $ | — | $ | 10,409 | ||||||||||||||||||||||
| Derivatives | — | — | 13 | — | 13 | |||||||||||||||||||||||||||
| Other invested assets | — | — | 72 | — | 72 | |||||||||||||||||||||||||||
| Total financial assets — Asset Management | 3,834 | 91 | 6,569 | — | 10,494 | |||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||
| Debt securities: | ||||||||||||||||||||||||||||||||
| U.S. government and agency | — | 10,348 | — | — | 10,348 | |||||||||||||||||||||||||||
| U.S. state, territories and municipalities | — | 5,354 | — | — | 5,354 | |||||||||||||||||||||||||||
| Other government and agency | — | 2,475 | — | — | 2,475 | |||||||||||||||||||||||||||
| Corporate | — | 261,039 | 10,149 | — | 271,188 | |||||||||||||||||||||||||||
| Asset and mortgage-backed securities | — | 323,246 | 19,427 | — | 342,673 | |||||||||||||||||||||||||||
| Corporate loans | — | 7,499 | 116,568 | — | 124,067 | |||||||||||||||||||||||||||
| Equity securities | 7,644 | 2,246 | 3,240 | 1,923 | 15,053 | |||||||||||||||||||||||||||
| Other invested assets | — | 51 | 5,637 | 299 | 5,987 | |||||||||||||||||||||||||||
| Total financial assets — Insurance Solutions | 7,644 | 612,258 | 155,021 | 2,222 | 777,145 | |||||||||||||||||||||||||||
| Corporate loans of consolidated VIEs | — | — | 119,731 | — | 119,731 | |||||||||||||||||||||||||||
| Equity securities of consolidated VIEs | — | — | 949 | — | 949 | |||||||||||||||||||||||||||
| Total financial assets including consolidated VIEs | 7,644 | 612,258 | 275,701 | 2,222 | 897,825 | |||||||||||||||||||||||||||
| Derivatives | — | 481 | — | — | 481 | |||||||||||||||||||||||||||
| Total financial assets | $ | 11,478 | $ | 612,830 | $ | 282,270 | $ | 2,222 | $ | 908,800 | ||||||||||||||||||||||
| Financial liabilities | ||||||||||||||||||||||||||||||||
| Insurance Solutions | ||||||||||||||||||||||||||||||||
| Ceded reinsurance - embedded derivative | — | 29,650 | — | — | 29,650 | |||||||||||||||||||||||||||
| Interest rate swaps | — | 1,388 | — | — | 1,388 | |||||||||||||||||||||||||||
| Total financial liabilities — Insurance Solutions | — | 31,038 | — | — | 31,038 | |||||||||||||||||||||||||||
| Total financial liabilities | $ | — | $ | 31,038 | $ | — | $ | — | $ | 31,038 | ||||||||||||||||||||||
Goodwill
We review goodwill for impairment annually and whenever events or changes in the business environment may indicate the carrying amount of one of our reporting units may exceed its fair value. Our methodology for conducting this goodwill impairment testing contains both a qualitative and quantitative assessment. In evaluating the recoverability of goodwill, we perform a qualitative analysis at the reporting unit level to determine whether there are any events or circumstances that would indicate it is more likely than not that the fair value of a reporting unit is below its carrying value. Based on the results of this analysis, if we determine that it is more likely than not that the fair value of a reporting unit is less than its carrying amount, we then perform the impairment evaluation using a quantitative assessment based on an analysis of the discounted future cash flows generated by the underlying assets. The process of determining whether goodwill is impaired or recoverable relies on projections of future cash flows, operating results and market conditions. Future cash flow estimates are based partly on economic trends such as interest rates and market conditions, which are beyond our control and are likely to fluctuate. While we believe that our estimates of future cash flows are reasonable, these estimates are not guarantees of future performance and are subject to risks and uncertainties that may cause actual results to differ from what is assumed in our impairment tests. Such analyses are particularly sensitive to changes in estimates of future cash flows and discount rates. Changes to these estimates might result in material changes in fair value and determination of the recoverability of goodwill, which may result in charges against earnings and a reduction in the carrying value of our goodwill in the future. We complete our annual goodwill impairment analyses in the fourth quarter of each period presented using an October 1 measurement date. For the year ended December 31, 2025 we performed our annual quantitative goodwill impairment test for our reporting units, LTC and MYGA. As of such date, we noted that the carrying value of the LTC reporting unit exceeded its estimated fair value, which resulted in recording a $25.5 million charge to fully impair the goodwill associated with the LTC reporting unit. The excess carrying value of the LTC reporting unit was primarily driven by an increase in its net assets resulting from lower recorded long‑term care (LTC) reserves
108
following a change in the accounting basis from IFRS to U.S. GAAP. Under U.S. GAAP, the revised reserving methodology reduced the level of recognized LTC reserves, thereby increasing the carrying value of the reporting unit. Consequently, the carrying value exceeded the estimated fair value as of the measurement date, resulting in the impairment. In contrast, the fair value of MYGA reporting unit exceeded its respective carrying value by 30.6%.
Derivatives
Freestanding derivatives are instruments that Ability has entered into as part of their overall risk management strategies. Such contracts include interest rate swaps to convert floating-rate interest receipts to fixed-rate interest receipts to reduce exposure to interest rate changes. All derivatives are recognized either as a Derivatives asset or Derivatives liability and are presented on a gross basis in the Condensed Consolidated Statements of Financial Position and measured at fair value unless there is a legal right of set-off. Changes in fair value are recorded in AOCI as the swaps are in hedging relationships, with changes in fair value reclassified into Interest income in the same period as the hedged transactions affect earnings. Any interest accruals will flow through earnings as adjustments to Interest income. Ability’s derivative financial instruments contain credit risk to the extent that its counterparties may be unable to meet the terms of the agreements. Ability attempts to reduce this risk by limiting its counterparties to major financial institutions with strong credit ratings.
To qualify for hedge accounting, at the inception of the hedging relationship, Ability formally documents its risk management objective and strategy for undertaking the hedging transaction. This documentation identifies how the hedging instrument is expected to mitigate the designated risk related to the hedged item and the method that will be used to retrospectively and prospectively assess the hedge effectiveness. A derivative designated as a hedging instrument must be assessed as being highly effective in offsetting the designated risk of the hedged item. Hedge effectiveness is formally assessed at inception and periodically throughout the life of the hedge accounting relationship.
Ability issues and reinsures products or purchases investments that contain embedded derivatives. If it determines an embedded derivative has economic characteristics not clearly and closely related to the economic characteristics of the host contract, and a separate instrument with the same terms would qualify as a derivative instrument, the embedded derivative is bifurcated from the host contract and accounted for separately, unless the Fair Value Option (“FVO”) is elected on the host contract. Under the FVO, bifurcation of the embedded derivative is not necessary as the entire contract is carried at fair value with all related gains and losses recognized in Net realized and change in unrealized gains (losses) from investment activities in the Condensed Consolidated Statements of Operations. Embedded derivatives are carried at fair value in the Condensed Consolidated Statements of Financial Position in the same line item as the host contract.
Additionally, reinsurance agreements written on a funds withheld or Modco basis contain embedded derivatives. Ability has determined that the obligation to pay the total return on the assets supporting the funds withheld liability represents a total return swap with a floating rate leg. The fair value of embedded derivatives on funds withheld and Modco agreements is computed as the unrealized gain (loss) on the underlying assets and is included within the funds withheld under reinsurance contracts in the Condensed Consolidated Statements of Financial Position.
The change in the fair value of the embedded derivatives is recorded in “Net investment income (loss) on funds withheld” in the Condensed Consolidated Statements of Operations. Ceded earnings from funds withheld liability and changes in the fair value of embedded derivatives are reported in operating activities in the Condensed Consolidated Statements of Cash Flows. Contributions to and withdrawals from funds withheld liability are reported in operating activities in the Condensed Consolidated Statements of Cash Flows.
Ability’s insurance operations include providing reinsurance related to LTC, as well as MYGA products. Insurance contracts are contracts with significant mortality and/or morbidity risks, while investment contracts are contracts without such risks. MYGA contracts were deemed to be investment contracts. Insurance revenue is comprised primarily of premiums and investment income. For traditional long-duration insurance contracts, Mount Logan reports premiums as revenue when due. Premiums received on MYGA products (a product without significant mortality risk) are not reported as revenue but rather as deposit liabilities. Mount Logan recognizes revenue for charges and assessments on these contracts, mostly relating to surrender charges. Interest credited to policyholder accounts is charged to expense.
Future policy benefit reserves represent the present value of future benefits to be paid to or on behalf of policyholders and related expenses less the present value of future net premiums. The liability is measured for each group of contracts (i.e., cohorts) using current cash flow assumptions. Contracts are grouped into cohorts by line of business, product type and cash flow streams, based on the date the policy was acquired (which for the entire LTC portfolio is the
109
date of the acquisition of Ability). Future policy benefit reserves are adjusted each period because of updating lifetime net premium ratios for differences between actual and expected experience with the retroactive effect of those variances recognized in current period earnings. Ability reviews its future policy benefit reserve cash flow assumptions at least annually, and if the review concludes that the assumptions need to be updated, future policy benefit reserves are adjusted retroactively based on the revised net premium ratio using actual historical experience, updated cash flow assumptions, and the locked-in discount rate with the effect of those changes recognized in current period earnings.
As Ability’s LTC business is in run-off, the locked-in discount rate is used for the computation of interest accretion on future policy benefit reserves recognized in earnings. However, cash flows used to estimate future policy benefit reserves are also discounted using an upper-medium grade (i.e., low credit risk) fixed-income instrument yield reflecting the duration characteristics of the liabilities and is updated each reporting period with changes recorded in AOCI. As a result, changes in the current discount rate at each reporting period are recognized as an adjustment to AOCI and not earnings each period, whereas, changes relating to cash flow assumptions are recognized in the Insurance Solutions Statement of Earnings (Loss).
Liabilities for the MYGA investment contracts equal the account value, that is, the amount that accrues to the benefit of the contract or policyholder including credited interest and assessments through the financial statement date. See Note 15. Interest sensitive contract liabilities to the Condensed Consolidated Financial Statements for further information.
Recent Accounting Pronouncements
A list of recent accounting pronouncements that are relevant to Mount Logan and its industries is included in Note 2. Summary of significant accounting policies to Mount Logan’s Condensed Consolidated Financial Statements.
Item 3. Quantitative and Qualitative Disclosures about Market Risk
We are a smaller reporting company as defined by Rule 12b-2 of the Exchange Act and are not required to provide the information otherwise required under this item.
Item 4. Controls and Procedures
Evaluation of Disclosure Controls and Procedures.
Our management, with the participation of our principal executive officer, principal financial officer, and principal accounting officer, has evaluated the effectiveness of our disclosure controls and procedures (as defined in Rules 13a-15(e) and 15d-15(e) under the Exchange Act), as of the end of the period covered by this Quarterly Report on Form 10-Q. Based on such evaluation, our principal executive officer, principal financial officer, and principal accounting officer have concluded that these disclosure controls were effective at a reasonable assurance level as of September 30, 2026.
Changes in Internal Control Over Financial Reporting.
There have been no changes in our internal control over financial reporting identified in connection with the evaluation required by Rule 13a-15(d) and 15d-15(d) of the Exchange Act during the third quarter of 2026 that have materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
110
PART II - Other Information
Item 1. Legal Proceedings
From time to time, we are involved in various legal proceedings, lawsuits and claims incidental to the conduct of our business. Our business is also subject to extensive regulation, which may result in regulatory proceedings against us. We are not currently party to any material legal proceedings.
111
Item 1A. Risk Factors
As of the date of this Quarterly Report on Form 10-Q, there have been no material changes to the risk factors disclosed in our Annual Report on Form 10-K for the year ended December 31, 2025.
Item 2. Unregistered Sales of Equity Securities and Use of Proceeds
On August 24, 2026, the Company issued 302,115 shares of common stock with an aggregate value of approximately $1.0 million to Willow in connection with the Transition Services Agreement related to the transaction with YS AIF described in Note 3. Business Combinations and Asset Acquisitions to the Condensed Consolidated Financial Statements. The issuance was exempt from registration under Section 4(a)(2) of the Securities Act as a transaction by an issuer not involving a public offering.
On August 24, 2026, in connection with the Sub-Advisory Agreement, in order to induce six employees of Willow to accept employment with BCPA and provide services to the Company pursuant to the existing staffing and servicing agreements between the Company and BCPA, the Company issued restricted stock units representing 199,397 shares of the common stock of the Company to such employees as an “inducement” grant pursuant to Rule 5635(c)(4) of the Nasdaq Listing Rules. The restricted stock units had an aggregate value of approximately $0.6 million, one-third vesting per year on the anniversary date of the grant, subject to the applicable employee’s continued provision of services to the Company. The issuance was exempt from registration under Section 4(a)(2) of the Securities Act as a transaction by an issuer not involving a public offering.
No cash consideration was received by the Company in connection with the issuance of the shares to Willow or the inducement grants described above.
Item 3. Defaults Upon Senior Securities
Not applicable.
Item 4. Mine Safety Disclosures
Not applicable.
Item 5. Other Information
Rule 10b5-1 Trading Plans
During the three months ended September 30, 2026, none of the Company’s directors or Section 16 officers adopted or terminated any “Rule 10b5-1 trading arrangements” or any “non-Rule 10b5-1 trading arrangements” (in each case, as defined in Item 408 of Regulation S-K).
112
Item 6. Exhibits
| Exhibit Number | Description | |||||||
| 2.1 | Agreement and Plan of Merger, dated as of January 16, 2025, by and among Mount Logan Capital Inc., 180 Degree Capital Corp., Yukon New Parent, Inc., Polar Merger Sub, Inc. and Moose Merger Sub, LLC (incorporated herein by reference to Exhibit 2.1 to the registrant’s Current Report on Form 8-K filed September 16, 2025). | |||||||
| 2.2 | Amendment to Agreement and Plan of Merger, dated as of July 6, 2025, by and among Mount Logan Capital Inc., 180 Degree Capital Corp., Yukon New Parent, Inc., Polar Merger Sub, Inc. and Moose Merger Sub, LLC (incorporated herein by reference to Exhibit 2.2 to the registrant’s Current Report on Form 8-K filed September 16, 2025). | |||||||
| 2.3 | Amendment No. 2 to Agreement and Plan of Merger, dated as of August 17, 2025, by and among Mount Logan Capital Inc., 180 Degree Capital Corp., Yukon New Parent, Inc., Polar Merger Sub, Inc. and Moose Merger Sub, LLC (incorporated herein by reference to Exhibit 2.3 to the registrant’s Current Report on Form 8-K filed September 16, 2025). | |||||||
| 3.1 | Amended and Restated Certificate of Incorporation of Mount Logan Capital Inc. (incorporated herein by reference to Exhibit 3.1 to the registrant’s Current Report on Form 8-K filed September 16, 2025). | |||||||
| 3.2 | Amended and Restated Bylaws of Mount Logan Capital Inc. (incorporated herein by reference to Exhibit 3.2 to the registrant’s Current Report on Form 8-K filed September 16, 2025). | |||||||
10.1 | Limited Waiver, Partial Collateral Release and Amendment No. 6, dated as of October 9, 2026, by and among MLC US Holdings LLC, the Lenders party thereto and the Agent party thereto (incorporated herein by reference to Exhibit 10.1 to the registrant’s Current Report on Form 8-K filed October 15, 2026). | |||||||
10.2 | Revenue Share Agreement, dated as of September 29, 2026, by and between BC Partners Advisors L.P. and Sierra Crest Investment Management LLC (incorporated herein by reference to Exhibit 10.2 to the registrant’s Current Report on Form 8-K filed October 15, 2026). | |||||||
10.3 | Assignment and Cancellation Agreement, dated as of September 29, 2026, by and between MLC US Holdings LLC and Sierra Crest Investment Management LLC (incorporated herein by reference to Exhibit 10.3 to the registrant’s Current Report on Form 8-K filed October 15, 2026). | |||||||
10.4 | Asset Purchase Agreement, dated October 19, 2026, by and between Mount Logan Management, LLC and Alternative Fund Advisors, LLC (incorporated herein by reference to Exhibit 10.1 to the registrant’s Current Report on Form 8-K filed October 20, 2026). | |||||||
10.5* | ||||||||
| 31.1* | ||||||||
| 31.2* | ||||||||
| 32.1+ | ||||||||
| 101.INS* | Inline XBRL Instance Document – the instance document does not appear in the Interactive Data File because XBRL tags are embedded within the Inline XBRL document | |||||||
| 101.SCH* | Inline XBRL Taxonomy Extension Schema Document | |||||||
| 101.CAL* | Inline XBRL Taxonomy Extension Calculation Linkbase Document | |||||||
| 101.DEF* | Inline XBRL Taxonomy Extension Definition Linkbase Document | |||||||
| 101.LAB* | Inline XBRL Taxonomy Extension Label Linkbase Document | |||||||
| 101.PRE* | Inline XBRL Taxonomy Extension Presentation Linkbase Document | |||||||
| 104 | Cover Page Interactive Data File (embedded within the Inline XBRL document) | |||||||
* Filed herewith.
+ Furnished herewith. This certification is not deemed filed by the SEC and is not to be incorporated by reference in any filing we make under the Securities Act or the Exchange Act, irrespective of any general incorporation language in any filings.
+ Furnished herewith. This certification is not deemed filed by the SEC and is not to be incorporated by reference in any filing we make under the Securities Act or the Exchange Act, irrespective of any general incorporation language in any filings.
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, as amended, the registrant has duly caused this report to be signed on its behalf by the undersigned thereunto duly authorized.
Mount Logan Capital Inc. | ||||||||
Date: November 10, 2026 | By: | /s/ Ted Goldthorpe | ||||||
Ted Goldthorpe | ||||||||
Chief Executive Officer and Director | ||||||||
(Principal Executive Officer) | ||||||||
Date: November 10, 2026 | By: | /s/ Brandon Satoren | ||||||
Brandon Satoren | ||||||||
Chief Financial Officer and Corporate Secretary | ||||||||
(Principal Financial Officer) | ||||||||